
How Weak Earnings Will Impact Rollins Stock After Citi Upgrade
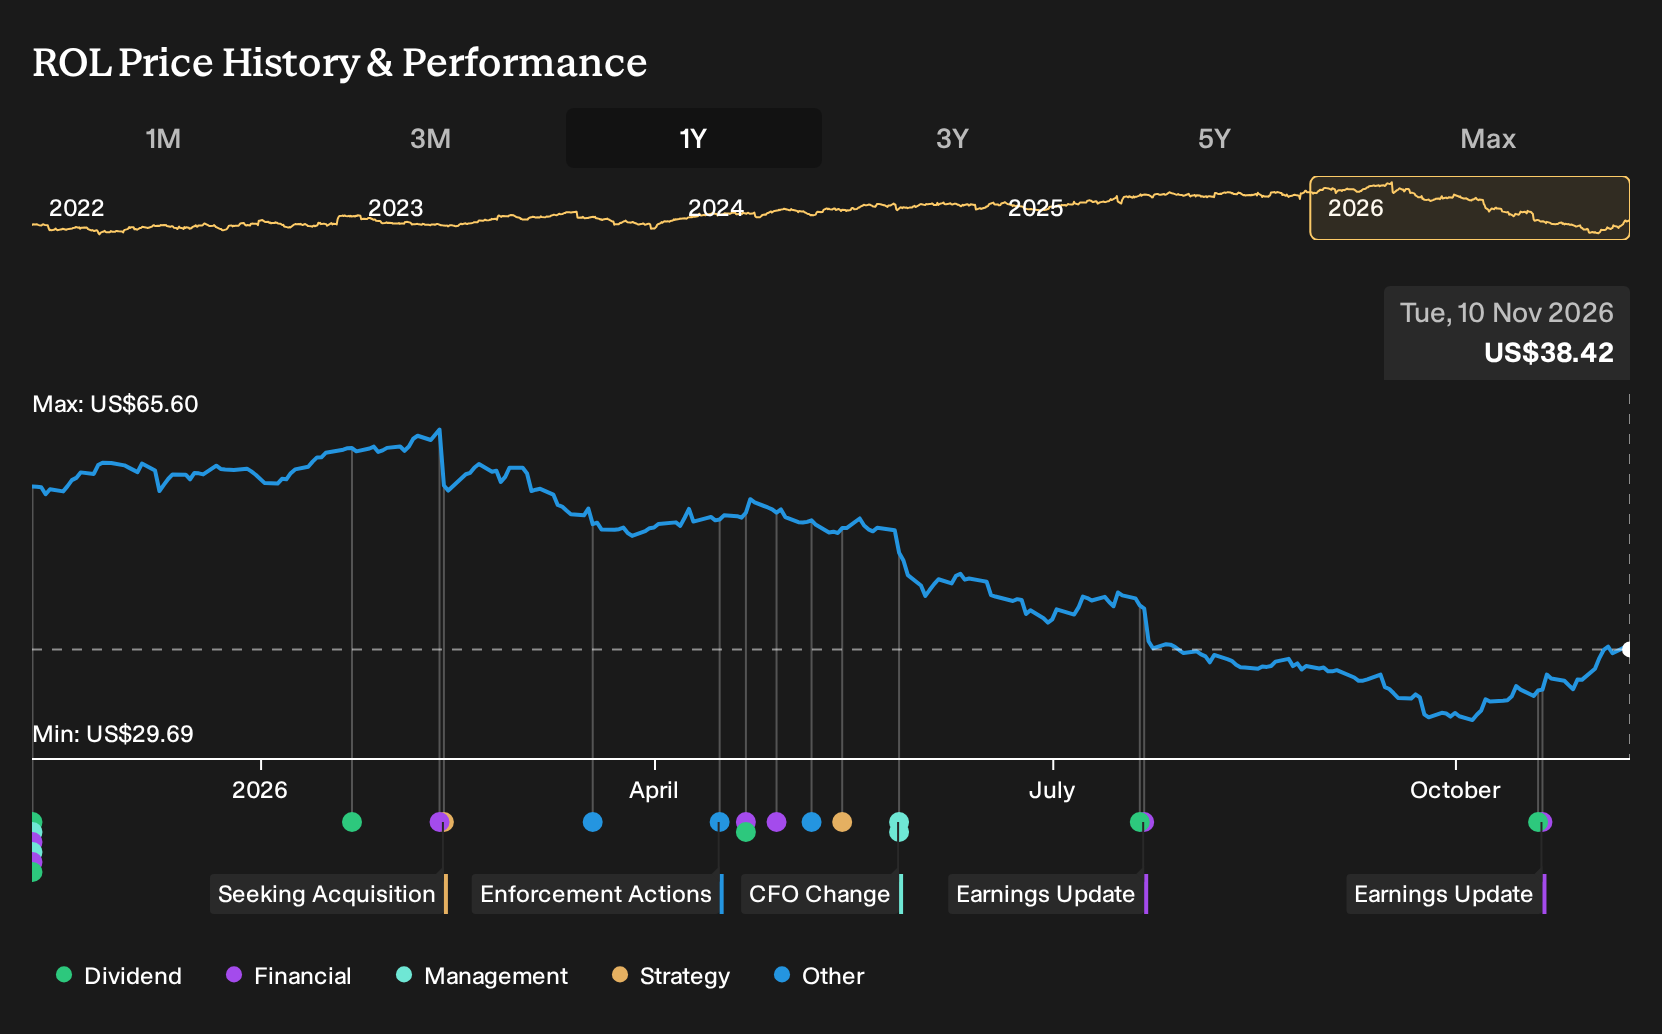
- Rollins reported third quarter 2026 results that fell short of analyst estimates on both revenue and adjusted earnings, with modest top line progress but clear operational pressure.
- Management is tackling growth challenges tied to AI-driven lead generation by testing moves such as publishing prices and offering same-day service windows, while acquisition integration remains a key execution swing factor.
- We will look at how Rollins' recurring-service investment story holds up as management tackles AI-related lead generation pressures.
Spot other companies wrestling with AI driven demand shifts and recurring revenue models by scanning our hand picked 36 high quality undervalued stocks alongside Rollins for comparison.
Rollins Investment Narrative Recap
To own Rollins, you need to believe the recurring pest control model can keep compounding even when lead generation tools change. The third quarter miss and softer earnings put the spotlight on how quickly AI driven search issues are addressed. The short term catalyst is clear: stabilise organic demand and route productivity as these new pricing and service tweaks roll through the system.
The biggest near term risk sits on the execution side. AI tools have disrupted how customers find providers, while acquisitions still need careful integration to protect margins. Esteban, a Simply Wall St Community investor who wrote the Narrative, argues that Rollins' moat and capital light model matter most over time, and this latest quarter does not fundamentally change that long view.
The most relevant recent move is management’s push to respond to AI led search shifts by publishing prices and offering same day service windows. For a pest control provider, that is about showing up more cleanly in algorithm driven comparisons and making it easier for a first time customer to choose Rollins quickly when there is an urgent problem to solve.
Execution around this change links directly to the key catalyst and risk. Faster, clearer digital conversion can support route density, which Esteban sees as central to the Rollins flywheel, while any stumble would keep pressure on earnings that already missed third quarter expectations. For you as a shareholder or potential shareholder, it comes down to confidence in management’s ability to turn these AI era experiments into steady, repeatable demand.
Esteban’s narrative arrives at a fair value of $16.20 for Rollins by modelling revenue that declines 16.7% a year yet still supports a future profit margin of 13.8%. The focus is on what that earnings power could justify for a mature, slower growing service provider.
Uncover why Rollins' fair value indicates a 58% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some bullish analysts view Rollins through a very different lens. You might focus on AI related lead risk, while they lean into forecasts that had revenue growing about 8.4% a year and earnings reaching roughly US$727.3 million by 2029. Those pre news assumptions may shift, so compare both stories before deciding what feels reasonable.
Explore 6 other Rollins fair value estimates, including one that suggests as much as 20% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rollins research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Rollins. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rollins' overall financial health at a glance.
Looking for more investment ideas beyond Rollins?
If the Rollins story has sharpened your thinking, use that momentum to widen your watchlist with a few focused stock shortlists built around different types of opportunity.
- For investors who want income that can potentially smooth out market swings, start with a curated set of higher yielding payers through the 5 dividend fortresses.
- If capital preservation and steadier balance sheets matter most to you right now, filter for sturdier businesses using the list of solid balance sheet and fundamentals (24 results).
- When you are hunting for underfollowed opportunities with room to grow, cast a wider net and scan our 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com