
Diamondback Energy (FANG) Stock Could Be Fully Priced Following Its 99% Run
Diamondback Energy has nearly doubled shareholders' money over the past five years, yet the stock has recently pulled back and the latest corporate moves keep bringing the same question back to the surface. Is the current share price at around US$178 being fairly supported by the earnings power of the business or has the valuation run ahead of itself?
- A roughly 98.9% return over five years puts a lot of expectations into Diamondback Energy. This makes it important to ask whether the profit stream underlying the stock now justifies that kind of share price journey.
- Recent updates on dividends, share buybacks and infrastructure investments suggest management is leaning on cash generation and capital discipline. These factors can shape how reliably earnings might support the current valuation over time.
- Your read on Diamondback Energy is one view; the desks covering it have another. See what analysts think Diamondback Energy's shares could be worth.
For investors, the debate is whether Diamondback Energy's recent share price, after a strong multi year run and fresh corporate developments, is adequately explained by the earnings the company is producing today.
To pressure test whether Diamondback Energy's earnings really justify a US$178 share price, it can help to compare it with a wider group of 36 high quality undervalued stocks.
Does Diamondback Energy Look Pricey on Earnings?
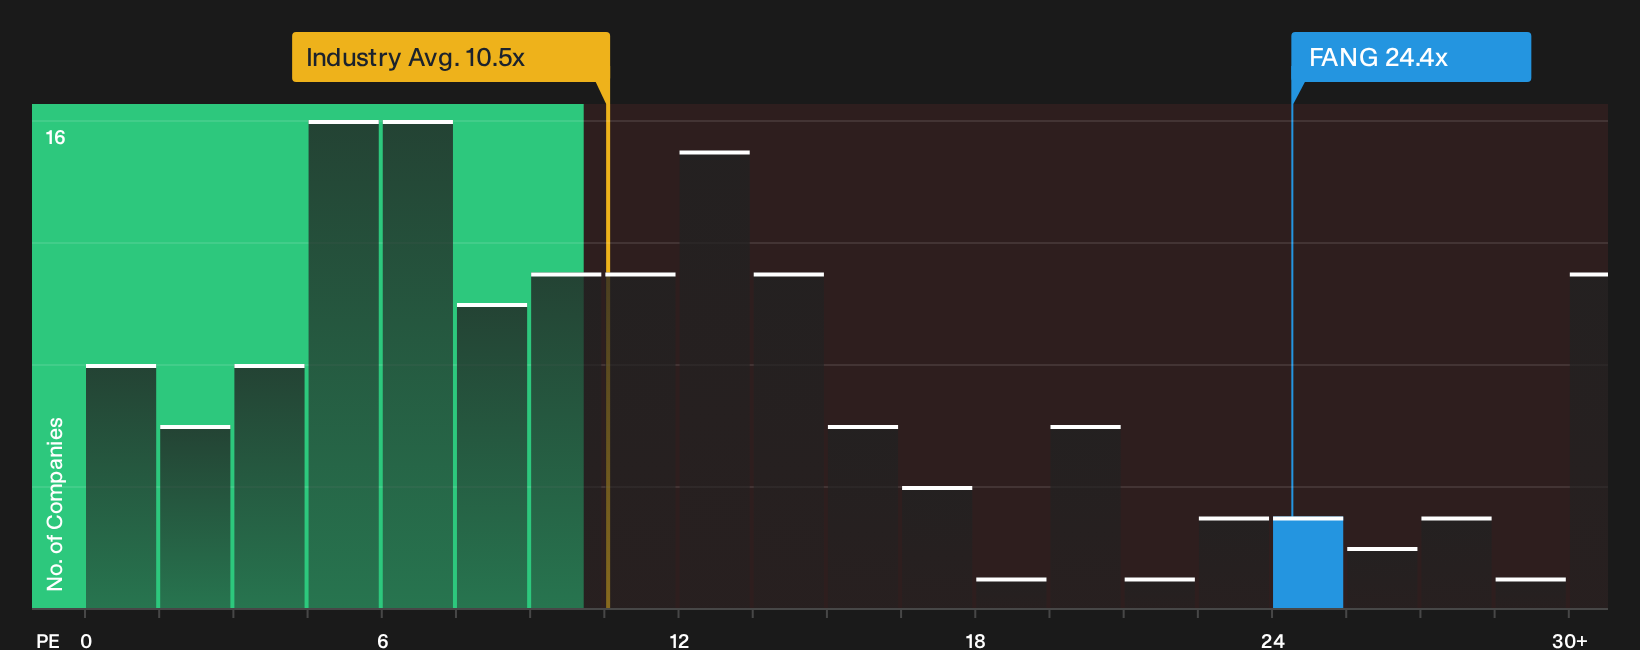
The P/E ratio suits Diamondback Energy because earnings remain a key anchor for how investors frame value in oil and gas producers. On this measure, the stock trades on roughly 24.4x earnings, compared with an industry average near 10.5x and a peer group around 10.7x. That is a sizeable step up from the broader oil and gas space, which tends to command lower P/E levels given the cyclical nature of commodity prices.
The fair multiple implied by Simply Wall St’s model, which blends Diamondback Energy’s growth profile, margins, size and risk into a single benchmark, also sits below the current 24.4x. Because the business has just highlighted stronger Q3 2026 results, a higher dividend and fresh infrastructure deals, the market appears willing to pay a premium P/E for that earnings profile despite cheaper peers across the sector. Explore the numbers behind Diamondback Energy's P/E valuation.
The Diamondback Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Diamondback Energy leaves off by spelling out which future paths for growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than the current price. They sit on the Community page so you can track how each fair value argument behaves over time as a real, testable thesis about the business rather than a single snapshot.
One of the top narratives on Diamondback Energy: 36% undervalued
This Narrative is the bullish analyst Narrative on Simply Wall St, built on the most optimistic analyst price target and forecasts, not one person's view.
"The numbers imply the share price treats Diamondback as only modestly undervalued relative to its cost structure and inventory depth..."
Discover why this Narrative puts Diamondback Energy at 36% undervalued.
Diamondback Energy’s share price is only one piece of the decision
Before you lean too hard on the P/E and valuation work, it is worth knowing that Simply Wall St’s broader checks have flagged specific concerns that investors often weigh carefully. Take a closer look at 4 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com