
MEITEC Group Holdings (TSE:9744) Cuts Interim Dividend, Is It Still Undervalued?
MEITEC Group Holdings (TSE:9744) has come into focus after reporting lower half year net income and earnings per share, alongside a trimmed interim dividend. These developments have raised fresh questions about the stock’s current risk reward profile.
At a share price of ¥3,266, MEITEC Group Holdings has seen short term momentum soften, with the 90 day share price return declining 2.59% and the year to date move down 7.84%. This comes even though the 1 year total shareholder return of 5.95% sits against a much stronger 40.50% three year and 75.97% five year total shareholder return profile, which still reflects investors being rewarded over a longer holding period as sentiment now reacts to weaker half year earnings, trimmed guidance and the lower interim dividend.
Compare how MEITEC Group Holdings stacks up on quality and valuation by lining it up against a curated 21 high quality undervalued stocks that share solid fundamentals and lower implied expectations.
So the question now is simple. After MEITEC Group Holdings softened on weaker earnings and a lower interim dividend, do you commit at this level, or wait for valuation to offer a clearer margin of safety?
Preferred Price-to-Earnings of 21.4x: Is it justified?
MEITEC Group Holdings trades on a P/E of 21.4x, which is higher than both its Professional Services industry reference point and peer group, even though the share price of ¥3,266 screens as 28.8% below an internal future cash flow estimate of ¥4,589.71.
The P/E multiple captures what investors are currently willing to pay for each unit of earnings. For a people heavy engineering solutions group like MEITEC Group Holdings it often reflects factors such as contract visibility, utilisation rates, and the resilience of client demand for outsourced engineers.
With this stock valued at 21.4x earnings versus a Professional Services industry average of 12.4x and a peer average of 20.5x, the market is assigning a clear premium. That premium also runs above an estimated fair P/E of 20x, which is a level the valuation analysis suggests the market could eventually gravitate toward if expectations cool.
Explore the SWS fair ratio for MEITEC Group Holdings.
Result: Price-to-Earnings of 21.4x (OVERVALUED)
Still, the risk is clear: if contract demand softens or utilisation weakens, the premium P/E on MEITEC Group Holdings could compress faster than earnings adjust.
Find out about the key risks to this MEITEC Group Holdings narrative.
Another View on MEITEC Group Holdings: Cash Flow Says Undervalued
The earnings multiple paints MEITEC Group Holdings as expensive, yet our DCF model points the other way. With the share price at ¥3,266 and a future cash flow estimate of ¥4,589.71, the framework suggests the stock trades about 28.8% below that implied value. Which lens do you trust more when earnings momentum is soft but cash generation appears stronger?
For a closer look at how this cash flow view is built, and where the key assumptions sit, Look into how the SWS DCF model arrives at its fair value.
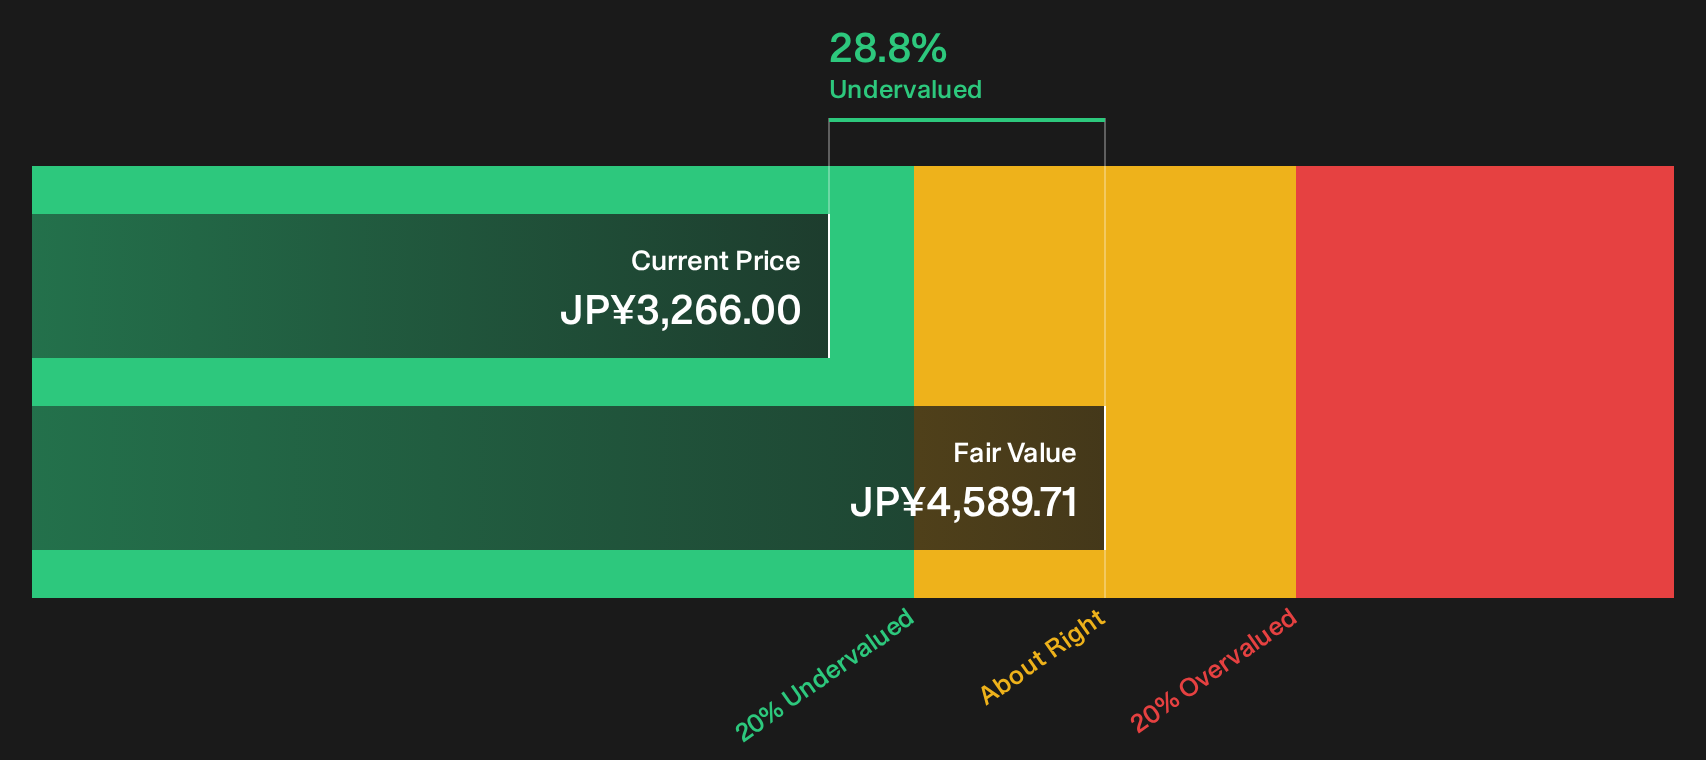
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MEITEC Group Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 21 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on MEITEC Group Holdings is clearly mixed, with rewards on one side and flagged risks on the other, so move fast and test the numbers for yourself. To see both angles in one place and decide where you stand, review the 2 key rewards and 1 important warning sign
Looking for more ideas beyond MEITEC Group Holdings?
Do not stop your research with one stock. Put the same disciplined thinking to work across a wider watchlist and let data surfaced by powerful screeners do the heavy lifting.
- Target dependable cash returns by focusing on income opportunities highlighted through the 27 dividend fortresses.
- Hunt for quality at a discount by filtering companies that combine valuation support and fundamentals using the 73 high quality undiscovered gems.
- Prioritise resilience by concentrating on businesses flagged in the 19 resilient stocks with low risk scores that score well on financial strength and risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com