
How Investors May Respond To Comfort Systems USA Stock As Earnings Estimates Rise
- Comfort Systems USA has recently seen analysts lift earnings estimates and highlight strong cash flow trends, pointing to solid project execution and healthy fundamentals across its mechanical and electrical operations.
- An interesting angle is how these higher earnings expectations intersect with Comfort Systems USA's technology heavy backlog and modular build out, which together could reshape the balance between large projects and recurring service work.
- We will now look at how Comfort Systems USA's investment narrative could be affected by these upgraded earnings expectations and analyst confidence.
Scan how upgraded earnings expectations on Comfort Systems USA compare with other construction and engineering plays by checking the hand picked list of solid balance sheet and fundamentals (24 results) in this space.
Comfort Systems USA Investment Narrative Recap
To own Comfort Systems USA, you need to be comfortable with a construction specialist that is tightly linked to AI data centers, semiconductor facilities and modular builds. The analyst consensus Narrative on Simply Wall St focuses on a record US$14.1b backlog, strong recent cash generation and high returns on equity. The short term swing factor is how smoothly that project queue turns into revenue while keeping gross margins in the mid 20% range.
The main operational risk is concentration. Technology linked work made up 58% of revenue in the first half of 2026 and industrial customers 75%. Any pause in these build programs or slower approvals could weaken backlog conversion just as expectations from upgraded earnings estimates have risen, even if underlying execution remains disciplined.
The most relevant piece of recent commentary is the focus on Comfort Systems USA being treated as a growth story, with earnings forecast to grow about 21% per year and revenue expected to rise around 18.4% annually. Those projections rely heavily on demand for complex technology and industrial projects that support higher gross margins and modular capacity expansion backed by customers.
Viewed against that backdrop, stronger earnings estimates and positive revisions mainly serve as a confidence check on the existing thesis rather than a new driver. The operational catalysts still sit in the same areas: modular construction ramp, conversion of the US$14.1b backlog and the eventual shift of data center projects into higher margin service work, while concentration in AI related construction and recent insider selling remain the pressure points to watch.
Comfort Systems USA's narrative projects US$23.3b revenue and US$3.4b earnings by 2029. This implies 23.0% yearly revenue growth and roughly a 2.1b earnings increase from US$1.6b today.
Uncover why Comfort Systems USA's fair value indicates a 65% potential upside to its current price, which could narrow quickly.
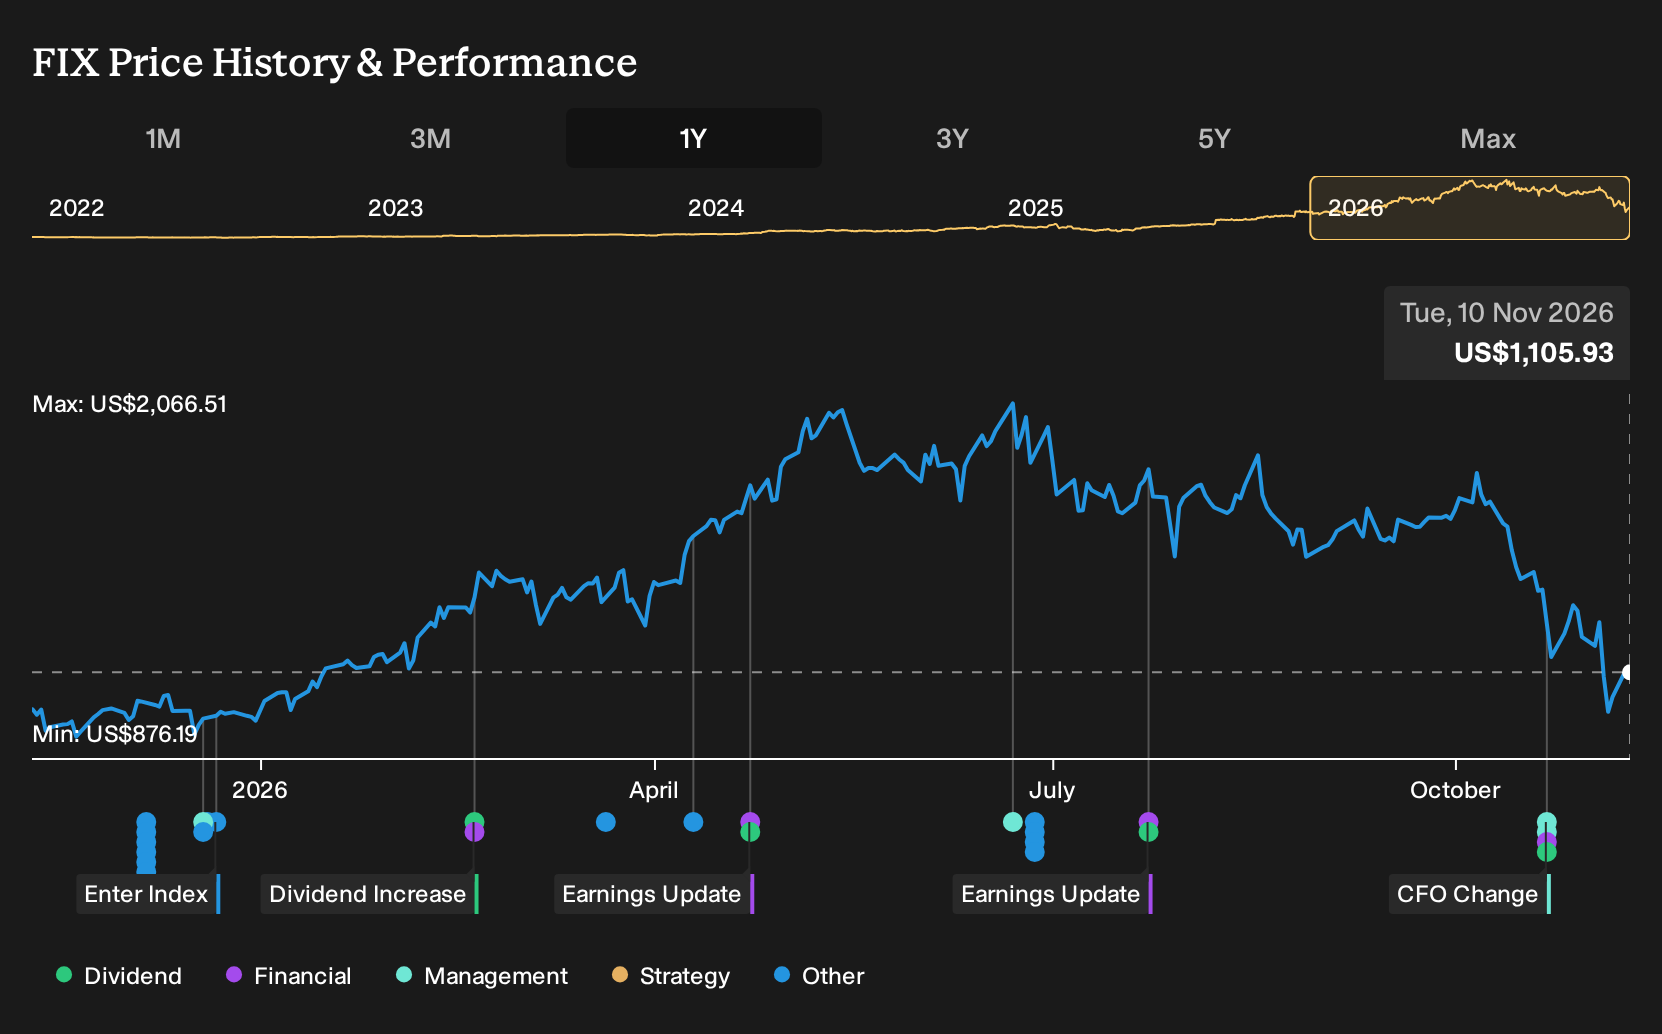
Exploring Other Perspectives
One alternate view focuses on the risk that Comfort Systems USA’s high capital spending on modular capacity becomes a drag if data center demand cools. The most cautious analysts were only pencilling in about US$20.9b of revenue and US$2.8b of earnings for 2029 before this upgrade news. That is a much more pessimistic path. Use that gap as a reminder that smart people can disagree widely, and treat this latest wave of strong earnings revisions as a reason to compare several narratives rather than settle on a single story.
Explore 5 other Comfort Systems USA fair value estimates, including one that suggests it could be worth just $1,255.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Comfort Systems USA research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Comfort Systems USA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Comfort Systems USA's overall financial health at a glance.
Looking for more Comfort Systems USA investment ideas?
If you want to stress test what you think about Comfort Systems USA against a broader opportunity set, it helps to line it up next to other businesses with different balance sheets, cash profiles and risk levels. The Simply Wall St Screener can surface a range of candidates that fit the kind of traits you care about most, whether that is resilience, income or potential mispricing.
- For investors who care most about financial strength, compare Comfort Systems USA with a list of solid balance sheet and fundamentals (24 results) to see which businesses pair sturdy balance sheets with solid fundamentals.
- If your priority is finding mispriced quality, set Comfort Systems USA alongside a 36 high quality undervalued stocks that may warrant a closer look based on current fundamentals.
- For a different angle focused on stability, weigh Comfort Systems USA against a 30 resilient stocks with low risk scores that screens for companies with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com