
Is Epiroc (OM:EPI A) Undervalued After Stronger Third Quarter Results?
Epiroc (OM:EPI A) just posted its third quarter and nine month 2026 results, with sales and net income figures higher than the previous year. This has put fresh attention on the stock’s recent pullback.
Despite the stronger nine month figures, the share price has slipped around 6.7% over the past 30 days and about 2.7% over the last quarter, while the year to date share price return of roughly 17.8% and 1 year total shareholder return of 25.2% suggest longer term momentum for Epiroc is still intact.
Scan for other industrials that show similar earnings strength to Epiroc, along with recent share price pullbacks, by checking our hand picked list of solid balance sheet and fundamentals (194 results)
Epiroc shares now trade at a discount to the average analyst price target, while an intrinsic value estimate sits close to the current price. Is the market applying healthy caution, or leaving a reasonable gap to fair value?
Most Popular Narrative: 13% Undervalued
The analyst consensus Narrative on Simply Wall St places Epiroc’s fair value at about SEK283.90, compared with the last close at SEK247.60. This suggests upside in that framework and puts more weight on long term contract visibility and aftermarket depth than on short term share price swings.
The main thing that has to go right is that Epiroc keeps turning its large and aging installed base into recurring aftermarket, automation and electrification revenue, while managing cyclical softness in Tools & Attachments and infrastructure exposure.
The current valuation, together with this narrative’s fairly valued and bullish stance, implies the share price already reflects substantial long-term growth and high-margin cash generation from mining equipment, services and technology, leaving limited room for disappointment if the cycle or execution weakens.
See why 12 investors see Epiroc as 13% undervalued.
Result: Fair Value of SEK283.90 (UNDERVALUED)
Still, the narrative could be shaken if prolonged weakness in construction keeps Tools & Attachments subdued or if higher inventories keep more cash tied up in Epiroc’s operations.
Find out about the key risks to this Epiroc narrative.
Another View: Epiroc looks pricey on earnings
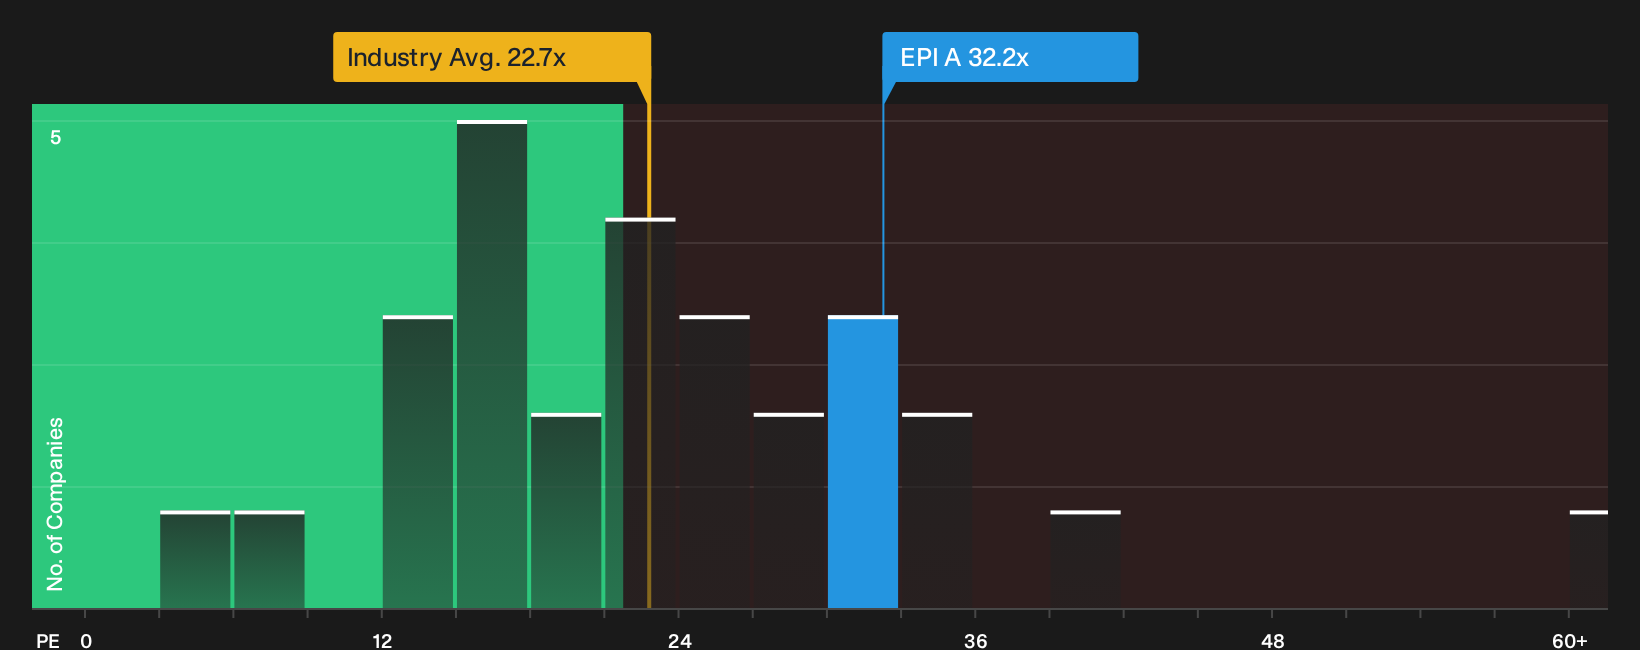
The SWS fair value narrative points to Epiroc trading roughly 13% below its estimate of SEK283.90. On straight earnings, the picture is much tougher. The current P/E of 32.2x is higher than the Swedish Machinery industry at 22.7x, above peers at 23.3x, and above the fair ratio of 28.7x, which flags valuation risk if sentiment cools.
For investors comparing these signals, the question is simple. Is Epiroc’s quality and growth profile enough to keep justifying this premium, or could the share price drift back toward that lower fair ratio level if expectations soften, ascribed by See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed signals on Epiroc leave you unsure, that is healthy. Act while the data is fresh and evaluate the potential upside drivers for yourself with 2 key rewards
Looking for more investment ideas beyond Epiroc?
If Epiroc has sharpened your focus on quality opportunities, keep that momentum going by lining up a few more candidates while this earnings season is still fresh.
- Target potential mispricings by scanning a curated set of resilient companies that combine quality fundamentals with appealing valuations through the 200 high quality undervalued stocks.
- Strengthen your income stream by reviewing a shortlist of companies offering higher yields and consistent payouts using the 216 dividend fortresses.
- Reduce surprise risk by focusing on businesses with robust finances and dependable balance sheets sourced from the list of solid balance sheet and fundamentals (194 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com