
How Investors May Respond To Gulfport Energy (GPOR) Lower Earnings And New Guidance
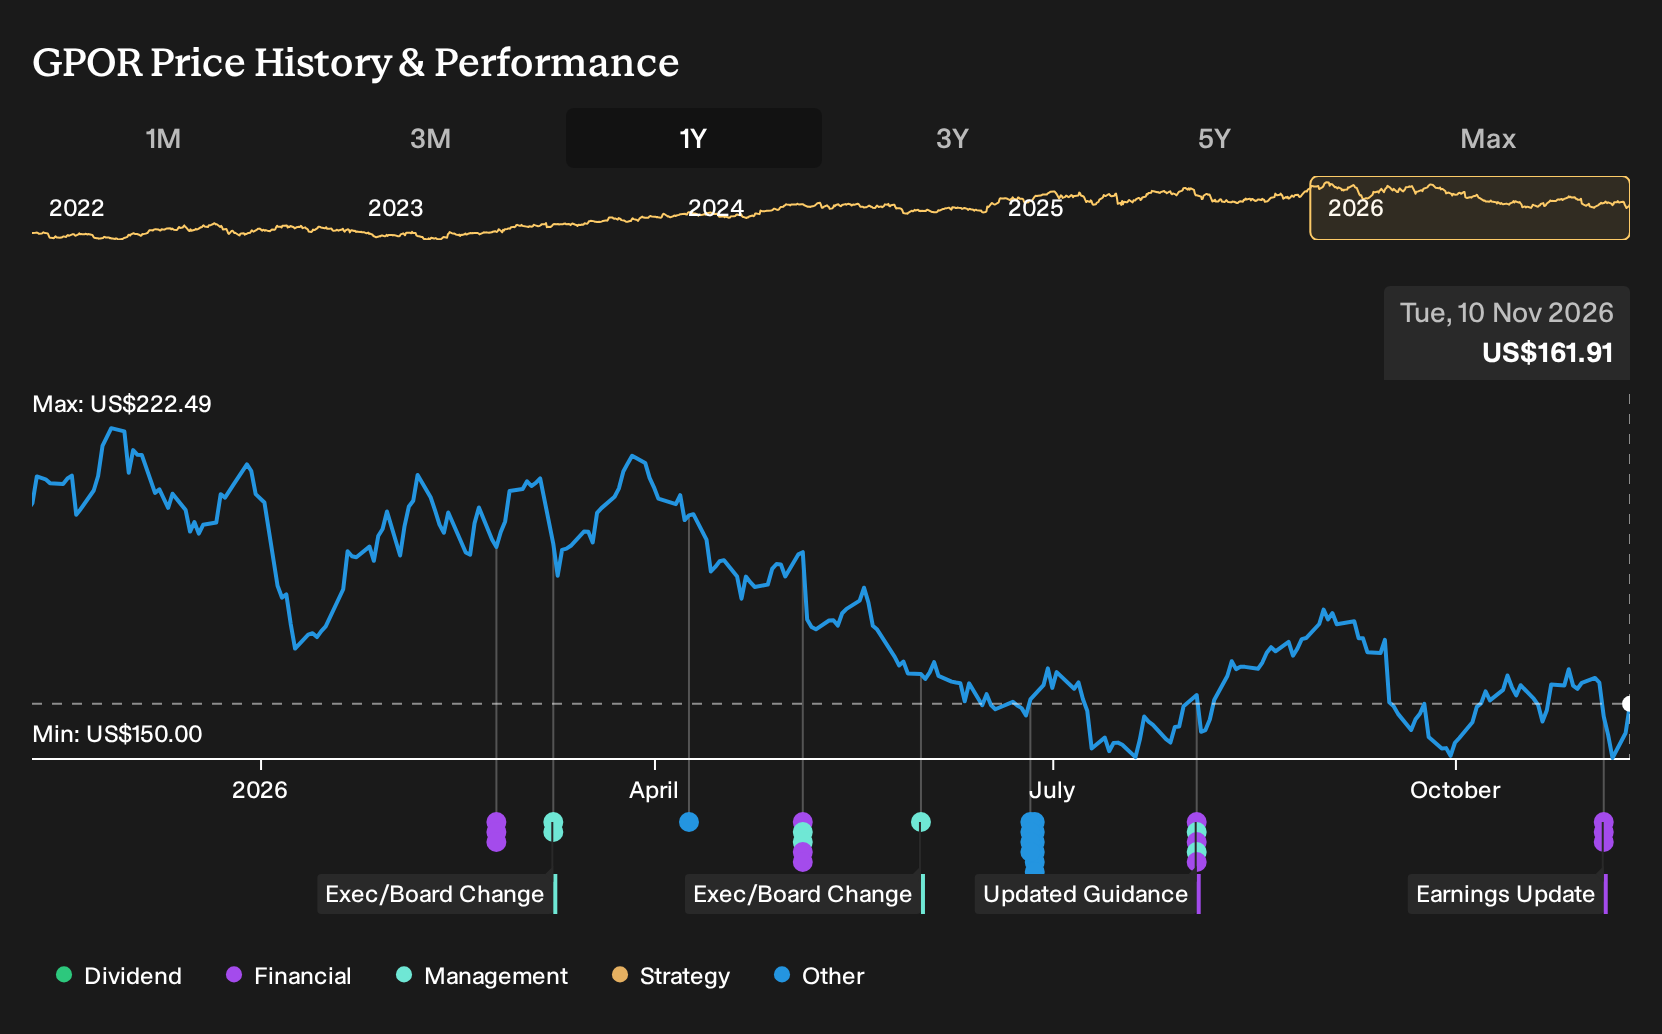
- Gulfport Energy reported third quarter 2026 revenue of US$362.47 million and net income of US$96.4 million, both below the same period a year earlier, along with updated production figures that showed lower natural gas and oil volumes but higher NGL output.
- Despite softer quarterly revenue and profit, Gulfport Energy’s basic EPS from continuing operations rose to US$5.47, supported by a higher year to date net income of US$349.32 million and a liquids heavy production mix that now includes delivered net liquids production of 23.5 MBbl per day.
- Attention now turns to how Gulfport Energy’s softer quarterly revenue, together with its new 2026 production guidance, could reshape the investment narrative.
Scan how Gulfport Energy’s liquids-heavy production story compares with other potential opportunities by reviewing a curated set of 36 high quality undervalued stocks that share solid cash generation and balance sheets.
Gulfport Energy Investment Narrative Recap
For Gulfport Energy, the core belief is that its Appalachia focused portfolio and liquids shift can support resilient cash generation even when gas volumes soften. The third quarter update fits that story because revenue and net income were lower year on year, yet earnings per share and year to date profit still held up, helped by a richer liquids mix.
The key near term swing factor remains how effectively Gulfport Energy turns its higher delivered net liquids production into steady cash flow while managing drilling and transport costs. The biggest risk flagged in the analyst consensus Narrative on Simply Wall St, weaker natural gas fundamentals or pricing, is not directly changed by this quarter, so the impact looks modest for now.
The new 2026 production guidance is the announcement that ties closest to this earnings release. Management outlined expected average daily gas equivalent volumes of 1.030 to 1.055 Bcfe per day and liquids of 18.0 MBbl to 21.0 MBbl per day, which gives a clearer frame for what the current capital program is aiming to deliver operationally.
That range matters because the catalysts in the analyst consensus Narrative on Simply Wall St lean heavily on efficient development of a large Appalachia inventory and ongoing liquids growth. If actual output lands meaningfully away from those ranges, it could either support that thesis or stress it, especially given the existing concerns about gas pricing, discretionary Utica spending and the need to keep returns on new acreage competitive.
Gulfport Energy’s analyst narrative points to forecast revenue of US$1.7b and expected earnings of US$531.7 million by 2029, based on an assumed 7.9% yearly increase in sales and an earnings rise of about US$44.6 million from current earnings of US$487.1 million.
Uncover why Gulfport Energy's fair value points to a potential 33% upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Gulfport Energy from the Simply Wall St Community span roughly US$215 to US$751, across just 2 retail investor views. This shows how far opinions can stretch. Set that against risks around gas pricing, Utica spending and production delivery, and you get plenty of reasons to compare several contrasting viewpoints before deciding your own stance.
Explore another Gulfport Energy fair value estimate, including one that suggests potential upside of up to 364% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Gulfport Energy research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Gulfport Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Gulfport Energy's overall financial health at a glance.
Looking For More Gulfport Energy Sized Ideas?
If Gulfport Energy has sharpened your thinking about risk, cash flow and balance sheets, use that same lens across the wider market with the Simply Wall St Screener. You can line up different sectors, filter for the traits that matter to you, and see which other businesses fit your preferred profile.
- Target resilient balance sheets and steady fundamentals by reviewing a list of solid balance sheet and fundamentals (24 results) that already filters for financial strength.
- Focus on quality at a reasonable price by scanning a curated pool of 20 high quality undiscovered gems that pair fundamental support with underfollowed stories.
- Dial down volatility in your watchlist by starting with a pre filtered universe of 30 resilient stocks with low risk scores that aim to keep risk scores in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com