
Why Worley (ASX:WOR) Is Back In The Spotlight
Fresh commentary on the global push into decarbonisation and nuclear power has put Worley (ASX:WOR) back in focus, as its expanding sales pipeline ties directly to energy transition spending.
Worley’s recent share price tells a mixed story, with a 1-day share price return of 1.89% and a 1-month share price return of 8.37%. However, the year to date share price return is down 18.49% and the 1-year total shareholder return has declined 23.68%, suggesting that renewed interest around the decarbonisation and nuclear opportunity is lifting momentum from a weaker base.
Scan beyond Worley and assess how other energy transition contractors are priced by reviewing our hand-picked 41 power grid technology and infrastructure stocks as you think about where capital could move next.
So after a sharp short term bounce but a tougher 12 month stretch, does Worley still offer enough upside in the current price to compensate for the risks that come with its energy transition exposure?
Most Popular Narrative: 12% Undervalued
On the analyst consensus Narrative on Simply Wall St, Worley screens as undervalued, with a fair value of A$11.67 against the last close at A$10.23. This puts the current price at a discount while analysts build their case around backlog, earnings power and risk.
The accelerating global push for decarbonisation and energy transition is expanding Worley’s addressable market. The current factored sales pipeline of future work is 24% higher year-on-year, with more than $10b of recent wins in areas such as LNG, power and energy transition materials, which can support future revenue and backlog growth.
Persistent high levels of infrastructure investment from both public and private sectors seeking greater resilience and sustainability are reflected in Worley’s FY26 bookings of $15.5b and new awards across gas infrastructure, pumped storage, nuclear and low carbon power. These can underpin future topline growth and earnings stability.
See why 37 investors see Worley as 12% undervalued.
Result: Fair Value of A$11.67 (UNDERVALUED)
Still, delays to project awards linked to Middle East conflict and ongoing chemical sector softness in Europe could quickly challenge the bullish Worley narrative.
Find out about the key risks to this Worley narrative.
Another View On Worley’s Valuation
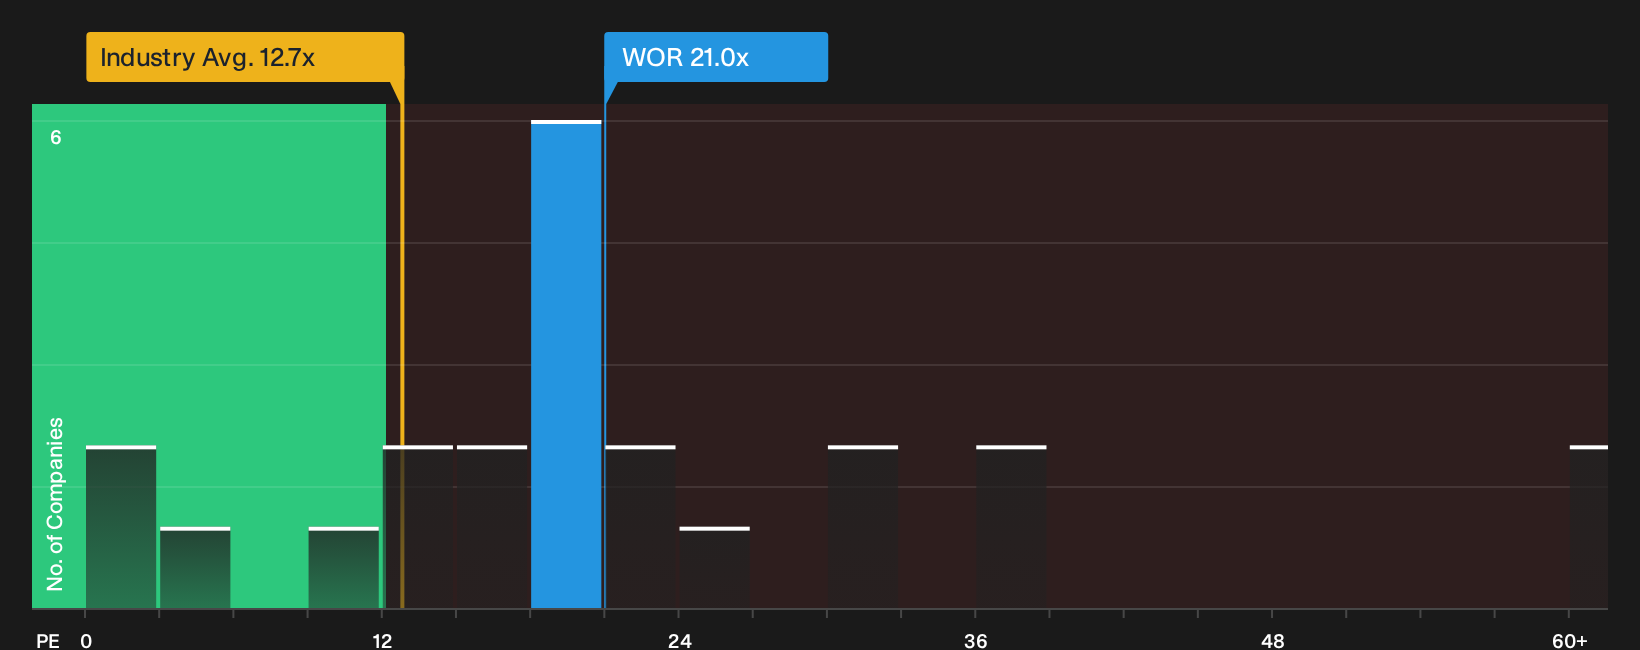
The analyst narrative sees Worley as undervalued against a fair value of A$11.67, yet the market is already paying a P/E of 21x for the shares compared with 20.1x for peers and 12.7x for the broader construction group. The Simply Wall St fair ratio of 23.4x points to some potential room above today’s earnings multiple, but it also raises a simple question for investors: Is the extra price you pay for Worley’s story enough, or already more than enough, for the risk you are taking on earnings delivery?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Worley’s valuation story are clear. Move quickly, pull up the numbers for yourself, and weigh both the upside and the risk using 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Worley?
If Worley has your attention, do not stop there. The real edge often comes from lining it up against other high quality opportunities side by side.
- Pinpoint potential bargains early by scanning our 2 high quality undervalued stocks before the crowd catches on.
- Build a portfolio that can weather shocks by focusing on companies in the 6 resilient stocks with low risk scores.
- Target rock solid balance sheets and steady fundamentals using the list of solid balance sheet and fundamentals (12 results) while others chase short term noise.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com