
Did Strong Earnings Just Shift SBI Holdings Stock Investment Narrative?
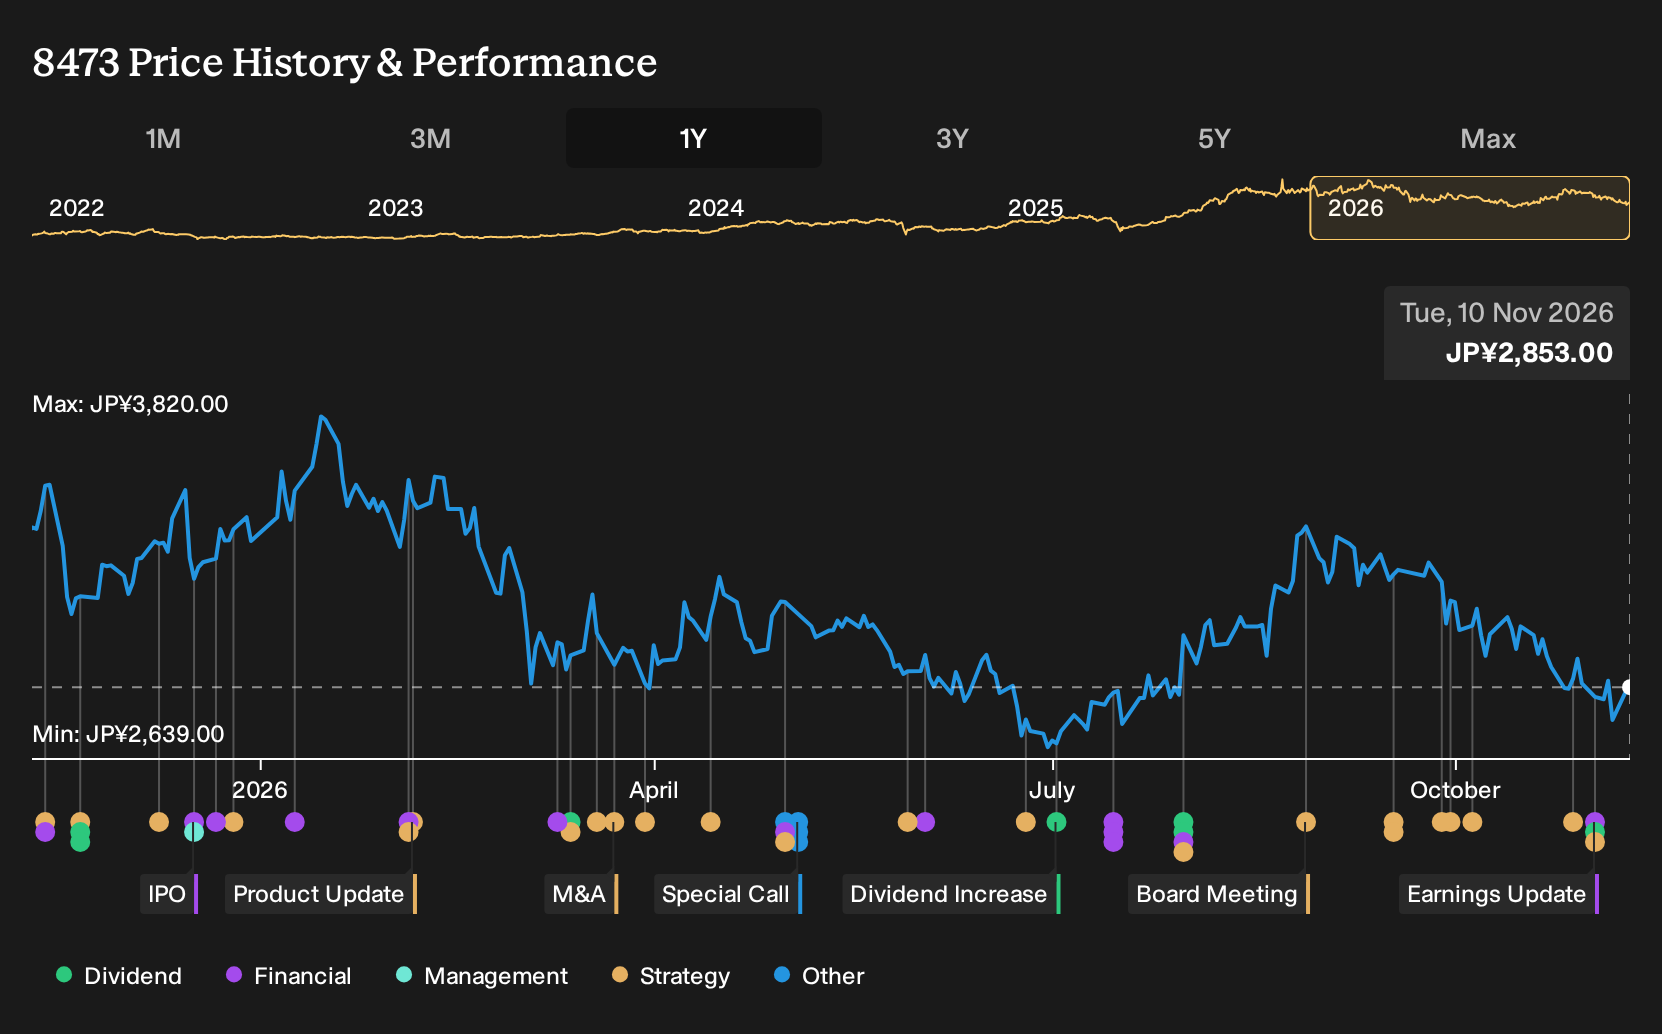
- SBI Holdings reported half year sales of ¥1,057,515 million and net income of ¥230,572 million, with higher basic and diluted EPS compared with a year earlier, alongside an interim dividend of ¥30 per share recorded on September 30, 2026.
- The group is pairing this earnings update with a planned annual dividend uplift and a planned joint venture with CRB Group targeting tokenized products, cross border payments and AI agent driven commerce in Japan and the wider Asia Pacific region.
- We will now look at how SBI Holdings' half year profits could reshape the existing investment narrative around digital finance.
Scan 21 cryptocurrency and blockchain stocks that, like SBI Holdings, are leaning into tokenized assets, cross border payments and AI driven financial infrastructure across Japan and the wider Asia Pacific region.
SBI Holdings Investment Narrative Recap
To own SBI Holdings, you need to believe the group can keep turning a broad financial platform into steady earnings while managing crypto and overseas expansion risk. The recent half year results, with ¥1,057,515 million in sales and ¥230,572 million in net income, suggest the business is currently generating solid profit that can fund this push.
The analyst consensus Narrative on Simply Wall St still flags the biggest near term swing factor as execution in digital assets and overseas operations, where losses or deal setbacks could unsettle earnings. The latest figures do not remove those concerns, although higher earnings and the interim dividend give management a bit more room to absorb volatility.
The clearest operational signal in this news flow is the dividend update alongside the earnings release. An interim payout of ¥30 per share for the September half, combined with an expected full year total of ¥110 per share for FY2027, matters for any thesis that sees SBI Holdings as a cash generative financial platform, not just a high beta crypto proxy.
That payout plan also intersects directly with near term risks from crypto businesses and overseas expansion. If earnings in those areas become more volatile or if overseas acquisitions fall short, the ambition to lift annual dividends could meet the "unstable dividend track record" flag in the risk summary. Investors will likely watch whether future distributions track full year performance or start to bump into those constraints.
SBI Holdings' analyst narrative points to revenue of ¥1,710.2 billion and earnings of ¥251.7 billion by 2029, based on an assumed yearly revenue decline of 5.5% and an earnings decrease of ¥239.3 billion from current earnings of ¥491.0 billion.
Uncover how SBI Holdings' fair value indicates a 36% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
One alternate view leans hard into SBI Holdings’ AI and on chain ambitions as a catalyst rather than a risk. In that more optimistic script, the highest analysts were working off 2029 revenue expectations around ¥1,746.3 billion and earnings near ¥279.7 billion. Those estimates all pre date this earnings and dividend news, so you may want to see how they get refreshed.
Explore 2 other SBI Holdings fair value estimates, including one that suggests as much as 58% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SBI Holdings research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SBI Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SBI Holdings' overall financial health at a glance.
Looking for more investment ideas beyond SBI Holdings?
SBI Holdings may sit at the center of your research today, but your portfolio will often benefit from a broader bench of ideas. The Simply Wall St Screener can help you quickly surface other candidates that fit the type of risk, income profile, or quality tilt you want to add next.
- For investors hunting for smaller companies with meaningful upside potential, scan a curated pool of 1 elite penny stocks with strong financials that meet strict financial quality filters.
- If you want to tilt toward value backed by business strength, look through our hand picked 21 high quality undervalued stocks that combine healthy cash flows with sturdier balance sheets.
- For readers who care most about resilience before anything else, focus on a focused universe of 19 resilient stocks with low risk scores that score well on our risk checks and financial stability tests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com