
Will Earnings Beats Change American Eagle Stock Narrative
- American Eagle Outfitters recently reported expectations for quarterly earnings of $0.49 per share with a projected 7.6% year over year decline, while consensus points to a 49.3% increase in earnings for the current fiscal year and continued revenue growth.
- Investor interest has centered on American Eagle Outfitters consistently beating earnings and revenue estimates across the past four quarters, as the retailer leans on Aerie, OFFLINE and ongoing digital and store initiatives to support future sales and margins.
- We will now look at how American Eagle Outfitters' consistent earnings outperformance could influence the existing investment narrative around its brands.
American Eagle Outfitters Investment Narrative Recap
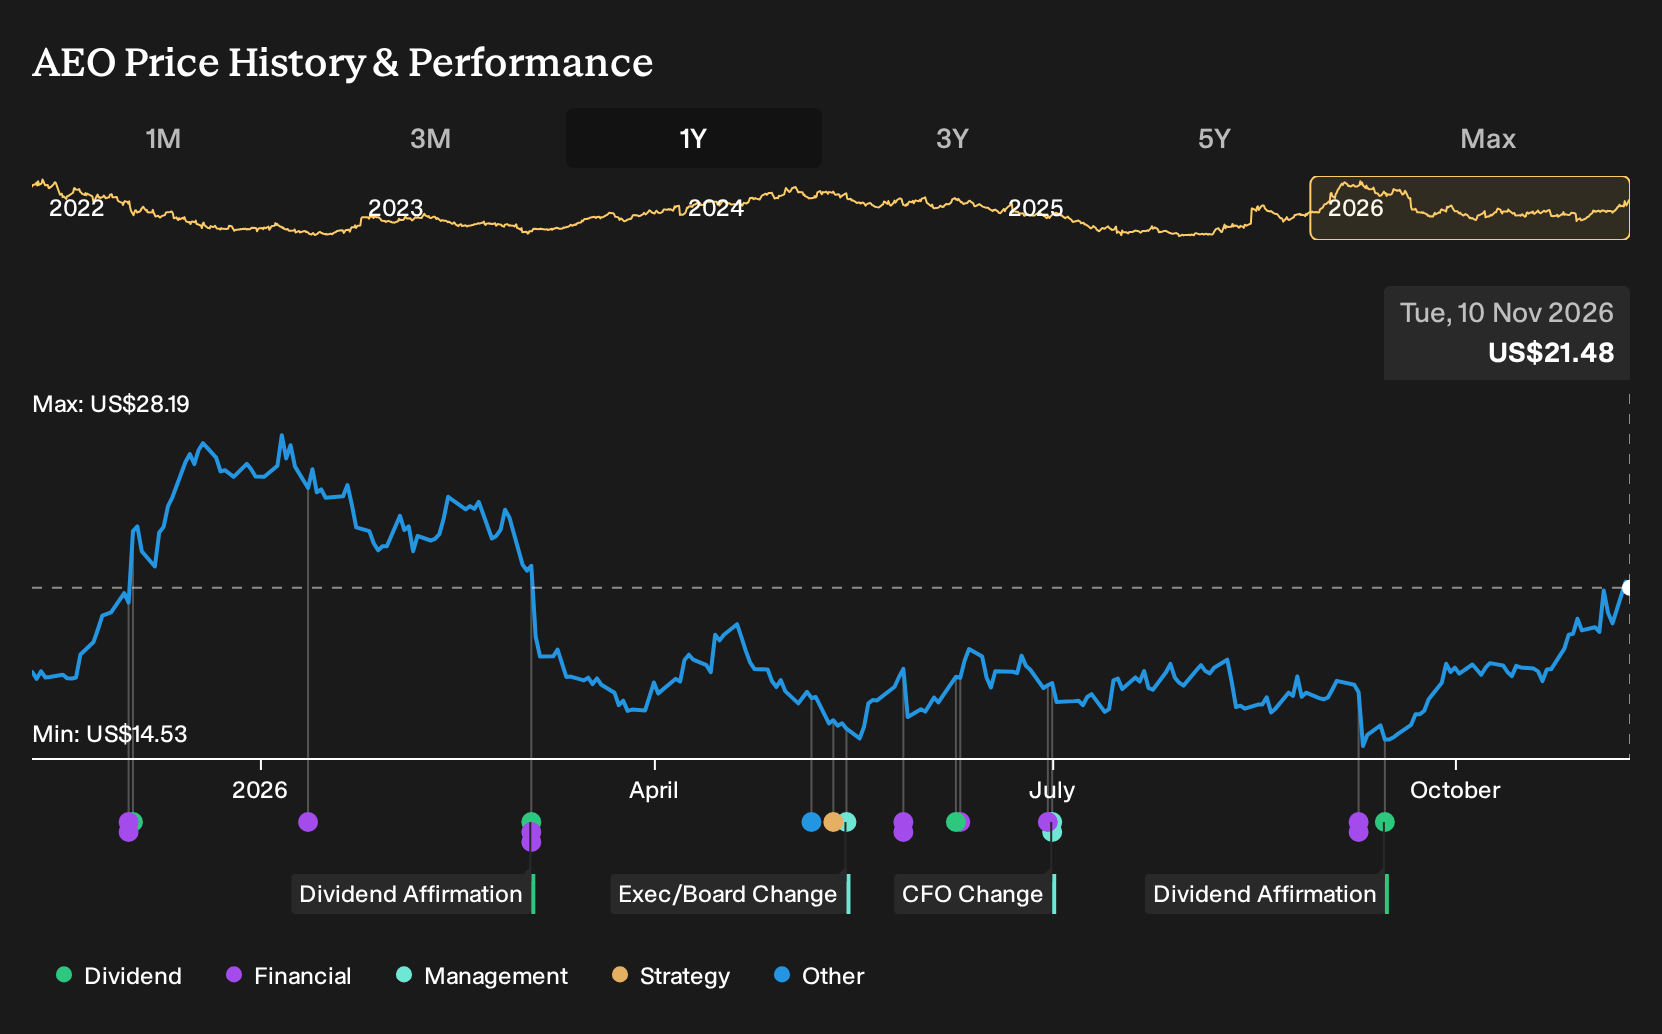
For an investor to stay with American Eagle Outfitters, the belief has to be that Aerie and OFFLINE keep bringing in customers while the core American Eagle brand works through its assortment reset. The analyst consensus narrative on Simply Wall St leans heavily on that balance. The recent 20.4% one month share gain and expected near term EPS softness do not materially change that operating equation.
The near term catalyst is straightforward: execution on inventory clean up and women’s bottoms at American Eagle, without heavy markdown pressure, needs to show up in reported margins. The biggest risk remains that ongoing softness in the flagship brand, higher inventories and further discounting eat into the earnings power created by Aerie.
The most relevant data point right now is that American Eagle Outfitters is expected to post quarterly EPS of US$0.49 with a 7.6% year over year decline, while the current fiscal year consensus still points to a 49.3% earnings increase. That mix of near term pressure and full year optimism keeps attention squarely on upcoming results as a key checkpoint.
Consistent beats on earnings and revenue over the last four quarters set a high bar for execution. If merchandise margin pressure at American Eagle, inventory imbalances or slower Aerie trends show up in the next print, the core catalysts in the analyst consensus narrative on Simply Wall St, from tariff benefits to marketing shifts and new distribution capacity, will face a tougher test in investors’ models.
Forecasts and Valuation Anchors for American Eagle Outfitters
Analysts are effectively asking you to weigh a measured growth plan for American Eagle Outfitters against tight expectations. The story hinges on whether the retailer can turn modest revenue expansion and slightly better margins into meaningfully higher profits by the next decade.
On the top line, the current framework assumes revenue grows at about 3.6% a year over the next three years. That is a steady, not aggressive, pace for an apparel retailer that is still investing in Aerie, OFFLINE and new distribution hubs. It sets a clear hurdle for how much extra customer demand and pricing power needs to come through the door.
Earnings today sit at roughly US$336.9 million, with analyst models pointing to about US$381.6 million by 2029. That implies an increase of roughly US$44.7 million in profits over the period. The forecast also bakes in a lift in profit margins from 5.9% to 6.0%, which is a small move but still requires cleaner inventory, more full price selling and fewer profit drags from markdowns at the American Eagle brand.
To reach those earnings and margin targets, consensus assumes American Eagle Outfitters continues to refine its mix of spending on advertising, digital, stores and supply chain. The shift toward more performance focused marketing and the build out of new logistics capacity both need to contribute to that slightly higher profitability, rather than just offseting rising costs.
Valuation expectations tie directly into these operating assumptions. The Simply Wall St report flags a P/E of 8.9x today that would rise to 10.4x on the 2029 earnings estimate of US$381.6 million. That multiple is still below the 16.7x P/E currently referenced for the US Specialty Retail industry. This leaves less room for compression if execution slips, but also limits how much re rating support is implied if things go right.
On revenue, the same framework points to about US$6.4b in sales by 2029 for American Eagle Outfitters. That level of turnover, combined with the earnings forecast, reflects an expectation that Aerie and OFFLINE continue to scale while the core American Eagle assortment reset stabilises margins. The pricing of the stock, with a consensus target of US$18.55 against a current share price of US$17.97 as at October 2026, signals that analysts on average see this scenario as broadly embedded in the quote.
American Eagle Outfitters' narrative projects US$6.4b revenue and US$381.6 million earnings by 2029. This requires 3.6% yearly revenue growth and about US$44.7 million earnings increase from US$336.9 million today.
Disagreement across the covering analysts adds useful context for readers. More bullish forecasts that push earnings toward US$457.4 million suggest some see more upside from margin expansion, tariff benefits or stronger Aerie trajectories. On the other side, the low end price targets around US$15 indicate concern that American Eagle brand softness, heavier markdowns or slower digital gains could make it hard to reach the central forecast path.
The gap between the high and low price targets also shows how sensitive the American Eagle Outfitters thesis is to execution on a few key levers. Inventory discipline, the pace of store openings and remodels, and how effectively management pivots marketing from awareness to conversion could all sway future earnings away from the current US$381.6 million anchor. For anyone tracking the stock, that makes upcoming quarterly reports useful scorecards against a fairly tight set of assumptions.
Uncover why American Eagle Outfitters' fair value indicates a 14% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
For the most optimistic analysts, the real swing factor is Aerie and OFFLINE turning American Eagle Outfitters into a larger lifestyle platform than current models assume. Before this latest run, some were penciling in revenue of about US$6.7b and earnings near US$457.6 million by 2029. Those projections did not factor in the recent 20.4% one month share move or the fresh US$0.49 EPS expectation, so those bullish views, and the more cautious ones, may change as new results are reported.
Explore 3 other American Eagle Outfitters fair value estimates, including one that suggests there could be as much as 38% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your American Eagle Outfitters research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for American Eagle Outfitters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Eagle Outfitters' overall financial health at a glance.
Looking For More Investment Ideas Beyond American Eagle Outfitters?
Once you have a view on American Eagle Outfitters, it can help to compare that opinion with other opportunities that match your risk tolerance, income needs and time horizon. The Simply Wall St Screener lets you cut through a large universe of stocks and focus on a short list that actually fits your brief.
- For investors who want income to be a core part of their returns, you could start with resilient payers by scanning our 5 dividend fortresses. This may help anchor a yield focused portfolio.
- If capital preservation and smoother portfolio swings matter most to you, focus on stability first by filtering for 30 resilient stocks with low risk scores that score well on our risk checks.
- When you want to widen the opportunity set beyond familiar tickers, look for underfollowed potential by searching across our 20 high quality undiscovered gems that pair quality fundamentals with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com