
How Investors Are Reacting To Alamo Group (ALG) Profit Drop
- Alamo Group reported third quarter 2026 revenue of US$403.14 million and net income of US$2.03 million, with basic earnings per share from continuing operations of US$0.17, compared with US$2.11 a year earlier.
- Over the first nine months of 2026, sales edged up to US$1,271.02 million, while net income and earnings per share trended lower, highlighting profit pressure despite a balance sheet that includes US$89.4 million more cash than debt and support from a dividend yield of 0.97%.
- We will now look at how Alamo Group’s sharply weaker quarterly earnings per share could reshape the longer term investment narrative.
Alamo Group Investment Narrative Recap
To own Alamo Group, you need to believe that its mix of Industrial Equipment and Vegetation Management can convert product launches, procurement gains and aftermarket parts growth into steadier earnings over time. The latest quarter challenges that view in the near term, with earnings per share dropping sharply even though nine month sales were slightly higher.
The most important short term catalyst remains execution on margin programs as older, higher cost inventory clears and procurement savings show up in reported results. The biggest current risk is that softer end markets in Vegetation Management and cost pressures keep profitability compressed. If that happens, the recent earnings hit could linger rather than look temporary.
The analyst consensus Narrative on Simply Wall St leans heavily on margin improvement, procurement savings and aftermarket growth as key drivers. The third quarter report, with net income of US$2.03 million compared with US$25.38 million a year earlier, highlights how sensitive that story is to any stumble in cost control or pricing.
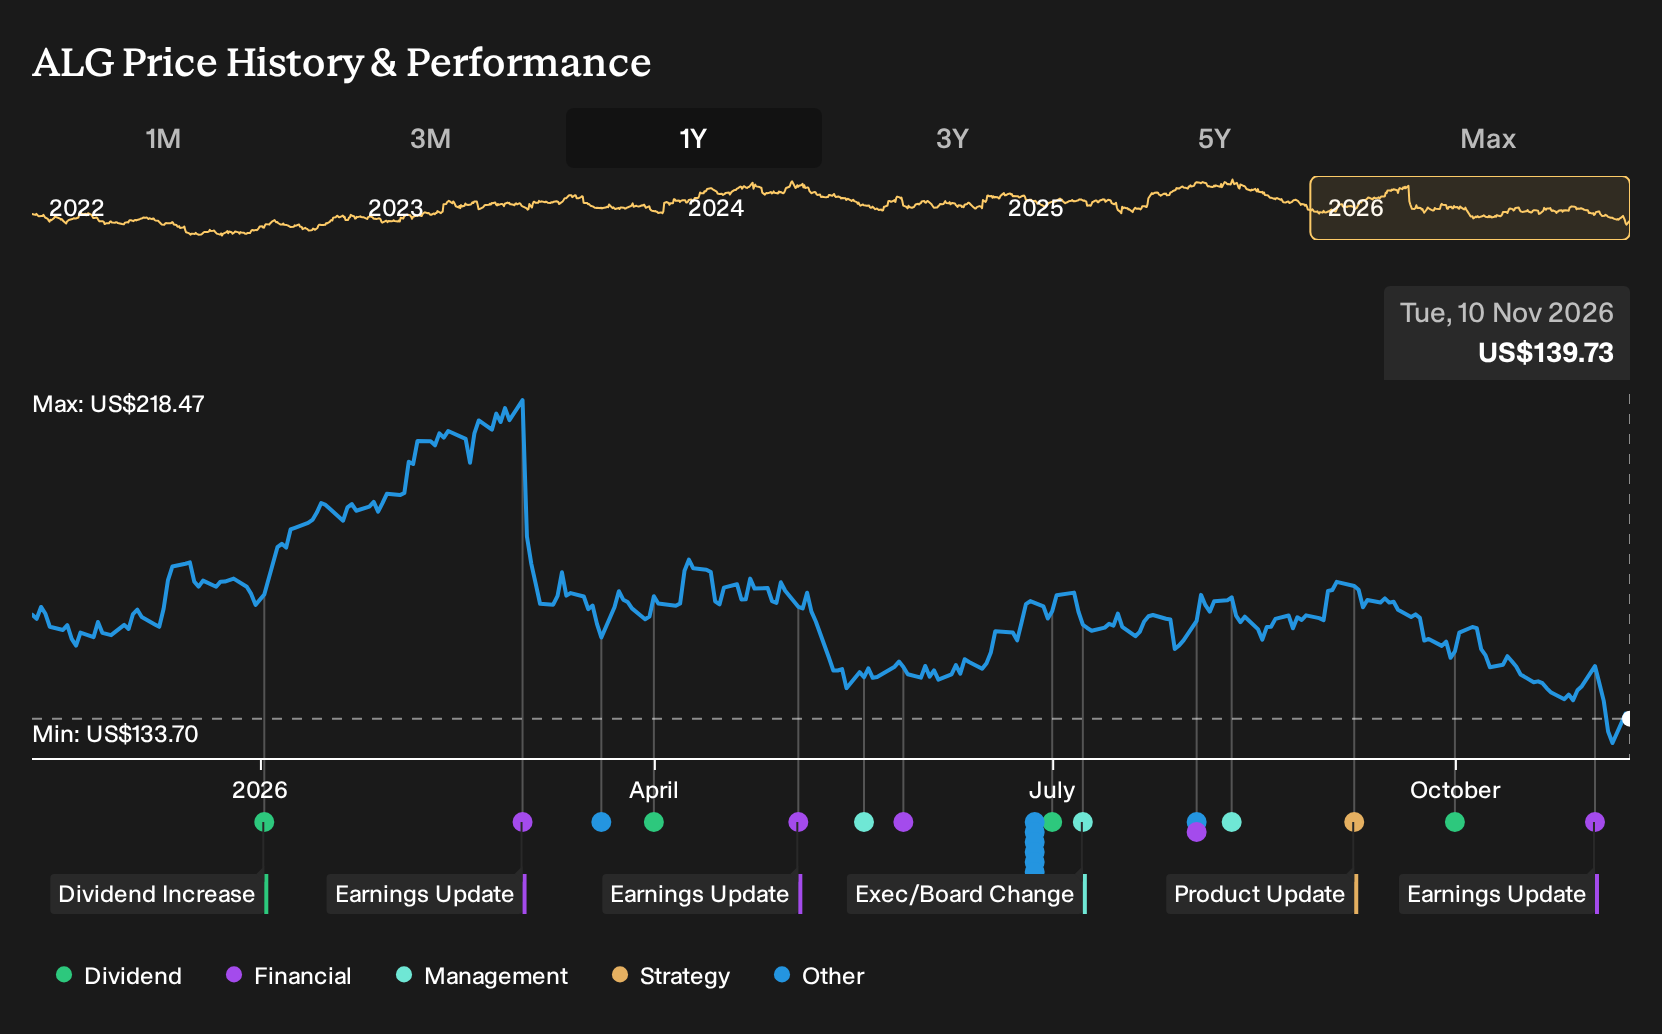
That same update keeps the focus on execution. Sales over the first nine months reached US$1,271.02 million, yet earnings per share moved lower and profit margins sat below last year. For a stock that has already underperformed the US Machinery industry over 1 and 3 years, your view on Alamo Group probably comes down to whether management can translate its margin playbook into cleaner quarterly numbers again.
Alamo Group's narrative projects US$1.9b revenue and US$178.3 million earnings by 2029. This implies 5.0% yearly revenue growth and an earnings increase of about US$100.6 million from US$77.7 million today.
Discover how Alamo Group's fair value reflects a 36% potential upside to its current price before sentiment narrows the gap.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$140 to about US$233, so retail investors there already show a wide spread on Alamo Group. Those views predate the sharp earnings drop reported on 2 November 2026. You may want to revisit them as margins, acquisitions and product launches reshape expectations.
Explore 2 other Alamo Group fair value estimates, including one that suggests the potential for as much as 66% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alamo Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Alamo Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alamo Group's overall financial health at a glance.
Looking For More Ideas Beyond Alamo Group?
If the Alamo Group story has you rethinking concentration risk, it can help to line it up against other opportunities that share some qualities but offer different return drivers. The Simply Wall St Screener gives you a quick way to compare balance sheets, cash generation and income profiles across a wide range of listed businesses.
- If capital preservation sits high on your list, consider starting with a basket of relatively steady candidates through a 30 resilient stocks with low risk scores that focuses on resilience rather than excitement.
- For readers who care most about quality at a sensible price, you can scan a 36 high quality undervalued stocks that filters for stronger fundamentals paired with valuations that may not fully reflect them.
- If regular cash payouts matter to your plan, use a yield focused 5 dividend fortresses aimed at finding companies combining higher income with balance sheets that can support those distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com