
Did Snapshot Pro Rollout Just Shift Progressive's (PGR) Investment Narrative?
- Progressive recently finished rolling out Snapshot Pro, a unified telematics program that merges Snapshot ProView and Smart Haul for most commercial auto customers and connects either to existing telematics hardware or Progressive devices, with potential savings tied to driving behavior during enrollment and renewal terms.
- The full launch of Snapshot Pro gives Progressive a broader telematics footprint in commercial auto, which can influence underwriting data quality, operating efficiency, and how the insurer prices risk for business fleets.
- We will now look at how Progressive's investment narrative is affected by the expanded Snapshot Pro telematics program for commercial customers.
Scan how Progressive's telematics push compares with other insurers reshaping commercial auto risk, starting with a curated set of 30 resilient stocks with low risk scores.
Progressive Investment Narrative Recap
For a shareholder in Progressive, the core belief is that its scale, data and direct distribution can keep offsetting pressure from a more competitive, potentially deflationary auto market described in the analyst consensus Narrative on Simply Wall St. Snapshot Pro fits neatly into that story, since richer telematics data can feed underwriting decisions, pricing and loss ratio management in both personal and commercial motor.
In the near term, the key swing factor is whether Progressive can hold combined ratios in check while claims severity and competition both stay in focus. Snapshot Pro looks additive but not obviously transformative to the short term earnings outlook, especially with analysts expecting revenue growth of 2.9% a year and a decline in profits over the next three years.
The Snapshot Pro rollout ties directly into one of the Narrative catalysts, which is Progressive's long running push into analytics and telematics across auto and property. This program broadens that toolkit on the commercial side, giving the insurer more behavioral data on fleets and small businesses where pricing accuracy and fraud control matter a lot to margins.
That same framework also highlights the key risk. Analysts already assume earnings will decline 6.2% a year over the next three years, and loss trends remain sensitive to bodily injury and physical damage costs. Snapshot Pro can support execution on pricing and selection, but investors still have to watch whether the extra insight meaningfully counters claim cost pressure in a competitive U.S. auto insurance market.
What The Snapshot Pro Rollout Implies For Progressive's Forecasts
Progressive's telematics expansion lands against analyst assumptions that already bake in modest revenue growth, thinner profit margins and softer earnings. The Snapshot Pro program slots into this backdrop as one more tool that could help management work within those constraints rather than reset expectations entirely.
Analysts in the Simply Wall St report frame the next few years around measured top line expansion. They project revenue rising at 2.9% per year, with the business moving from a profit margin of 12.8% today to 9.6% in roughly three years. That margin compression sits in the background when you think about what more granular telematics data might do for underwriting quality, fraud detection and fleet pricing discipline.
Earnings estimates in that same report point to a decline over the coming years. Consensus expects profit to move from US$11.7b today to US$9.5b by 2029, which is a drop of about US$2.2b in absolute terms rather than an increase. For a reader looking at Snapshot Pro, the key question is not whether this single product line reverses that trend, but whether it helps Progressive hold loss ratios and expenses closer to those expectations as commercial auto evolves.
Valuation assumptions remain anchored to those longer term revenue and earnings forecasts. To line up with the analyst narrative, investors would need to assume Progressive generates about US$99.0b of revenue and US$9.5b of earnings in 2029, while the stock trades on a P/E of 17.0x instead of the current 10.6x and above the 11.1x level quoted for the wider US insurance sector. Telematics does not directly set that multiple, although a broader and more effective data footprint in commercial auto can influence how confident the market feels about those future profit streams.
Snapshot Pro's impact sits more in the execution layer than in the headline numbers. The consensus already assumes that profit margins compress and that earnings drift lower, even as revenues grow at a steady 2.9% clip. What telematics can potentially do is help Progressive stay within that earnings corridor by sharpening risk selection, aligning premiums with exposure in small business fleets and potentially reducing frequency or severity of claims where driver behavior responds to feedback.
Progressive's narrative projects US$99.0b revenue and US$9.5b earnings by 2029. This path assumes 2.9% yearly revenue growth and an earnings decrease of about US$2.2b from US$11.7b today.
Uncover why Progressive's fair value aligns with its current price.
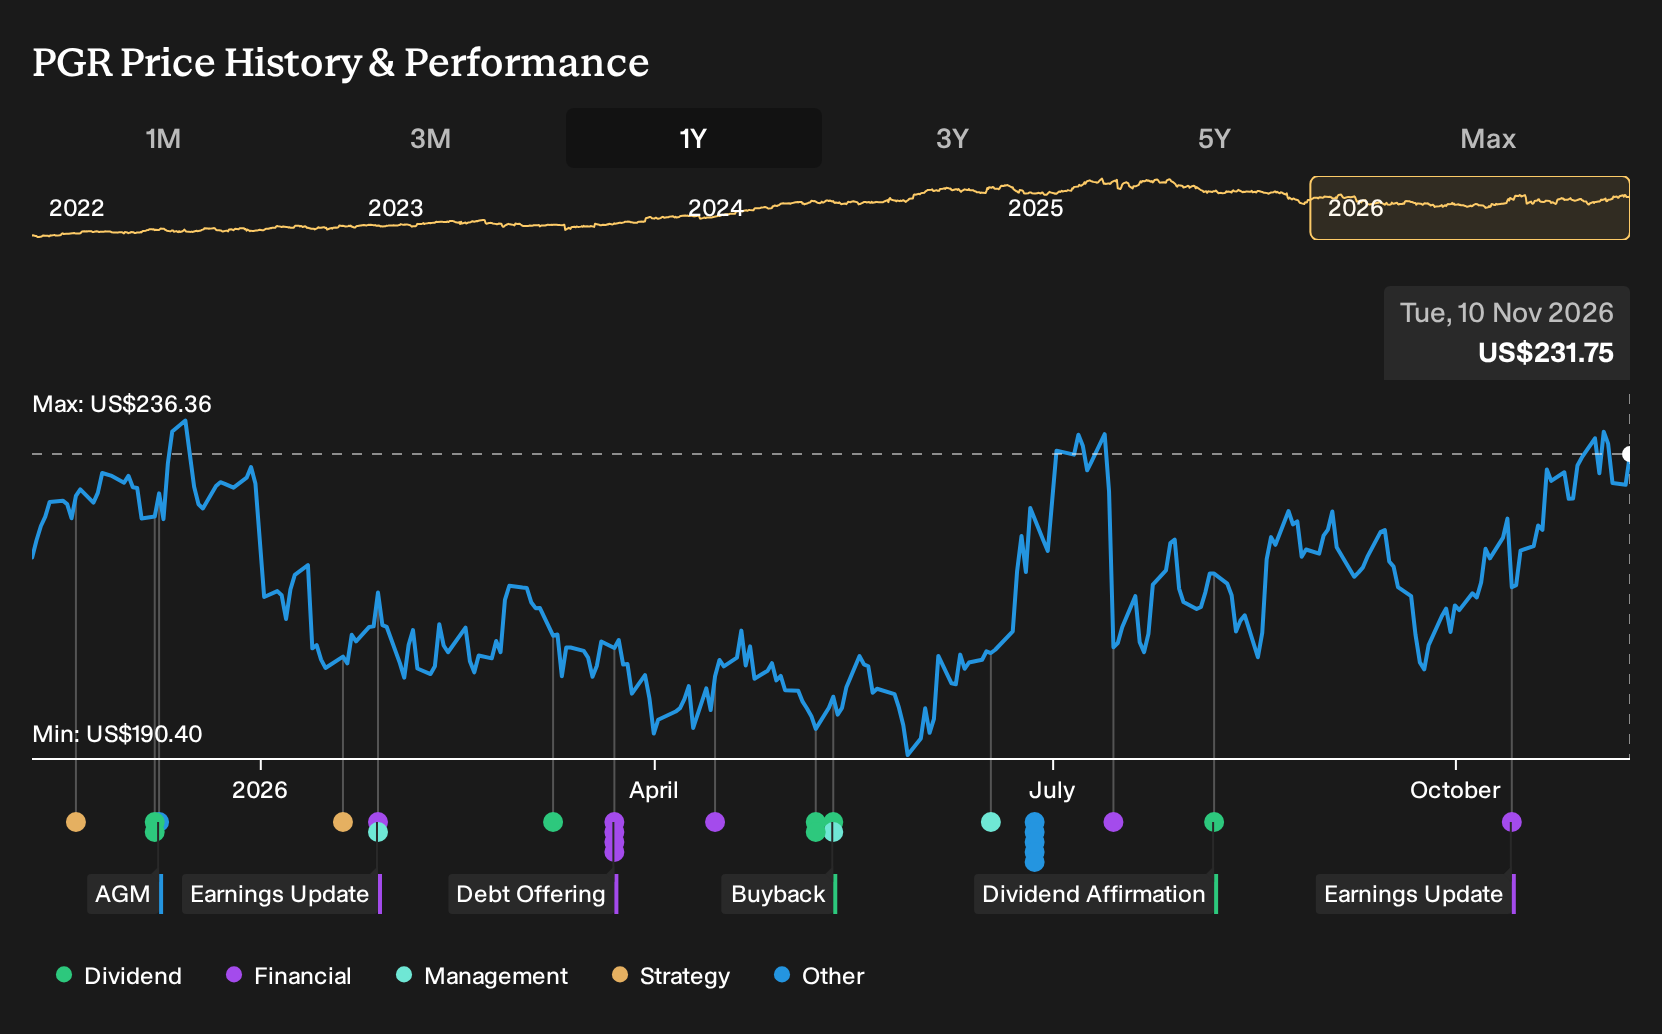
Exploring Other Perspectives
Some of the most optimistic analysts frame Progressive as a volume story rather than just a margin one. Before this Snapshot Pro news, they were already pencilling in 4.6% yearly revenue growth and about US$105.0b of sales by 2029. You can treat those expectations as one end of the range and ask whether broader telematics and programs like Keys to Progress eventually shift forecasts closer to that view or pull them back toward the more cautious consensus.
Explore 3 other Progressive fair value estimates, including one that suggests as much as 102% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Progressive research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Progressive. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Progressive's overall financial health at a glance.
Looking for more investment ideas beyond Progressive?
Once you have a handle on Progressive and its telematics story, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about capital preservation and steadier volatility, consider starting with a curated set of 30 resilient stocks with low risk scores that may better align with a cautious approach.
- If value is your focus and you are hunting for potential mispriced opportunities, scan through a 36 high quality undervalued stocks that combines quality fundamentals with more modest valuation multiples.
- Income focused readers who want cash flow from their portfolio can review a targeted group of 5 dividend fortresses that currently offer yields of 5% or more.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com