
American Electric Power Company (AEP) Expands Infrastructure Push, Is The Stock Fully Valued?
American Electric Power Company (AEP) is reshaping its growth story around large scale energy infrastructure, anchored by a new AEP Infrastructure unit, a US$100b capital plan, and a massive Google data center partnership in Wyoming.
Despite a small 1-day share price decline of 0.38% to US$127.84 and a 7-day share price return that is down 1.56%, American Electric Power Company has a 30-day share price return of 4.10% and a year-to-date share price return of 10.39%, with a 3-year total shareholder return of 83.33%. This suggests that momentum has been building over a longer horizon as investors react to the US$100b capital plan, the AEP Infrastructure launch, the recent earnings update, and the Google data center partnership in Wyoming.
Scan American Electric Power Company’s push into energy infrastructure against a wider field of grid-focused opportunities with a curated list of 41 power grid technology and infrastructure stocks.
American Electric Power Company is pitching a US$100b build out, a new infrastructure arm and a marquee Google contract. After that run in the share price, the question is whether the balance of risk and reward still leans toward buyers as the valuation work starts.
Most Popular Narrative: 4% Undervalued
Against the last close at $127.84, the leading narrative on American Electric Power Company pegs fair value at $133 and points to a small undervaluation that hinges on how its huge capital plan and data center load translate into earnings per share.
AEP is the largest US transmission owner and the cleanest regulated way to own data-centre load. About 90% of the plan is recovered through reduced-lag mechanisms, and the incremental US$22B of capital needs only US$5.2B of new equity. The trade-off is valuation: at 17.0x 2028E the stock already prices a premium-growth utility. That leaves the return mostly in the 9 to 11% EPS growth and the dividend, not in a re-rating.
See why 2 investors see American Electric Power Company as 4% undervalued.
Result: Fair Value of $133 (UNDERVALUED)
Still, the AEP story leans heavily on ERCOT approvals and a US$58.3b funding gap, so setbacks on Texas load or credit metrics could quickly rewrite this thesis.
Find out about the key risks to this American Electric Power Company narrative.
Another View: American Electric Power Company On Earnings Multiples
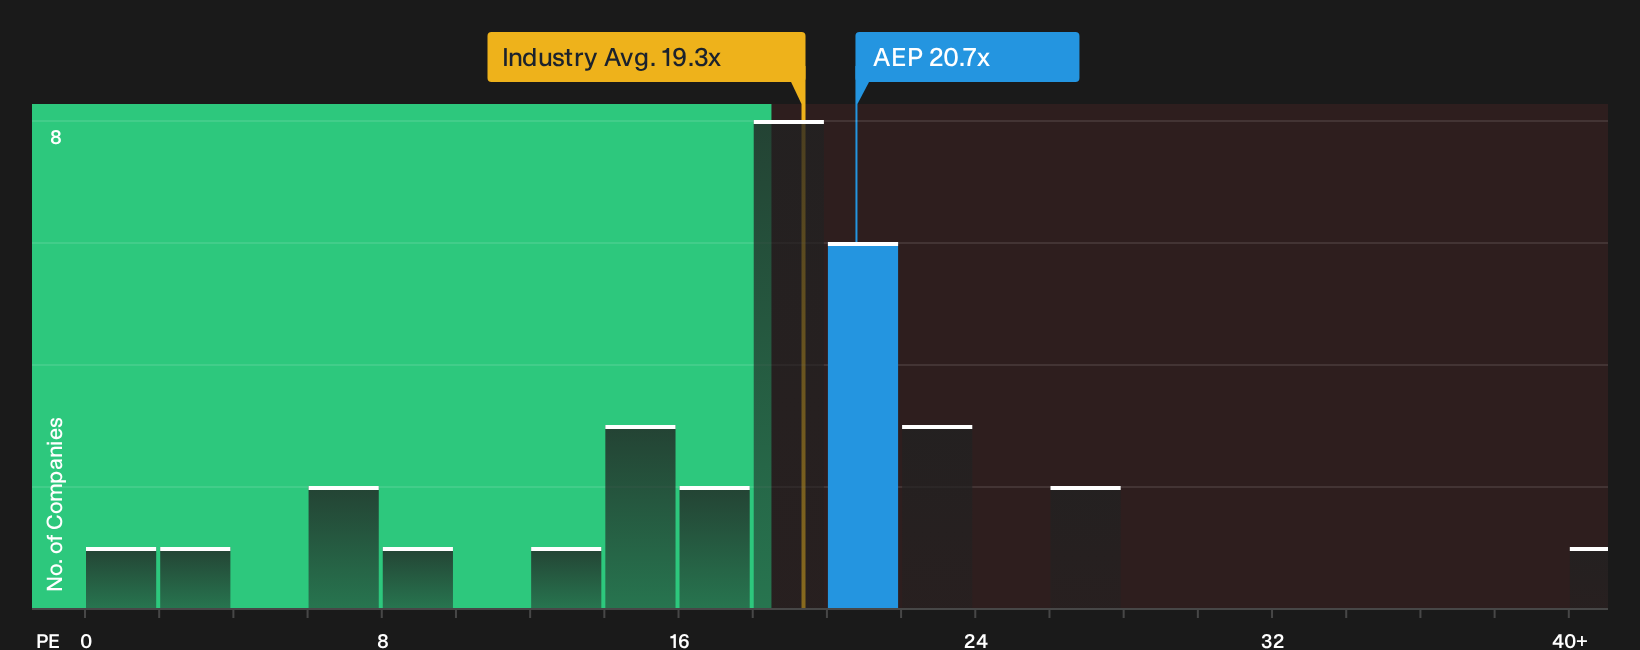
There is a different lens on American Electric Power Company when looking at simple earnings multiples. AEP trades on a P/E of 20.7x, which is higher than the US Electric Utilities industry on 19.3x, but slightly below a peer average of 21.2x and under a fair ratio estimate of 24.4x. That mix of small premium, small discount and a higher fair ratio highlights both valuation risk if sentiment cools and potential upside if the market moves toward that fair ratio. Where in that range do you think the stock truly belongs?
To see how the numbers stack up in more detail, including how this price compares to what the fair ratio implies, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around American Electric Power Company is clear, with both risks and rewards on the table. Move quickly, review the numbers yourself, and weigh the 1 key reward and 2 important warning signs
Looking for more American Electric Power Company style investment ideas?
Do not stop with American Electric Power Company. Broaden your watchlist with other focused ideas that match your risk comfort and return goals while this research is fresh.
- Target potential mispricing by scanning a curated pool of quality companies that trade below estimated value using the 36 high quality undervalued stocks.
- Strengthen your income game by zeroing in on businesses with higher yields and resilient payouts through the 5 dividend fortresses.
- Dial down portfolio stress by filtering for companies that pair sturdy balance sheets with robust fundamentals via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com