
Earnings Beat Might Change The Case For Investing In Pinnacle West Capital Stock (PNW)
- Pinnacle West Capital reported third quarter 2026 sales of US$1,972.75 million and net income of US$434.24 million, with both basic and diluted earnings per share from continuing operations above the prior year period.
- For the first nine months of 2026, Pinnacle West Capital recorded higher sales and net income than a year earlier and lifted its full year earnings guidance to US$5.05 to US$5.25 per diluted share, indicating management confidence in underlying demand and cost execution.
- We will look at how Pinnacle West Capital's raised 2026 earnings guidance affects the investment narrative around Arizona load driven growth.
Scan other regulated utilities showing similar earnings momentum and guidance upgrades with the hand picked 30 resilient stocks with low risk scores, which is aligned to this kind of steadier profile.
Pinnacle West Capital Investment Narrative Recap
To own Pinnacle West Capital, investors need to be comfortable with a regulated utility profile that relies on Arizona load growth and a sizable capital plan. The raised 2026 earnings guidance to US$5.05 to US$5.25 per diluted share is supported by customer and sales trends plus weather, which provides some near term confidence but still depends on execution and regulatory outcomes.
The key short term catalyst is how effectively the multi year US$7.95 billion capital program translates into earnings without eroding returns through higher interest costs. The main current risk is that interest expense, depreciation and weaker transmission revenue continue to pressure profitability even if volumes remain solid.
The most relevant update is the third quarter and nine month 2026 earnings report. Pinnacle West Capital reported third quarter sales of US$1,972.75 million and net income of US$434.24 million, with diluted EPS from continuing operations of US$3.49. For the first nine months, diluted EPS from continuing operations was US$5.20.
This profile is generally consistent with the analyst consensus Narrative on Simply Wall St, which discusses earnings expectations linked to Arizona demand and capital deployment. Recent results show higher sales and earnings alongside headwinds from interest and depreciation, so the near term focus is on whether operational efficiency and regulatory recovery continue to offset those financing and cost pressures.
Pinnacle West Capital Earnings Assumptions and Analyst Targets
Pinnacle West Capital's current analyst narrative leans heavily on incremental revenue and margin gains rather than a complete reset of the business model. Analysts are building their models around Arizona demand and the existing US$7.95b capital plan, then layering in assumptions about how that spending filters through to the income statement over the next few years.
Forecasts in the Simply Wall St report assume revenue expands by 5.1% per year over the next three years, with profit margins moving from 11.5% today to 13.1% by around 2029. That margin lift is what supports the jump in net income from current earnings of US$640.1 million to a consensus forecast of US$845.9 million by 2029, an increase of about US$205.8 million. For investors tracking per share outcomes, the same analyst set sees earnings per share at US$6.37 by 2029, which ties directly to the earnings bridge behind the story.
Valuation work in the report links those operating assumptions to a specific market outcome for Pinnacle West Capital. To line up with the consensus view, revenues would reach about US$6.4b in 2029 and earnings would land at roughly US$845.9 million, with the stock trading on a P/E of 19.3x. That multiple is lower than the current 20.1x attached to the company and slightly under the 20.2x cited for the broader US electric utilities group. This means the scenario does not rely on a richer valuation multiple to make the numbers work.
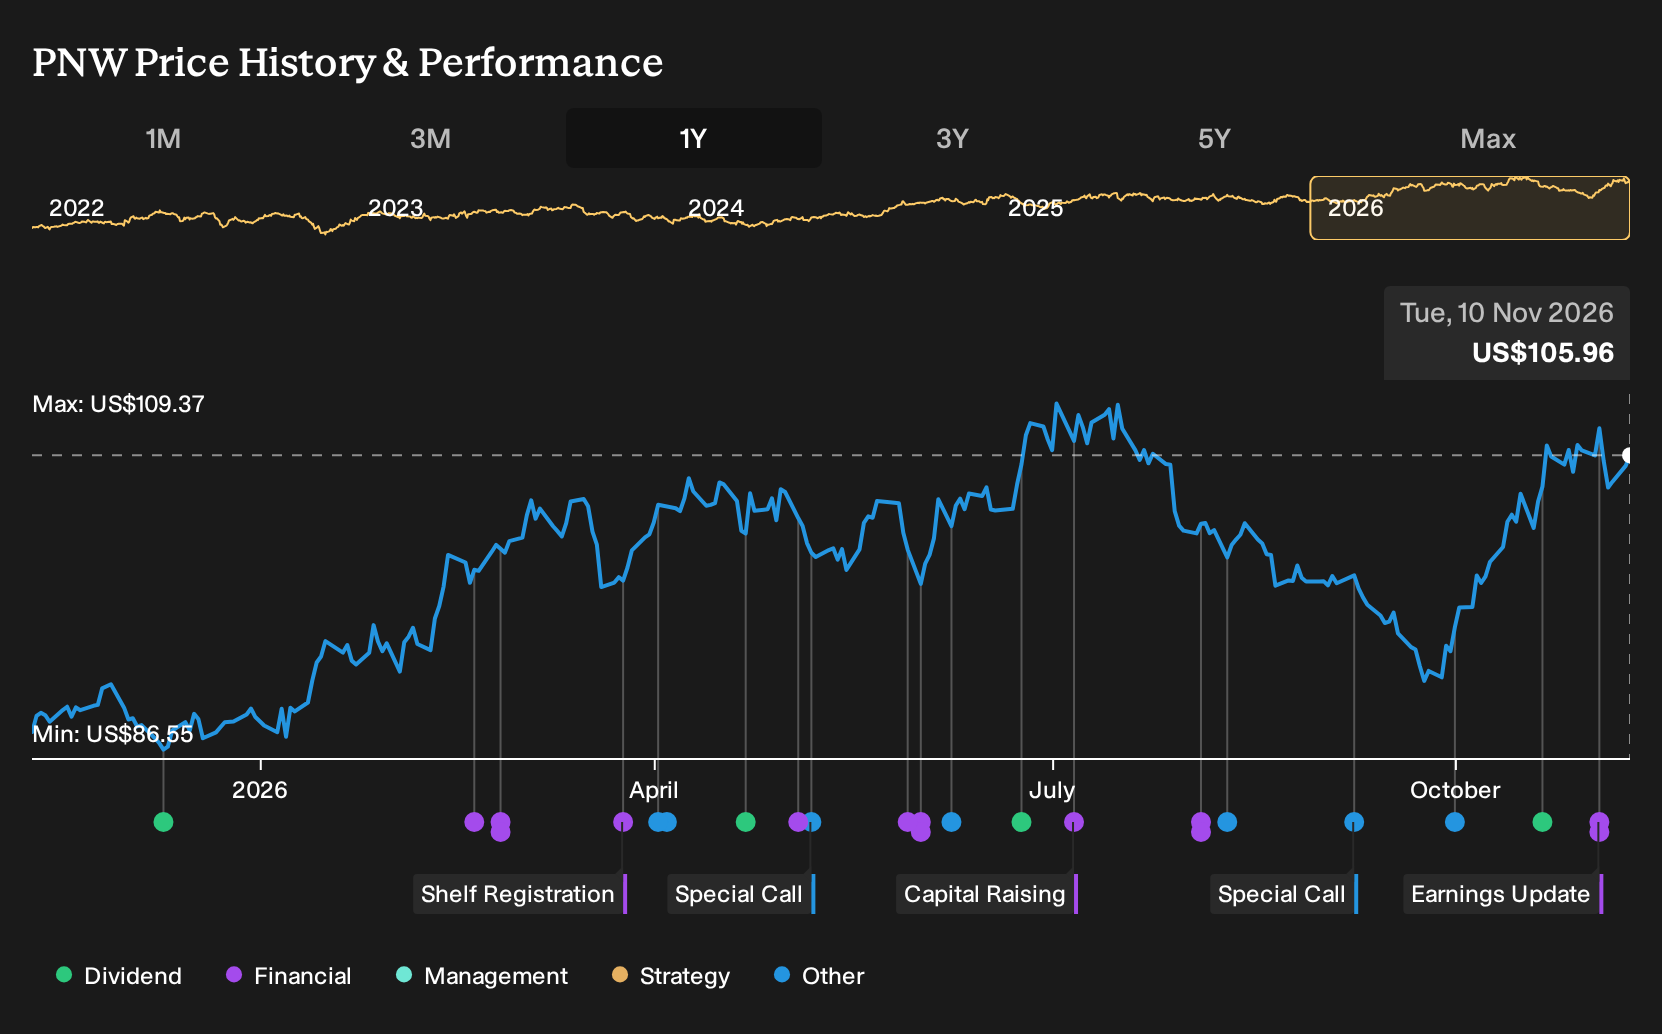
The price target range itself reflects moderate disagreement rather than a binary bull or bear split. Analyst targets cluster around a consensus of US$104.97, with the high estimate at US$119.50 and the low at US$89.00, against a current share price of US$106.28 as of late 2026. The roughly 1.3% gap between the market price and the average target suggests analysts on balance view Pinnacle West Capital as close to fully valued on these assumptions. Any change in the outlook for Arizona demand, capital recovery or cost of capital could become an important swing factor.
Pinnacle West Capital's narrative projects US$6.4b revenue and US$845.9 million earnings by 2029. This requires 5.1% yearly revenue growth and an earnings increase of about US$205.8 million from current earnings of US$640.1 million.
Uncover why Pinnacle West Capital's fair value indicates a value that is roughly in line with its current price.
Exploring Other Perspectives
The Simply Wall St Community adds two retail investor fair value views for Pinnacle West Capital, stretching from about US$89.76 to roughly US$104.97 per share. Those opinions sit beside fresh earnings guidance tied to Arizona load growth and heavy capital spend, which could either support that range or challenge it. You can compare your own expectations on demand, regulation and financing costs against this spread and explore how other community members frame upside and downside for the stock.
Explore another Pinnacle West Capital fair value estimate, including one that suggests as much as 15% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pinnacle West Capital research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Pinnacle West Capital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pinnacle West Capital's overall financial health at a glance.
Looking For More Investment Ideas Beyond Pinnacle West Capital?
If the Pinnacle West Capital story has sharpened your view on earnings quality and valuation, you can use that same lens across the wider market. The Simply Wall St Screener lets you quickly filter for different types of opportunities so you can build a watchlist that fits your risk tolerance and income needs.
- For investors who care most about capital strength and balance sheet resilience, start with a list of solid balance sheet and fundamentals (24 results) that already screens for financial sturdiness.
- If long term wealth building through mispriced quality appeals to you, scan a curated set of 36 high quality undervalued stocks that pair strong fundamentals with what analysts view as attractive pricing.
- Income focused readers who prioritise steady cash returns can focus on 5 dividend fortresses that combine higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com