
Is Simon Property Group (SPG) Fairly Valued As Higher FFO Guidance Lifts Optimism?
Simon Property Group (SPG) has just paired strong third quarter revenue growth with a higher 2026 real estate FFO outlook, a larger common dividend, and ongoing share repurchases, which is sharpening attention on shareholder return priorities.
Recent trading has been strong, with a 30 day share price return of 17.58% and a year to date gain of 27.46%. The latest close at US$234.48 sits against a 1 year total shareholder return of 32.62% and a 3 year total shareholder return of 124.87%. This points to momentum that investors appear to be linking to Simon Property Group’s higher real estate FFO guidance, dividend increase, and ongoing buybacks, despite the slightly lower net income range for 2026.
Surf 5 dividend fortresses to see how Simon Property Group's income profile compares with other high-yield plays that pair shareholder payouts with balance sheet resilience.Bulls view Simon Property Group’s focus on cash flow, a higher dividend, and active buybacks as potential drivers of further upside, while bears highlight lower net income guidance and interest rate risk. The key question is which side the current valuation supports next.
Most Popular Narrative: 2% Overvalued
Compared with Simon Property Group's last close at $234.48, the analyst consensus Narrative on Simply Wall St anchors fair value at $229, implying a small premium that frames how much future cash flow strength is already priced in given a 7.87% discount rate.
Ongoing redevelopment and mixed-use projects, including about US$1.07b of developments under way at blended 9% yields, more than US$600 million of projects expected to start in the second half of 2026 and a longer term pipeline above US$4b funded largely from internal cash flow after dividends, provide a path for higher net operating income and earnings over time.
See why 63 investors see Simon Property Group as 2% overvalued.
Result: Fair Value of $229 (OVERVALUED)
Still, the narrative can crack if higher interest costs bite harder than expected or if redevelopment projects miss leasing or return assumptions and drag on cash flow.
Find out about the key risks to this Simon Property Group narrative.
Another View on Simon Property Group’s Valuation
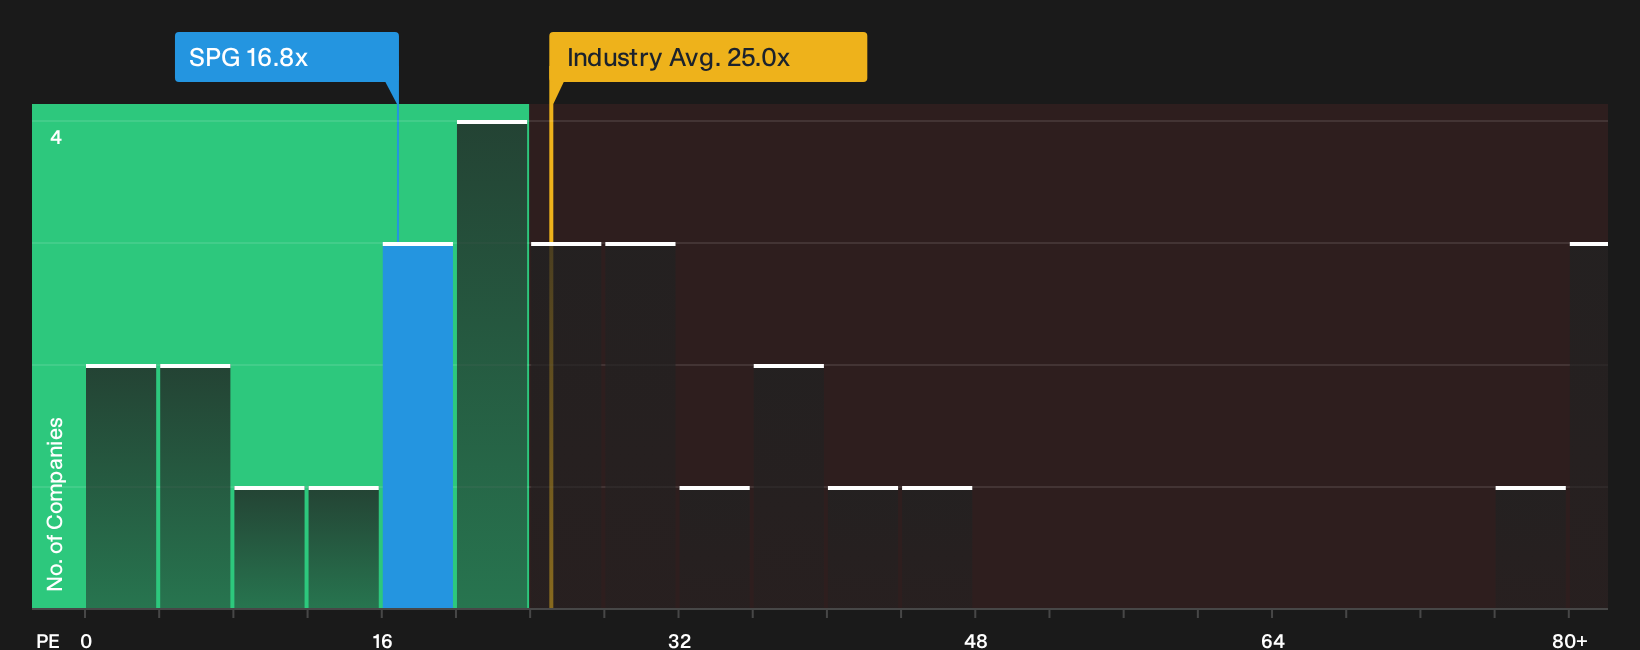
The analyst fair value of $229 pegs Simon Property Group as about 2% overvalued on future earnings assumptions. A different picture emerges when looking at the current P/E of 16.8x against the US Retail REITs industry at 25x and a fair ratio of 25.6x. This comparison signals a sizable valuation gap that could either close through price moves or through changing fundamentals. Which side of that equation do you think shifts first?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these only matter if you pressure test them yourself and act before the crowd reshapes the story. Start by weighing Simon Property Group's risks against its potential upside through 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond Simon Property Group?
If Simon Property Group has sharpened your focus on quality and price, broaden the view with a few curated idea lists that can help you stress test your next move.
- Target robust cash generators with room for sentiment to catch up by scanning our universe of quality-at-a-discount opportunities through the 36 high quality undervalued stocks.
- Prioritise resilience first and let potential upside be the bonus by sorting companies that clear a higher bar for financial strength via the list of solid balance sheet and fundamentals (24 results).
- Hunt for lesser known opportunities before they hit the mainstream radar by filtering through the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com