
Tokyo Ohka Kogyo (TSE:4186) Faces Valuation Questions After Sharp Swings And Long Term Gains
Recent commentary has put Tokyo Ohka Kogyo (TSE:4186) under the spotlight, questioning whether its share price fully reflects current earnings power after a period of very strong long term returns.
The share price has been volatile recently, with a 1 day share price return of 9.91% coming after the stock fell 21.26% over the past 30 days. Yet Tokyo Ohka Kogyo still shows strong momentum when you zoom out, with a 5 year total shareholder return of 228.74%, hinting at how firmly longer term holders have been rewarded.
Spot potential peers to Tokyo Ohka Kogyo by scanning a curated set of resilient materials and semiconductor suppliers in the 19 resilient stocks with low risk scores.For Tokyo Ohka Kogyo, bulls see a key supplier to resilient semiconductor demand; bears see a stock whose strong run and rich P/E leave little room for comfort. Which case do the current valuation markers support next?
Price-to-Earnings of 22x: Is it justified?
Tokyo Ohka Kogyo trades on a P/E of 22x, which sits well above several reference points and places it firmly in premium territory relative to peers.
The P/E ratio compares the current share price with earnings per share. For a specialist materials supplier into semiconductors, this often reflects how the market weighs current profitability alongside expectations for future cash generation and the resilience of demand for its products.
Here, investors are paying a much steeper multiple than the JP Chemicals industry average of 11.1x and the peer average of 16.4x. The stock also trades above an estimated fair P/E of 17.6x. That combination indicates a rich earnings valuation and a level the market could move toward if sentiment or growth assumptions cool.
Explore the SWS fair ratio for Tokyo Ohka Kogyo.
Result: Price-to-Earnings of 22x (OVERVALUED)
Still, the Tokyo Ohka Kogyo story could be knocked off course if semiconductor spending weakens or if its premium P/E multiple compresses toward levels more in line with the sector.
Find out about the key risks to this Tokyo Ohka Kogyo narrative.
Another View: SWS DCF Says Undervalued
While the P/E of 22x makes Tokyo Ohka Kogyo look expensive next to peers, the SWS DCF model comes to a very different conclusion. On that cash flow view, the share price of ¥7,350 compares with an estimated future cash flow value of ¥15,927.6, which points to undervaluation.
That sort of gap raises a direct question for you as an investor: Is the P/E sending a caution signal that matters more, or is the DCF flagging mispriced long term cash generation potential that the market has not fully recognized yet?
Look into how the SWS DCF model arrives at its fair value.
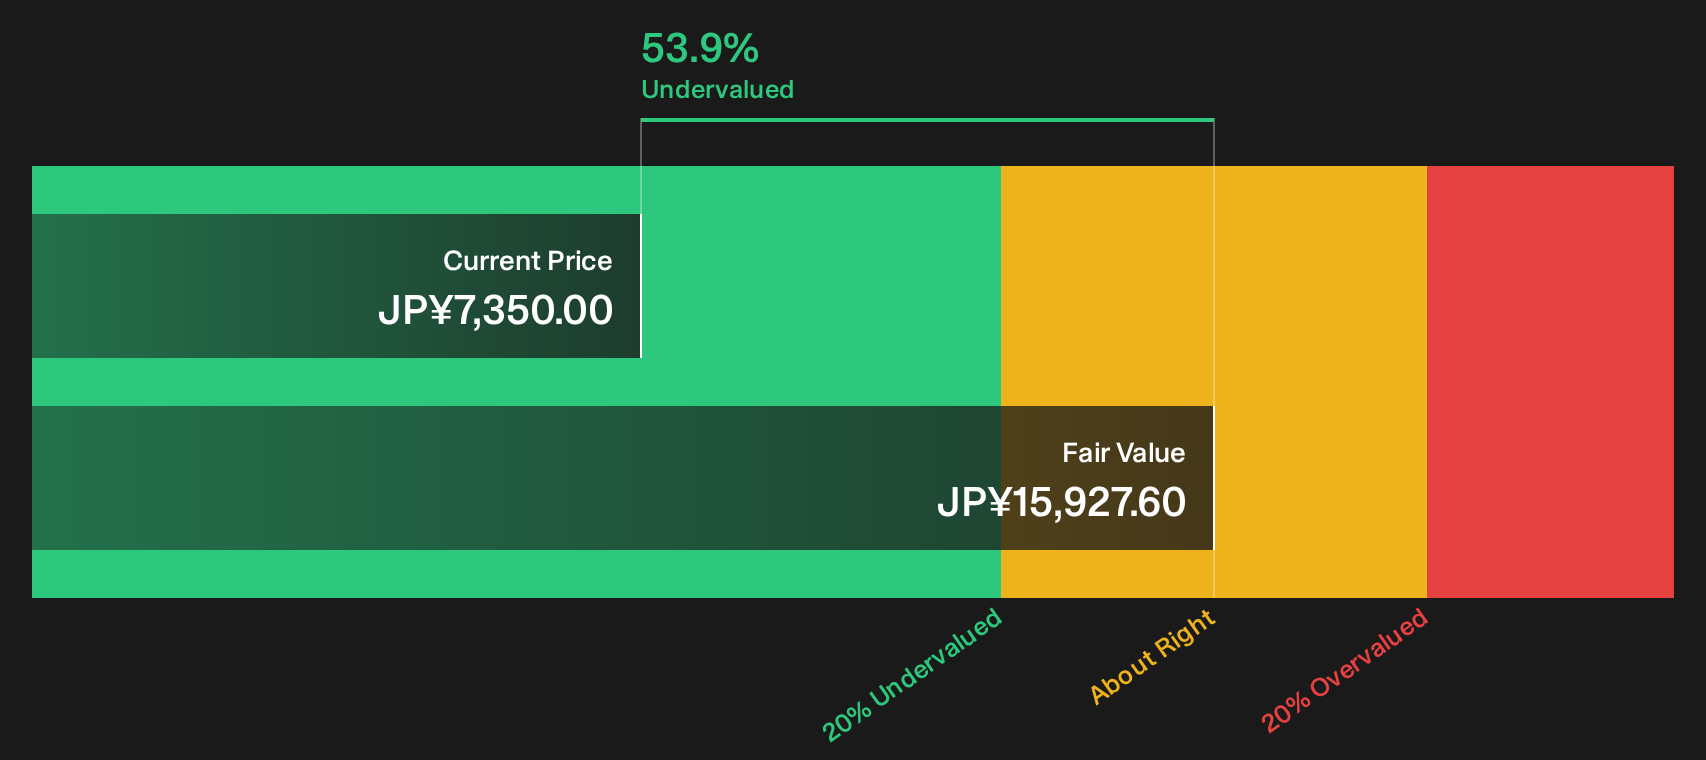
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tokyo Ohka Kogyo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 21 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this split verdict on Tokyo Ohka Kogyo leaves you undecided, act promptly. Review the underlying metrics, weigh both the cautions and the upside, then examine the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Tokyo Ohka Kogyo?
If Tokyo Ohka Kogyo has sharpened your sense for valuation gaps and risk, you may want to broaden your watchlist with a few focused stock ideas built from the Simply Wall St screener.
- Target potential bargains by scanning a curated mix of quality companies that trade below their estimated worth with the 21 high quality undervalued stocks.
- Strengthen your downside protection by reviewing a list of solid balance sheet and fundamentals (23 results) that can help you focus on financially resilient businesses.
- Search for a 73 high quality undiscovered gems that highlights companies with solid fundamentals before they attract wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com