
Oil Below $90 Puts Singapore Airlines Stock And Energy Heavy Cyclicals In Focus
Oil has slipped back below $90 a barrel, conflict risk feels a little less acute, and suddenly some of the most energy hungry industries on the planet are working with a different set of numbers. When fuel becomes less of a tax on every mile flown or ton shipped, cash flows can stretch further and investor attention can shift. This article examines three stocks that sit at the crossroads of that change and outlines how this news event affects each one in a different way.
The stocks highlighted below are just a small sample of this theme. The full screen surfaced 377 more companies with equally compelling stories that are not covered here. To identify, analyze, and focus on the most interesting energy intensive plays for your watchlist, head straight into the Global Energy-Intensive Cyclical Stocks screener.
Shandong Hongqiao Aluminum Industry Holding (SZSE:002379)
Shandong Hongqiao Aluminum Industry Holding runs highly energy intensive aluminum smelting and processing operations in China and overseas, producing electrolytic, liquid, recycled and deep processed aluminum products, with a market value of about CN¥190.4b.
Heavy electricity use makes Shandong Hongqiao Aluminum Industry Holding tightly linked to the theme of energy intensive cyclicals, so lower fuel and power costs can meaningfully affect profitability in this commodity business. Investors watching the recent drop in oil may care most about what happens when one unseen pressure on its cost base shifts.
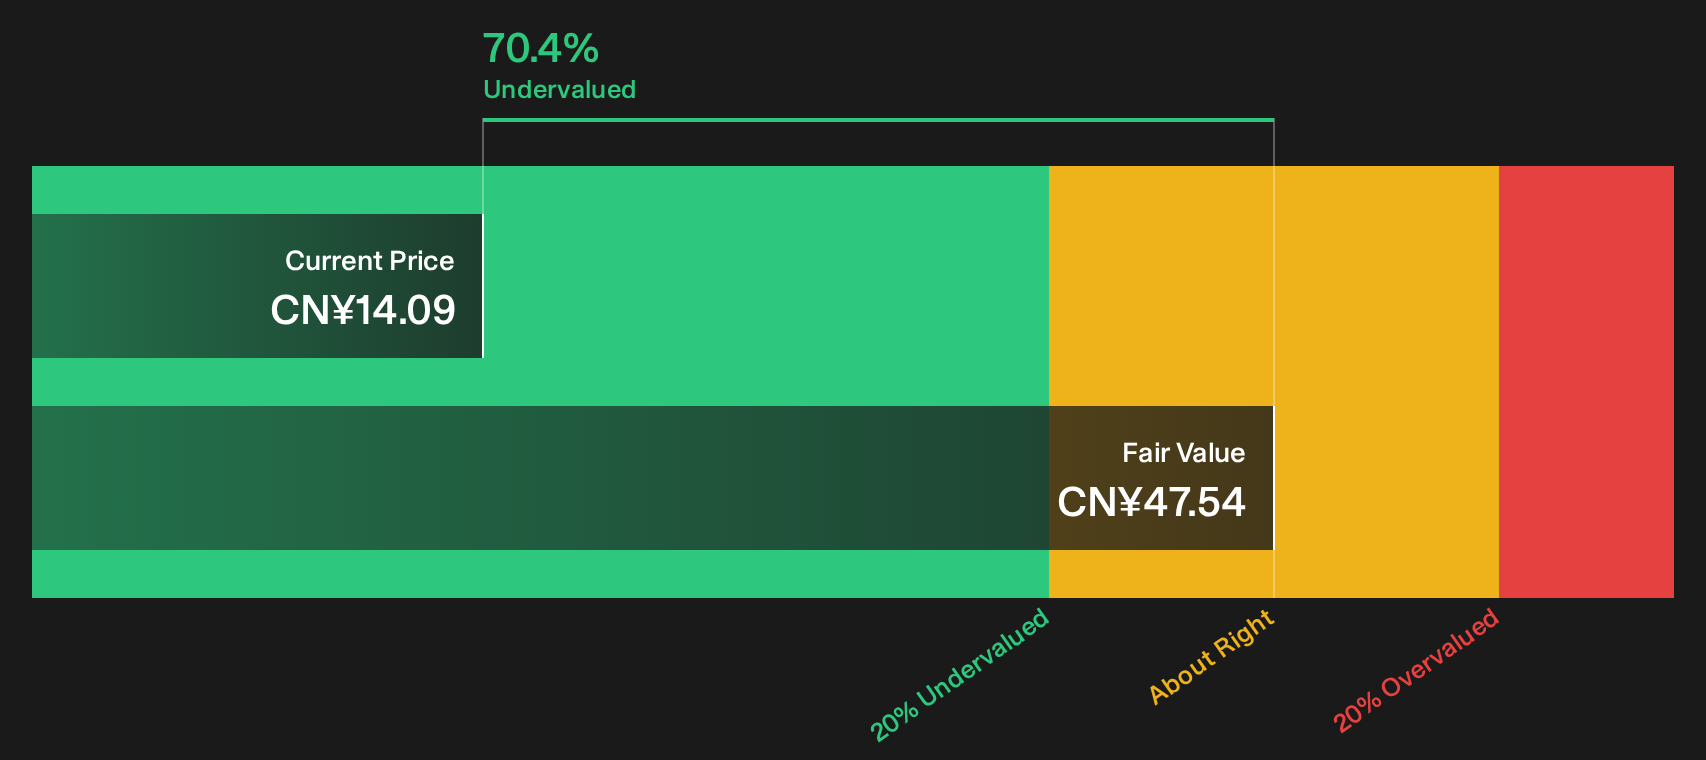
When that pressure on costs shifts, the key question is how it could filter through to profitability, which is exactly what the DCF valuation analysis for Shandong Hongqiao Aluminum Industry Holding starts to unpack for you.
Dangote Cement (NGSE:DANGCEM)
Dangote Cement is an energy heavy cement producer whose kilns, power needs and transport footprint tie it closely to fuel costs, with about NGN 3.4t revenue from Nigeria and NGN 1.6t from Pan Africa, and a market value near NGN 24.6t.
For an energy intensive cyclical like Dangote Cement, what really matters now is how efficiently it can turn fuel and logistics costs into durable cash generation. This is exactly where the analyst consensus Narrative on Simply Wall St picks up the story.
"The ongoing conversion of Dangote Cement’s truck fleet to CNG, with about 3,000 trucks already converted and a target for virtually all more than 8,000 trucks to run on CNG by 2027, directly addresses haulage costs where CNG is reported to cost roughly 40% of AGO and can therefore support operating margin and earnings quality."
What happens if a single assumption inside that wider cost and capacity plan breaks will likely decide how resilient those margins really are.
If that risk feels crucial to your thesis, read the full narrative for Dangote Cement to see how fuel strategy, pricing power and capacity plans could be accelerating or masking future returns.

Singapore Airlines (SGX:C6L)
Singapore Airlines is a fuel hungry global carrier firmly tied to the Global Energy Intensive Cyclical Stocks theme, with its full service and low cost units generating about S$17.4b and S$2.6b of revenue respectively, plus S$1.4b from engineering services, and a market value near S$21.9b.
Cheaper oil and firm travel demand place Singapore Airlines in a favorable position within this screen. The analyst consensus Narrative on Simply Wall St focuses on how its fleet choices could turn that fuel exposure into margin support rather than a constraint.
"Fleet renewal with an average age of about 7 years and continued deliveries that keep the aircraft count on track to reach 218 units gives Singapore Airlines the opportunity to benefit from up to 25% better fuel efficiency on new generation aircraft and potentially support net margins as capacity expands."
What really moves the dial now is whether one unseen pressure inside that fuel and non fuel cost mix quietly squeezes or protects those margins.
If that unseen pressure on Singapore Airlines margins feels like the real story, read the full narrative for Singapore Airlines to see what could be accelerating or quietly masking returns.

Seeking Fresh Alternatives Before They Fly
Some opportunities are already building breakout momentum while others are quietly dropping into attractive ranges under the radar for now. Before the crowd gets caught up, consider your options in advance.
- Target dependable income streams by scanning 217 dividend fortresses curated for investors who want payouts that aim to keep working while prices move around them.
- Hunt for potential category leaders through the 573 high quality undiscovered gems collection, where lesser-known businesses with strong fundamentals are still priced like they have something to prove.
- Explore the structural buildout of next-gen AI infrastructure with the 53 AI infrastructure stocks universe, filtered for companies supporting data centers, chips, and critical hardware.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com