
This Beaten-Down AI Stock Got a Massive Vote of Confidence From Industry Giants
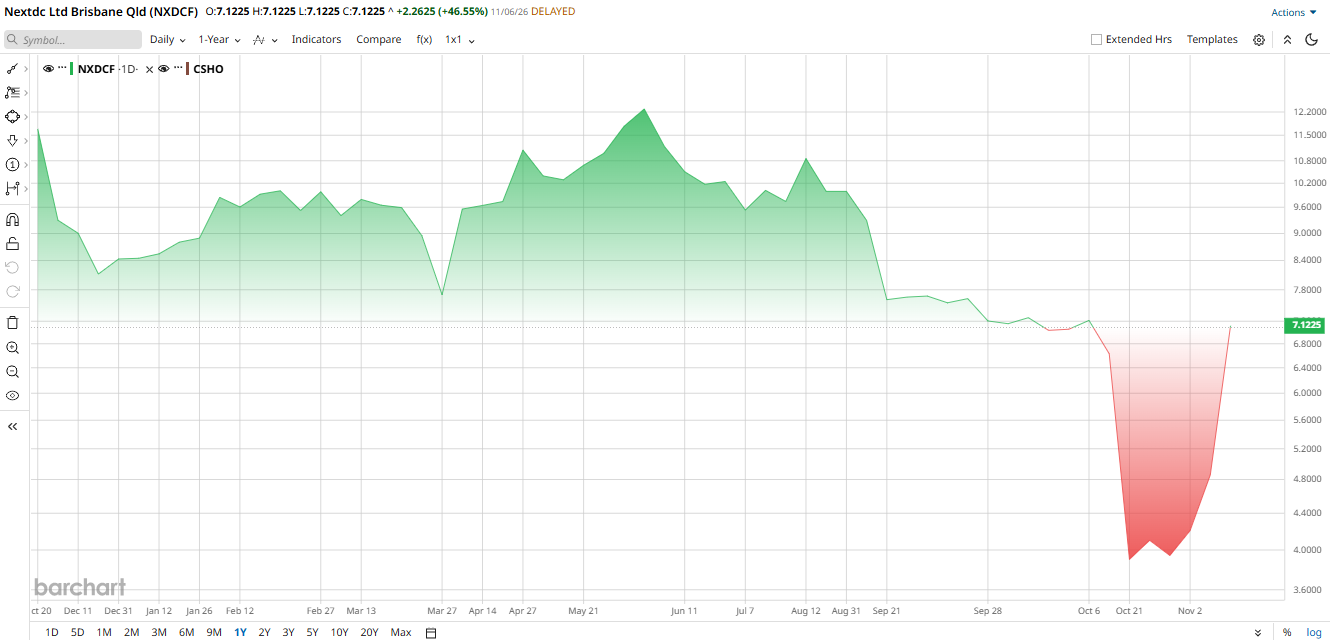
NextDC (NXDCF) has suddenly become one of the more interesting data center stocks to watch after reports that Goodman Group (GMGSF) and Digital Realty Trust (DLR) are acquiring a 9.9% stake through Ackland Investments at A$9.50 per share.
That price is about 45% higher than the previous market price, driving shares up about 40% to 45%.
It's followed by a bad few years for NextDC. Shares fell by some 45% in October after delays in its M3 Melbourne project, sharply lower fiscal 2027 guidance, and a moratorium on new projects by management. The share price had been falling nearly 15% in 2026 prior to the latest rebound.
The company's FY2026 results, meanwhile, showed continued business growth. Revenue grew 16% to A$405 million with underlying EBITDA up 15% to A$248.8 million, beating the guidance. Revenue grew 16%, and underlying EBITDA was 15% higher than the previous year, beating the guided figures.
Why the Stake News Matters
Goodman is a leading property group, and Digital Realty is one of the world's largest data center operators. They reported an investment to the extent of 9.9%, making it a premium, indicating that they have a long-term interest in the company's assets and AI exposure.
The term of this agreement has the potential for commercial association, financial support, and maybe even a takeover offer. This is not a takeover offer but a minority acquisition offer. NextDC board members have called the action “opportunistic,” and there is no assurance that the purchasers will look to acquire control of NextDC.
The A$9.50 per share price paid is now a reference point. The issue is whether the customers venture further in utilization or assist with shifting NextDC's pipeline towards paying customers. While sentiment will be improved by the stake news, it will not cure project delays.
Strong Growth Outlook, Heavy Spending Needs
NextDC reported an A$82.1 million statutory net income in FY2026, bringing the company back to profitability after a A$60.5 million loss the prior year. Part of this improvement was due to an A$129 million fair-value gain on an investment property and some tax-related items. The drop in operating cash flow was to around A$100 million in FY2025, down from A$223 million.
AI and cloud customers continue to be upbeat. NextDC landed a fresh deal for 495 MW of installation contracts for a record 495 MW of new contracts and commissioned a 565 MW installation with a binding order book for FY2026. But, of its contracted 740 MW capacity, only 175 MW was earning money.
As we look ahead, Management's guidance for FY2027 is for revenue to be in the range of A$615 million to A$640 million and EBITDA of A$385 million to A$410 million. Capital spending is expected to be A$5.25 billion to A$5.75 billion.
Despite some risks due to delays in execution and increased development costs, NextDC finished FY2026 with A$876 million of cash on hand and a pro forma liquidity of A$8.7 billion.
Is NextDC Stock Still Expensive?
Valuation is on the high side relative to earnings. NextDC has a trailing price-earnings ratio of 80x and a price-to-revenue ratio for FY2026 at 8x. It's significantly higher than the average earnings multiples of roughly 25x for stocks in technology-related businesses.
Price-to-earnings (P/E) indicates the swing from loss to profit in recent years and also suggests swift growth in the future. Conversely, the stock is currently selling cheap in comparison to its book value of 1.3x vs. a 3x sector median, putting a relatively low valuation on its asset base.
However, data centers are high-capital-cost projects that need to be undertaken ahead of revenue. It does not mean that a low price/books (P/B) is necessarily low. This is when project delays and low returns on the planned capacity can result in such. Investors should keep an eye on NextDC to fulfill the contractual timelines and realize the contracted MWs in billings.
Analysts See Modest Upside
The overall picture of the NextDC stock is positive, although it is by no means a universal one. TipRanks has nine “Buy” ratings and three “Holds” from 11 analysts, on average, with a target price of around A$12, suggesting more than a 12% upside premium from the current level.
I think NextDC has attracted several key industry investors and a resurgence of growth, and it's now up to the execution. If projects continue to move forward and the billing picks up, the stock may continue to go higher. However, when purchased with a speculation on the takeover alone, the investors are at risk if a bigger bid does not follow.
On the date of publication, Nauman Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.