
Wall Street Turns Bullish on Uber as Profitability Strengthens Its Growth Story
Analysts are lining up behind Uber (NYSE:UBER), with 9 Strong Buy and 32 Buy ratings against a single Sell. The 24/7 Wall St. price target for Uber is $107.27, which means 53.5% upside from the $69.87 close.
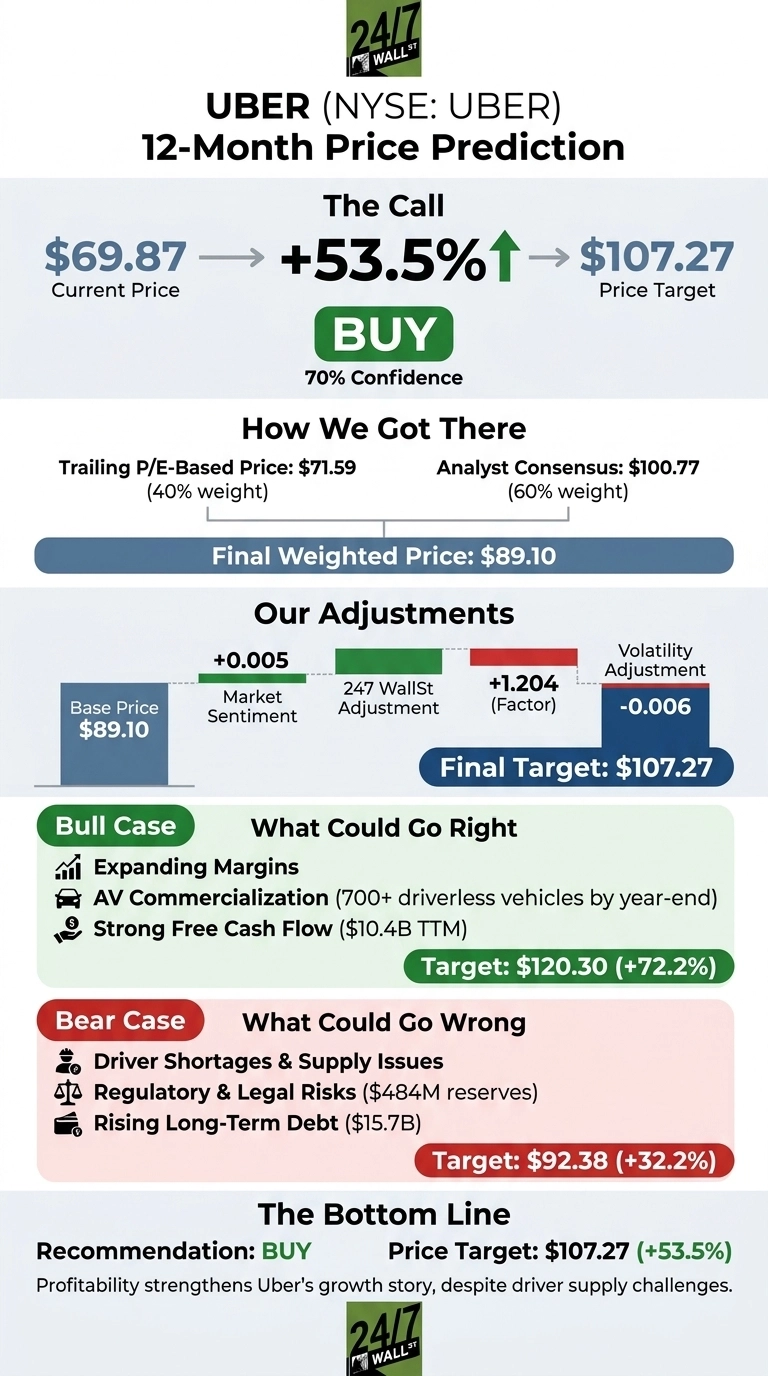 24/7 Wall St. Metric Value Current Price $69.87 Price Target from 24/7 Wall St. $107.27 Upside 53.5% Model Rating BUY Confidence Level 70%
A 70% confidence reading is fairly high. Profits are rising quickly, but the stock still carries a 15 trailing earnings multiple. Q4 guidance calls for non-GAAP EPS growth of 34% to 39%.
Uber Bounces Off Its Lows After a Revenue BeatShares rose 4.91% on earnings day and 7.05% for the week. The shares remain down 14.49% year to date and sit 26.6% below the 52-week high of $95.18.
Q3 revenue of $14.77 billion beat the $14.67 billion estimate, while non-GAAP EPS of $0.88 fell short of the $0.90 expected. Gross Bookings rose 20% to $59.8 billion. The CEO told CNBC that Uber is “investing significantly” to add drivers.
Why Bulls See $120 Within ReachThe bull case hits $120.30, or 72.2% upside. Delivery is the main driver. Segment operating income rose 30% to $1.057 billion, and grocery and retail now run at a $15 billion annual rate that is growing 40%.
Autonomous vehicles add a second leg, with about 700 driverless vehicles by year-end and more than 2,000 by the end of 2027. Trailing free cash flow hits a record $10.4 billion. The CFO said, “If anything, you’re seeing the profit ramp expand, and that puts us in a pretty good spot for 2027.”
Driver Shortages and GAAP Noise Could Cap the RallyThe bear case lands at $92.38, still 32.2% above the current price. Mobility revenue fell 2% as driver supply lagged demand, and fuel costs weighed on markets such as Brazil and India. GAAP EPS of $0.25 included $484 million in legal and regulatory reserves.
Long-term debt rose to $15.664 billion, and Freight is still losing money. To be fair, Mobility Gross Bookings grew 18%, segment profit rose 27%, and management said driver supply improved in October.
Uber Sits Between Lyft’s Discount and DoorDash’s PremiumLyft (NASDAQ:LYFT) is Uber’s direct rideshare rival. Its P/E of 2 is skewed by a $2.90 billion non-cash tax benefit, and its operating margin is still negative.
DoorDash (NASDAQ:DASH) competes head-on with Uber Eats. The stock carries a far higher multiple while it works through a pending $17 billion Instacart deal.
Company Trailing P/E Price/FCF Operating Margin Uber 14 14.6 10.7% Lyft 2 6.4 -3.0% DoorDash 88 37.6 5.3%Our target means a multiple of about 23 times earnings. That is well below DoorDash’s multiple even though Uber’s operating margin is higher, so the 24/7 Wall St. price target looks reasonable, if not conservative.
Profit Momentum Keeps Our Model ConstructiveThe 24/7 Wall St. price target stands at $107.27, with a buy model rating at 70% confidence.
Rising margins tip the scale: Adjusted EBITDA hits 5% of Gross Bookings, up from 4.5%. I would grow more confident if Q4 EPS lands within the $0.95 to $0.99 guidance range. I would turn cautious if driver shortages last into 2027. For now, profit growth is outpacing the stock.
Year (November) Price Target from 24/7 Wall St. 2026 (current) $69.87 2027 $105.39 2028 $140.42 2029 $174.53 2030 $192.73Uber would need to keep executing its current strategy for these projections to hold. Getting autonomous vehicles to scale might raise results above this path, while worker-classification rulings could pull them below it.