
Can International Seaways (INSW) Stay Cheap After Record Earnings?
International Seaways has seen its share price move sharply in recent years, which puts a fresh spotlight on whether the current valuation is still grounded in the company’s earnings power. After such a run, the key issue for any holder is how much of that earnings story may already be reflected in today’s price.
- Over the past 5 years the stock has gained roughly 8x, which raises the question of how much long term earnings strength the market is already baking in.
- Record earnings, a larger tanker fleet and active capital returns can support the view that International Seaways may be positioned to convert current market conditions into sustained profit generation.
- The analysts covering International Seaways have run their own numbers. See what analysts think International Seaways's shares could be worth.
The issue now is whether the current share price of International Seaways is justified by the earnings that the business is generating today.
If you are considering International Seaways based on its earnings and capital returns, it may be useful to compare that situation with other stocks screened using 33 high quality undervalued stocks.
Is International Seaways a Bargain on Earnings?
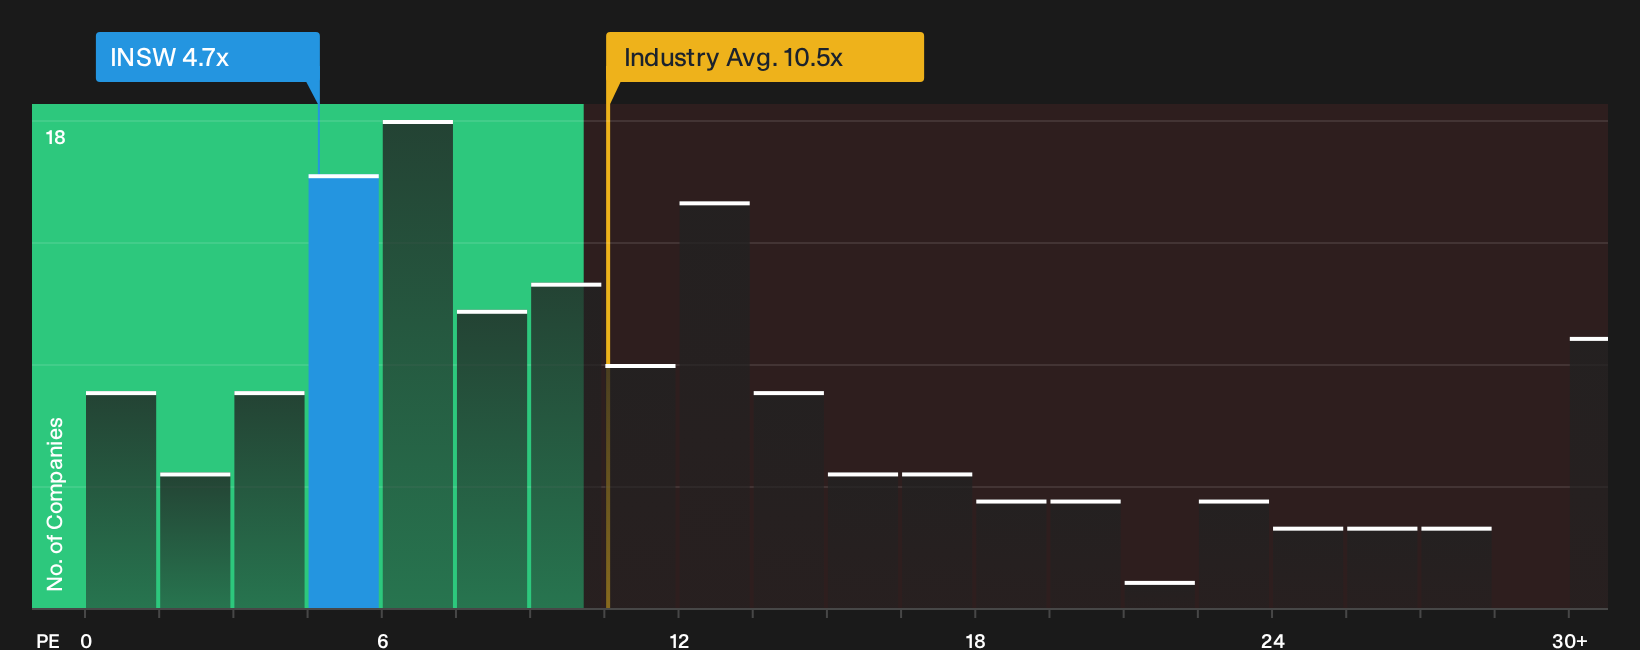
The P/E ratio suits International Seaways because recent results put earnings in clear focus. From this perspective, the stock trades on a P/E of 4.7x, which is well below the oil and gas sector average of 10.5x and also beneath the broader peer group on roughly 17.2x. Compared with the more tailored fair multiple that reflects International Seaways’ margins, risk profile and scale, the current P/E also appears on the cheaper side.
Because record Q3 2026 earnings came through during a strong tanker market, the low P/E suggests investors are treating that profitability as less durable than the headline numbers might imply. For a holder or potential buyer, the gap between the earnings being reported and the price the market is willing to pay per dollar of profit is the key question to probe further. Explore the numbers behind International Seaways's P/E valuation.
The International Seaways Narrative: What Would Justify Today's Price?
Narratives for International Seaways pick up where this valuation puzzle leaves off by spelling out which paths for future earnings, margins and growth would need to play out for the stock to be worth materially more or less than it is today on Simply Wall St's Community page. Instead of stopping at a single ratio or model output, these scenarios unpack the future that number assumes so you can later judge whether reality is staying close to that script.
One of the top narratives on International Seaways: 23% undervalued
This is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The numbers now embedded in International Seaways’ share price, including its recent share price movement, payout ratio and insider selling alongside repeated target changes, imply a valuation that already prices the stock as fairly valued with a skew toward bearish outcomes if tanker conditions or sentiment soften..."
Discover why this Narrative puts International Seaways at 23% undervalued.
International Seaways’ valuation still leaves one crucial issue unresolved
Numbers on International Seaways only tell part of the story, because our research has also highlighted specific risk checks that could change how you weigh everything discussed so far. Take a closer look at 4 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com