
Hubbell (HUBB) Could Be 19% Undervalued Following Raised 2026 Outlook
Hubbell raises 2026 outlook after reporting higher Q3 sales and earnings
Hubbell (HUBB) lifted its full year 2026 earnings guidance after announcing third quarter and nine month results that showed higher sales and net income compared with the same periods a year earlier.
The guidance hike arrives after a choppy period for Hubbell’s shareholders, with the stock gaining 2.82% on the day of the news and 1.81% over the past week, yet still down 6.86% on a 1 month share price basis and 15.02% over 3 months. At the same time, longer term total shareholder returns of 57.82% over 3 years and 128.89% over 5 years point to a stronger multi year story.
Scan beyond Hubbell and see how other power grid technology players are reacting to similar guidance and earnings shifts with the curated 42 power grid technology and infrastructure stocks
Hubbell just raised its 2026 outlook while the share price has slid over the past quarter. Does that combination reward buyers now, or argue for patience and a better entry later as valuation comes into focus?
Most Popular Narrative: 19% Undervalued
Hubbell closed at $441.57, while the analyst consensus Narrative on Simply Wall St cites a fair value of $543.46, implying meaningful upside based on its grid and data center exposure and the updated 2026 guidance.
Hubbell is entering a long period of elevated spending on grid hardening and modernization. This is supported by a strong Utility Solutions order book, a first half 2026 book to bill of about 1.2x and projects already extending into 2027, which can support revenue and earnings growth visibility.
The emerging build out of 550 to 765 kV high voltage transmission, with management pointing to a roughly US$1.5b industry opportunity over 10 years and initial 550 kV and 765 kV shipments starting between late 2026 and 2027, introduces a new revenue layer that can lift Hubbell’s long term earnings power.
See why 20 investors see Hubbell as 19% undervalued.
Result: Fair Value of $543.46 (UNDERVALUED)
Still, the Hubbell narrative can crack if NSI integration drags on margins or if higher interest costs and softer Electrical Solutions profitability squeeze earnings more than analysts expect.
Find out about the key risks to this Hubbell narrative.
Another View on Hubbell’s Valuation
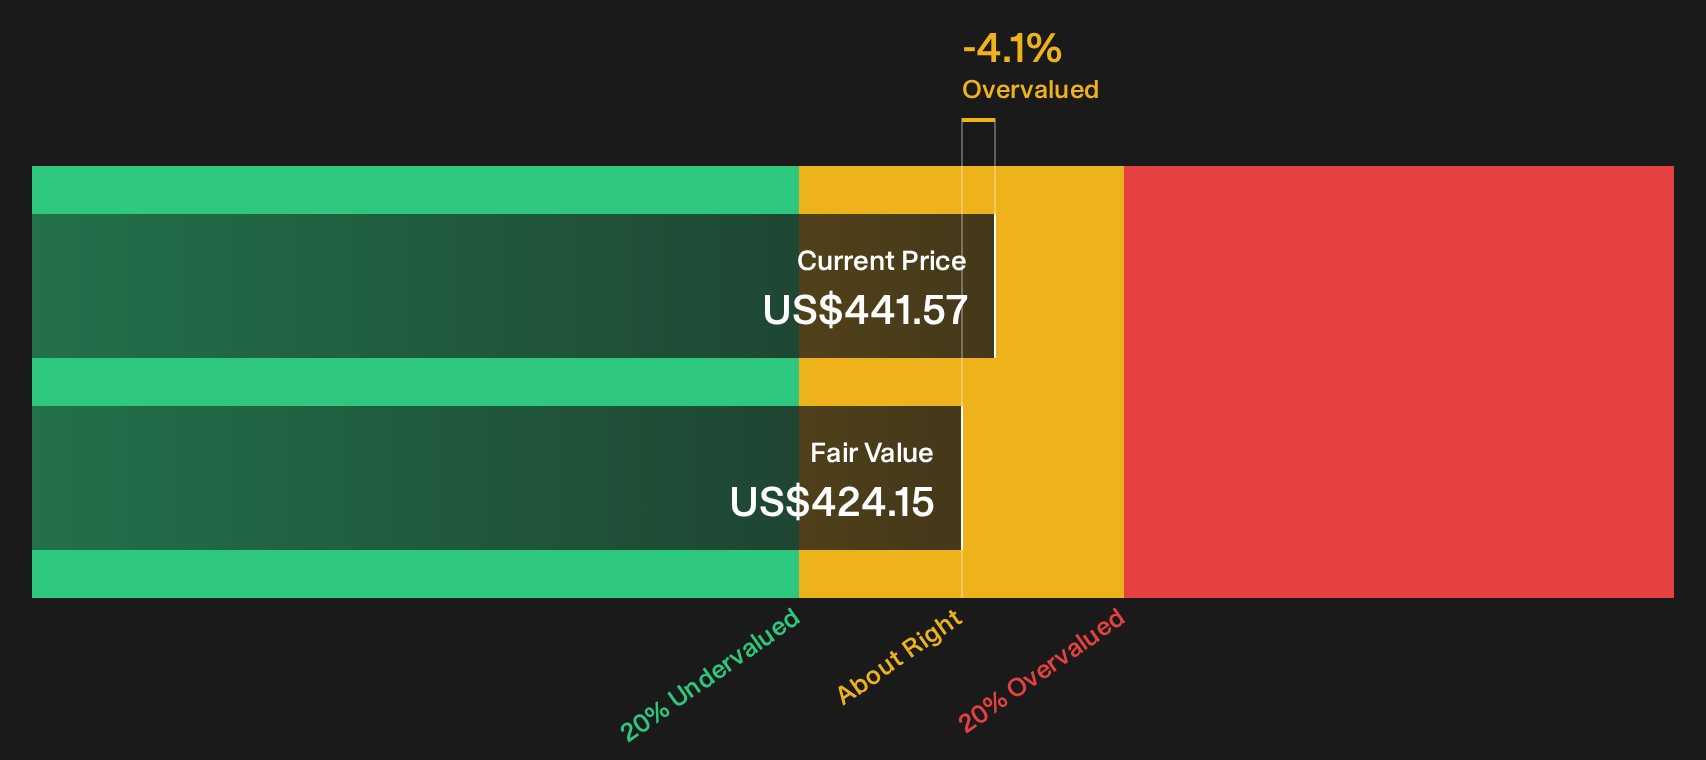
The analyst narrative tags Hubbell as undervalued versus a fair value of $543.46, yet the SWS DCF model points to a future cash flow value of $424.15, below the current $441.57 share price. One approach flags upside, while the other suggests the stock runs slightly rich. Which lens do you trust more for your own hurdle rate?
To understand how this cash flow based view is built step by step, and what would need to change in the assumptions for the signal to flip, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hubbell for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Hubbell's value case can feel confusing, so move quickly past the headline takes and weigh the signals for yourself with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Hubbell?
Hubbell offers one angle on the grid upgrade story, but your portfolio benefits when you line up several quality ideas instead of relying on a single stock.
- Target resilient balance sheets and steadier cash flows by scanning the list of solid balance sheet and fundamentals (25 results).
- Hunt for potential value opportunities that combine quality fundamentals with pricing that still looks reasonable through the 33 high quality undervalued stocks.
- Build a list of potential future leaders before they hit the spotlight by reviewing the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com