
Higher Earnings At Credicorp (BAP) Has Changed Its Investment Story
- Credicorp reported third quarter 2026 net income of PEN 1,929.41 million and nine month net income of PEN 5,974.52 million, both above the prior year levels.
- The higher profit across both the quarter and year to date reflects changes in earnings from Credicorp's underlying banking and financial services operations.
- We will look at how Credicorp's higher third quarter net income influences its investment narrative and longer term earnings profile.
Scan how Credicorp's latest earnings compare with peers by reviewing a curated 33 high quality undervalued stocks that may also be pricing in stronger profitability trends.
Credicorp Investment Narrative Recap
To own Credicorp you need to be comfortable with a Peru centric financial group that is trying to convert digital engagement and financial inclusion into steady fee and lending income. The analyst consensus Narrative on Simply Wall St hinges on Credicorp turning its user base and underpenetrated credit markets into profitable lending while keeping efficiency and cost of risk in line. The latest quarterly net income of PEN 1,929.41 million supports that story but does not radically change it.
The short term catalyst is operational execution in digital services and loan growth, especially with earnings forecast to grow 14.43% a year and revenue expected to increase 13.4% annually. The biggest current pressure point remains risk and concentration. High reliance on Peru, a 4.1% bad loan ratio and exposure to a possible stronger El Niño in 2027 keep credit quality and provisioning firmly in focus.
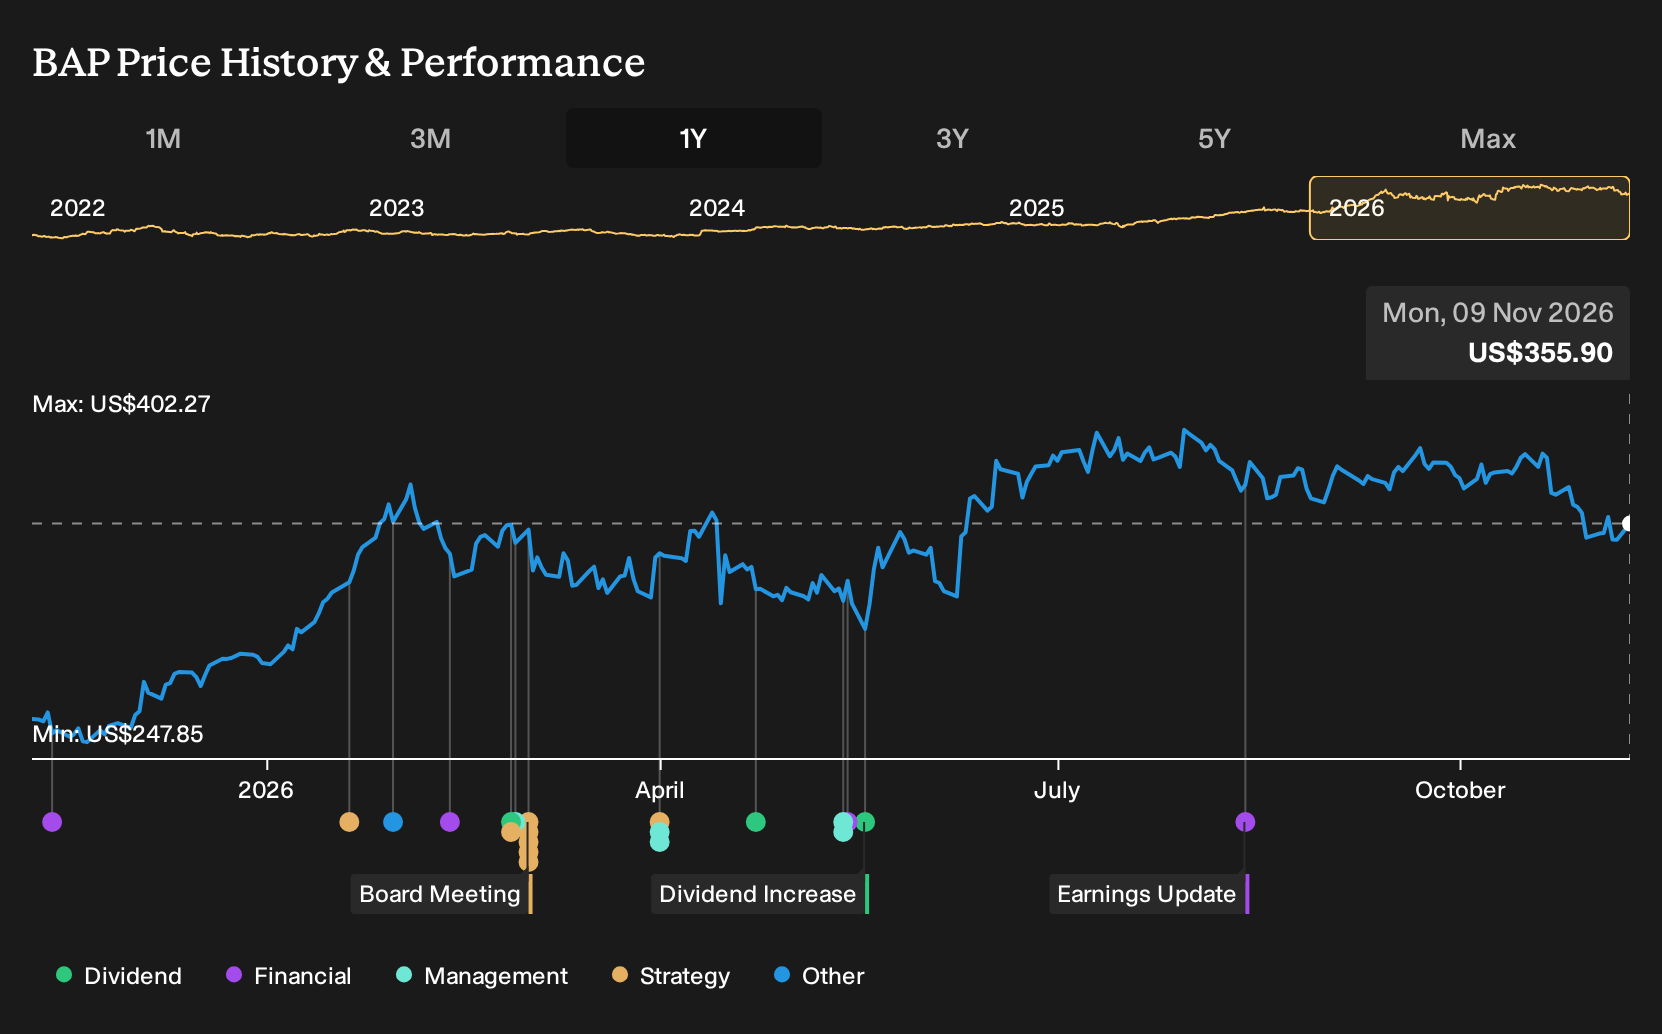
The most relevant announcement is Credicorp’s earnings release for the nine months to September 30, 2026. Net income over that period was PEN 5,974.52 million compared with PEN 5,338.37 million in the prior year period. For you as a shareholder, the key question is whether this profit level is supported by sustainable fee income, disciplined lending and an efficiency ratio that stays within management’s guidance.
These reported figures sit alongside expectations that earnings could reach PEN 11.1b by about October 2029 according to the analyst consensus Narrative on Simply Wall St. That view depends on Credicorp converting its digital platforms, broader regional footprint and capital light businesses into durable returns without letting non performing loans or event risks like El Niño erode margins. Your own thesis needs to weigh that execution opportunity against concentration in Peru, an unstable dividend history and a P/E of 13.1x that is above the wider US Banks industry level of 11.3x.
Credicorp's current narrative points to revenues of PEN 35.0b and earnings of PEN 11.1b by 2029, based on an assumed revenue growth rate of 16.3% a year and an earnings increase of about PEN 3.7b from current earnings of PEN 7.4b.
Discover why Credicorp's fair value suggests a 20% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view leans heavily on Credicorp’s pension withdrawal risk. Those analysts already flagged that the planned eighth withdrawal could trim 2026 loan growth by 0.5 percentage points and Prima’s fees by about 10%. They still projected revenue near PEN 36.4b and earnings around PEN 14.4b by 2029. The key question now is whether the fresh PEN 1,929.41 million quarterly profit meaningfully reshapes that more optimistic script.
Explore 2 other Credicorp fair value estimates, including one that suggests there could be up to 39% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Credicorp research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Credicorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Credicorp's overall financial health at a glance.
Looking for more Credicorp style investment ideas?
If the Credicorp story has sharpened your thinking and you want to cast a wider net, the Simply Wall St Screener can help you quickly spot other stocks that fit the kind of risk and return profile you prefer.
- For investors who want income resilience alongside capital preservation, take a look at companies offering steady payout potential through the 6 dividend fortresses.
- If capital protection and smoother performance matter most to you, filter for businesses with sturdier financial profiles using the 30 resilient stocks with low risk scores.
- When you are hunting for lesser known opportunities with strong underlying numbers, widen your research bench with a curated 19 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com