
Is Watsco (WSO) Undervalued As Earnings Reset Growth Expectations?
How Watsco’s latest earnings reset expectations
Watsco (WSO) just posted third quarter and nine month results that paired higher sales with lower profit, and the mix of weaker Canada revenue and stronger Latin America performance is now under closer investor review.
Investors have reacted quickly to the earnings reset, with Watsco’s share price jumping 3.97% on the day. This built on a 13.05% one-month share price return, even as the year-to-date share price performance remains down 8.90% and the one-year total shareholder return is down 6.56%.
Compare Watsco’s earnings reset with other companies that have been hand picked for resilient fundamentals and cleaner balance sheets using our list of solid balance sheet and fundamentals (25 results).
Watsco’s share price has already bounced on this earnings reset and now trades near analysts’ targets. The live question is whether most of the gain is already in the rearview mirror or if meaningful upside still lies ahead.
Most Popular Narrative: 10% Undervalued
Watsco closed at $316.42, while the analyst consensus Narrative on Simply Wall St points to a fair value near $349.70. The current reset leaves the stock trading at a discount that the Narrative links directly to margin pressure and revised earnings forecasts.
The main thing that has to go right is that Watsco converts its heavy ongoing technology spend and growing e-commerce and OnCall Air usage into sustained gross margin progress toward its stated 30% target while managing OEM pricing and regulatory shifts.
The current valuation implies the market is discounting near term gross margin compression, the earnings miss, and the share price drop more than the narrative here, which holds that Watsco is undervalued and that its technology, market share headroom, and debt free balance sheet still matter for the long run.
See why 15 investors see Watsco as 10% undervalued.
Result: Fair Value of $349.70 (UNDERVALUED)
Still, the narrative can be knocked off course if gross margins remain compressed around the recent 27.5% level or if A2L related pricing frictions persist for longer.
Find out about the key risks to this Watsco narrative.
Another View on Watsco’s Valuation
The first take leans on discounted cash flows to argue Watsco is trading at a 32.9% gap to an estimated future cash flow value of $471.90. A simple P/E check tells a very different story and puts more pricing power in the market’s hands rather than in the model.
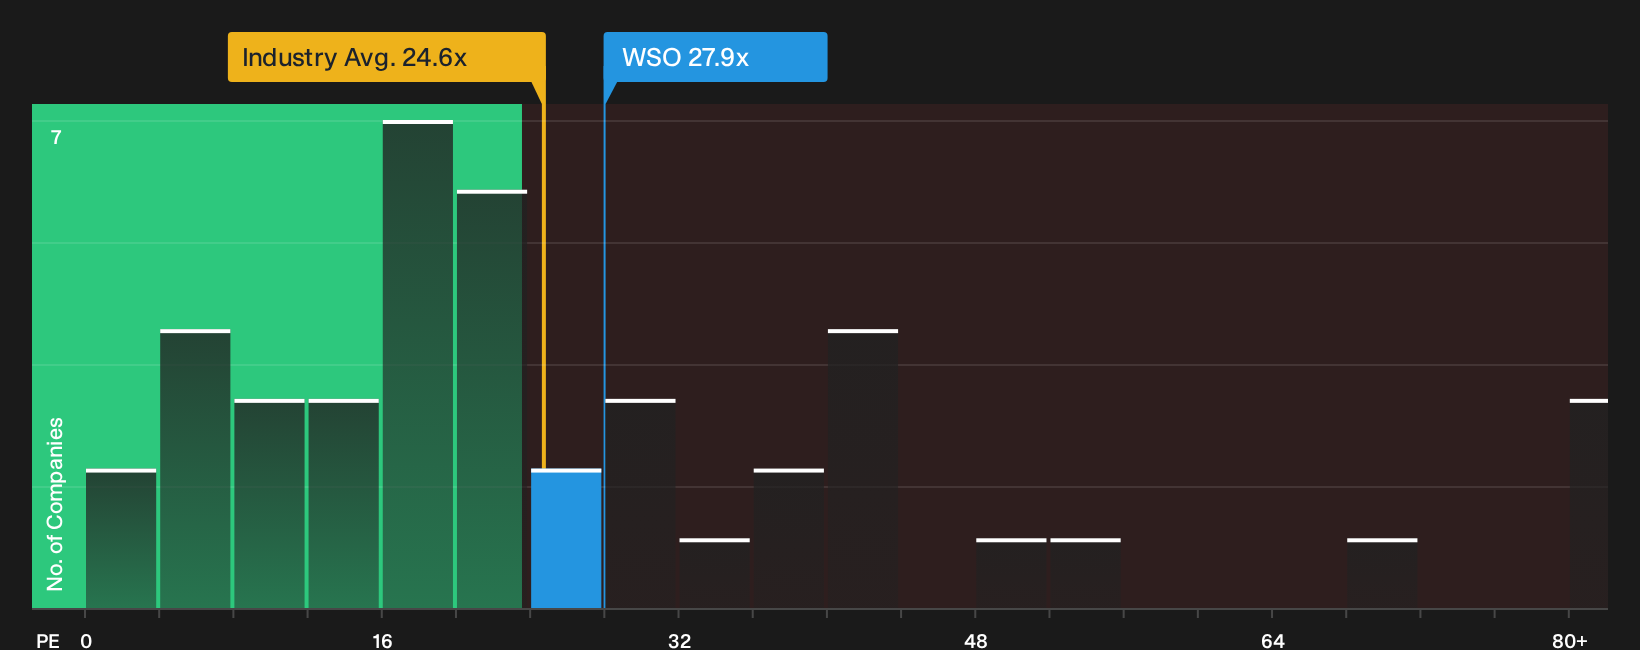
On earnings multiples, Watsco trades on a P/E of 27.9x, which is higher than both the US Trade Distributors industry at 24.6x and the peer average at 23.5x, and also above an estimated fair ratio of 22.8x. That kind of premium points to valuation risk if earnings do not track cleanly with expectations, so the key question is which signal you trust more when the next set of results is released.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like this can leave even experienced investors split on Watsco’s risk reward balance, so it pays to review the same data yourself and move early if you reach conviction. To frame both sides of the argument in one place, start with the 2 key rewards and 1 important warning sign
Looking for more Watsco investment ideas?
If you are weighing what to do next after Watsco’s move, do not stop at one ticker when a wider watchlist could sharpen your decisions.
- Spot potential mispricings early by running your own shortlists through the 33 high quality undervalued stocks and see which businesses the numbers flag as promising.
- Prioritize resilience in tougher periods by focusing on companies with stronger finances using the 30 resilient stocks with low risk scores before headlines start driving prices.
- Hunt for quality that is not already crowded by institutions through the 19 high quality undiscovered gems and give yourself more options than the usual large caps.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com