
Packaging Corporation Of America (PKG) Could Be 4% Undervalued On Price Fixing Probe
News that Packaging Corporation of America (PKG) received a Justice Department subpoena tied to a grand jury probe into possible containerboard price-fixing has pushed legal and regulatory risk to the forefront for current and prospective shareholders.
Against that backdrop, Packaging Corporation of America’s recent trading tells a mixed story. The share price sits at US$254.41 after a 1-day share price return of 1.89% and a 30-day share price return of 10.37%. The 1-year total shareholder return of 29.96% and 5-year total shareholder return of 118.64% indicate that longer term holders have seen significantly stronger results than short term traders.
Contrast the legal overhang at Packaging Corporation of America with a hand-picked group of companies that pair strong finances with resilience using our 30 resilient stocks with low risk scores
Bulls see Packaging Corporation of America as a quality compounder temporarily marked down by legal noise, while bears focus on subpoena risk and recent share swings. Which side does the valuation evidence lean toward next?
Most Popular Narrative: 4% Undervalued
Packaging Corporation of America’s fair value in the analyst consensus Narrative on Simply Wall St sits at $264.56 compared with the last close at $254.41. This suggests a modest valuation gap while legal risk dominates the headlines.
The main factor is that Packaging Corporation of America converts its heavy mill and box plant investment, including the upgraded Greif mills and new Ohio facility, into sustained high uptime, efficient output and solid packaging margins despite cost inflation.
See why 10 investors see Packaging Corporation of America as 4% undervalued.
Result: Fair Value of $264.56 (UNDERVALUED)
Still, Packaging Corporation of America faces real pushback if recycled fiber, freight and energy costs stay elevated, or if containerboard price hikes do not fully stick with customers.
Find out about the key risks to this Packaging Corporation of America narrative.
Another View: Packaging Corporation of America On Earnings Multiples
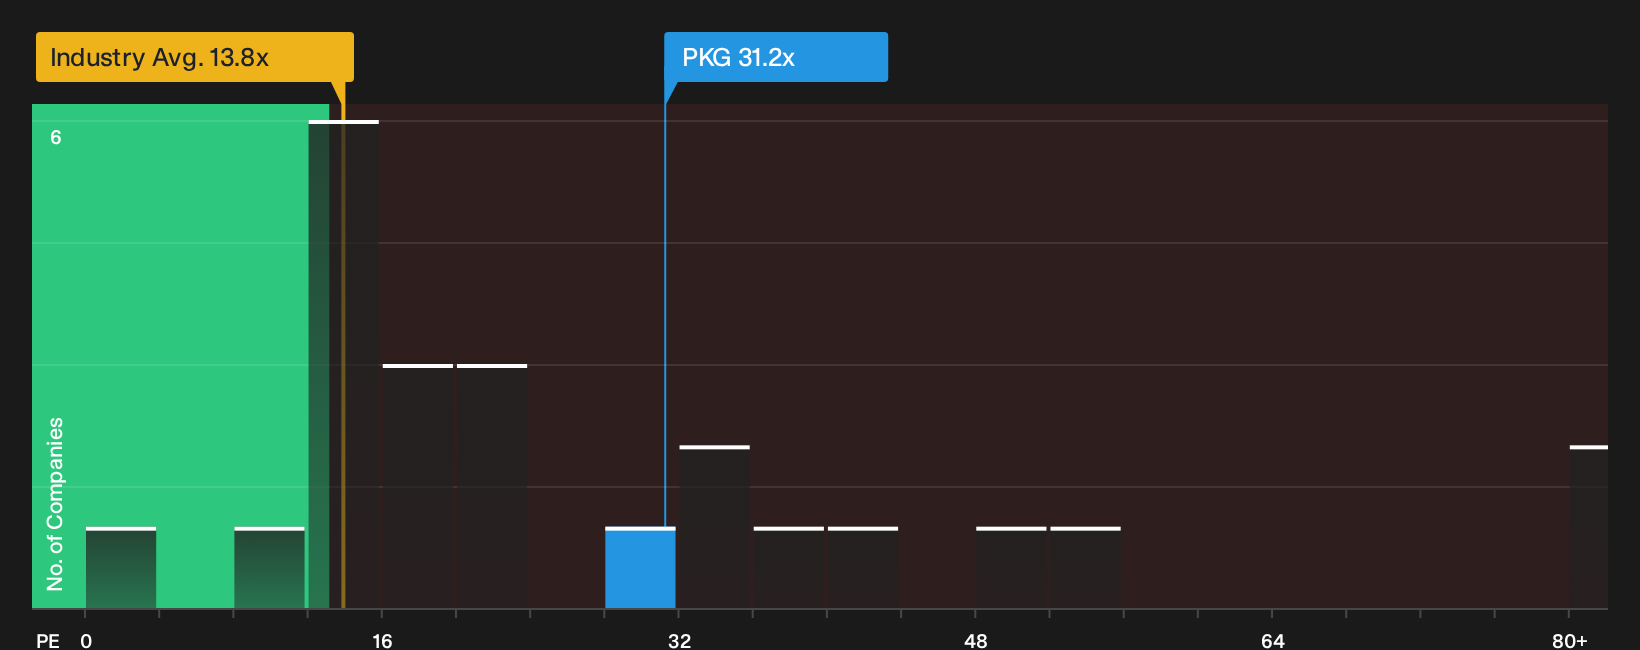
On Simply Wall St’s cash flow model, Packaging Corporation of America screens as good value, trading at $254.41 compared with an estimated future cash flow value of $440.20. That suggests upside based on cash generation. Yet the current 31.2x P/E sits above a 26x fair ratio and well above the 13.7x global packaging average, which raises the question of whether you see a bargain or just richer sentiment getting a long leash.
To see how this earnings multiple gap could close in either direction, and what the numbers imply in practice, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and risk can cut both ways, so consider reviewing the data yourself early and weighing the evidence on Packaging Corporation of America’s legal exposure and potential upside drivers. You can start with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Packaging Corporation of America?
Do not stop your research with one ticker when there are hundreds of other opportunities that could fit your risk profile and income goals.
- Target reliable income streams by reviewing companies in the 6 dividend fortresses and see which payouts might complement your current holdings.
- Hunt for quality at a reasonable entry point by scanning the 33 high quality undervalued stocks that pair solid fundamentals with appealing valuations.
- Prioritise financial strength by focusing on businesses in the list of solid balance sheet and fundamentals (25 results) so temporary shocks are less likely to knock your plan off course.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com