
The Bet BT Group Holders Made
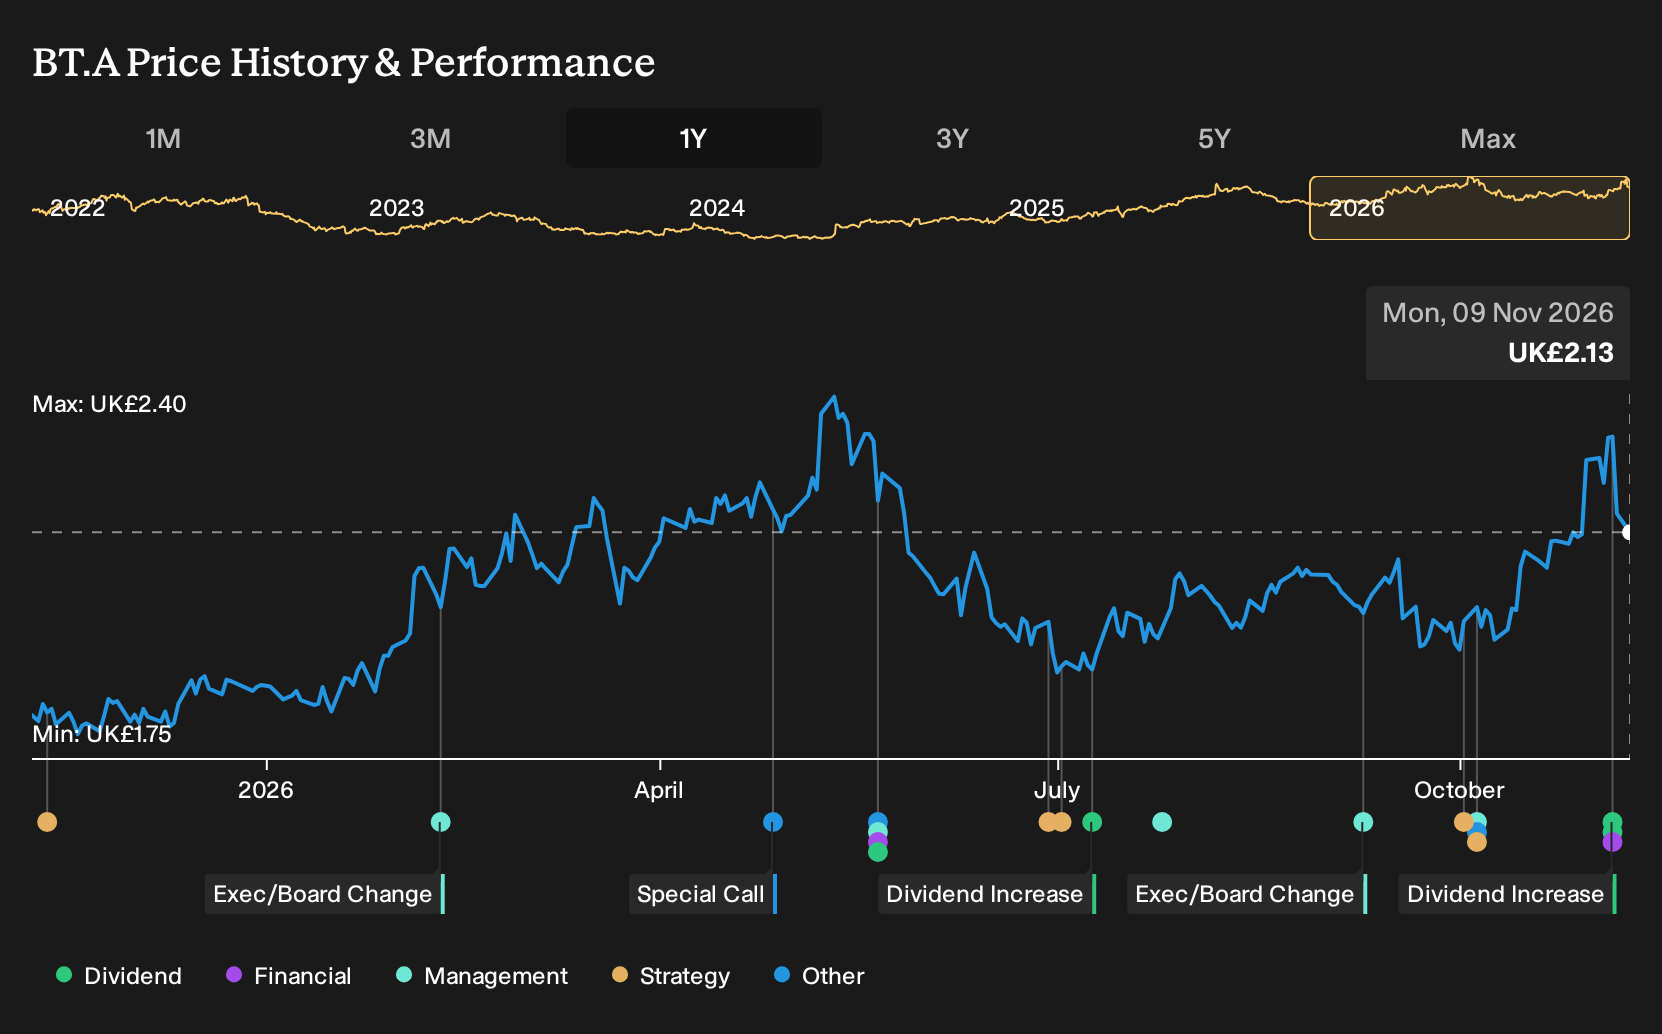
If BT Group was on your watchlist rather than in your portfolio, the recent performance may feel like a missed shot. Investors who held BT Group over the past year are up 25.8%, including dividends. That jump came after analysts were debating whether fibre expansion and margin improvement could offset pressure in fixed-line and Business revenues. If you rewind to late 2025, how could you have judged whether BT’s push into fibre and 5G would outweigh those structural headwinds?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
BT Group has already moved. See which of 16 high quality undervalued stocks still trade below our estimates.
The Two Stories BT Group Investors Had To Weigh
The shares cost £1.79 at the start of the period, and BT Group sat between two very different stories about what might come next.
On the positive side, one Narrative pointed to a Fair Value of £2.1, which was 17% above the start price. It rested on BT Group lifting profit margins to 8.5% over three years while trading on a future P/E of 15.5x.
A more cautious Narrative put Fair Value at £1.3, which was 28% below the start price. That view focused on structural decline in fixed-line revenue and pressure on ARPU as customers shifted toward mobile and wireless-first connectivity.
What The Results Changed For The BT Group Story
The clearest new fact was BT Group’s reported H1 2027 numbers. Revenue was £8,753m and net income was £835m, which was higher than H1 2026, and net margin moved from 8.4% to 9.5%. That margin shift leaned toward the optimistic case that relied on better profitability, while ongoing pressure in fixed-line markets meant the cautious view was not fully overturned.
The practical takeaway is simple. When a thesis hinges on future margin strength, as BT Group’s did, track the reported net margin and profit trend in each set of results and check whether they actually move toward the forecast level.
What BT Group's Price Already Assumes
BT Group now trades at £2.13, after a 25.8% gain over the past year. The bearish analyst Narrative on Simply Wall St sets its Fair Value below that level, based on concerns about how long fixed-line and legacy voice erosion might weigh on reported revenue.
That Narrative argues the key question is whether cost savings, network migration and fibre build can sustain earnings and cash generation. Anyone paying today’s price is effectively backing that cash flow story, so the open question is how its revenue and margin assumptions test that belief.
"The main factor that needs to work in BT Group’s favor is successful delivery of its extended cost transformation and network migration program, so that large planned cost savings and efficiency gains translate into resilient earnings and cash generation. The current valuation suggests the market is already accounting for successful fiber rollout, cash flow growth and ongoing dividend increases, which may leave limited room for disappointment in BT Group’s share price."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
How Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 33% below our estimate - manages renewable-heavy infrastructure portfolios for institutions seeking direct exposure to real assets.
- Company 2 - 25% below our estimate - sells testing and compliance tools that automate complex workflows for enterprise resource planning users.
- Company 3 - 30% below our estimate - builds low-cost investing platforms that advisers and retail savers use to consolidate portfolios digitally.
That is three of the list. See every one of the 9 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com