
Is Peloton Interactive (PTON) Reasonably Valued After Its Earnings Rebound?
Peloton Interactive has seen its share price move around sharply in recent years, which puts a spotlight on whether today’s market value lines up with what the business earns. With the focus now on its earnings power rather than hype, the question is how much of the recent story is already reflected in the stock.
- Over the past 5 years the share price has dropped 87.5%, which makes the current valuation debate largely about whether the remaining equity value is well supported by the company’s earnings profile.
- Recent news about revenue growth, product launches and debt reduction can influence how investors think about future profitability and the timing of cash generation, which all feed directly into what Peloton’s earnings may reasonably support.
- There is a second opinion on Peloton Interactive worth weighing. See what analysts think Peloton Interactive's shares could be worth.
The issue now is whether Peloton’s current share price is justified by its earnings when set against a Fair Ratio benchmark.
To pressure test Peloton Interactive’s recent earnings story, it can help to line it up against other companies, starting with a curated list such as 33 high quality undervalued stocks.
Does Peloton Interactive Look Fairly Valued on Earnings?
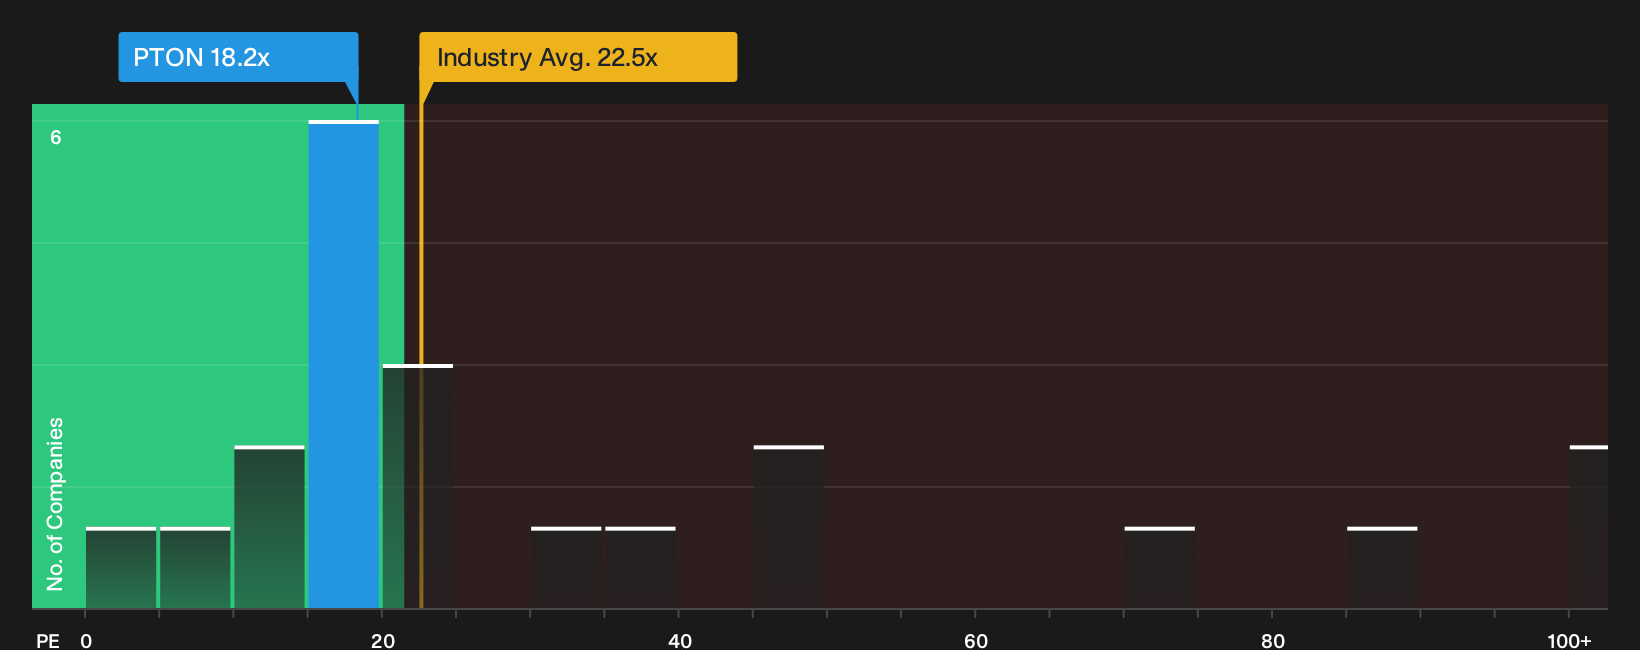
P/E is usually the cleanest way to compare Peloton Interactive with other Leisure stocks that already report positive earnings. On this measure, Peloton trades on about 18.2x earnings, which is very close to both the Leisure industry average of 16.9x and the peer group on roughly 18.6x.
Because recent Q1 FY2027 results featured solid earnings per share and upbeat guidance, this kind of middle-of-the-pack P/E suggests the market is already giving the business some credit for that progress but not pushing it into a premium tier. The current multiple sits near the Fair Ratio level implied by Peloton’s own growth outlook, margins, scale and risk profile, so valuation on earnings looks broadly in line with what a tailored model would flag. For a deeper read on how that benchmark is built and how big the gap might be, follow through to the full multiple breakdown. Explore the numbers behind Peloton Interactive's P/E valuation.
The Peloton Interactive Narrative: What Would Justify Today's Price?
Peloton Interactive’s valuation puzzle only really comes into focus once you see the Narratives on Simply Wall St’s Community page, which spell out what would need to happen to future growth, profitability and earnings for the stock to trade meaningfully higher or lower than it does today. Where a single multiple or model output gives one clean number, these scenarios unpack the future path that number relies on so you can watch how the real world lines up with it over time.
Peloton Interactive now splits opinion between analysts who see connected wellness and AI as underappreciated, and others who think subscription strain still weighs too heavily.
Bull case: 24% undervalued
The analyst consensus Narrative on Simply Wall St argues Peloton’s connected wellness and AI push could make the current price look too low.
"The main thing that has to go right is that Peloton turns its early connected wellness and AI traction, its commercial and Spotify reach, and its more accessible hardware and micro stores into stable or rising memberships and durable subscription economics…"
Discover why this Narrative puts Peloton Interactive at 24% undervalued.
Bear case: 35% overvalued
The bearish analyst Narrative on Simply Wall St stresses that pressure on Connected Fitness subscriptions could leave Peloton investors paying too much today.
"Bearish analysts expect Peloton Interactive to see its Connected Fitness subscription base and revenue weighed down by higher churn, guidance for lower paid subscriptions, and weaker gross subscriber additions relative to past peaks…"
Explore why this Narrative puts Peloton Interactive at 35% overvalued.
Before focusing on Peloton Interactive’s valuation alone, there is one more factor to weigh
Peloton Interactive’s numbers tell only part of the story, since our broader checks have highlighted specific risks that could change how you judge the whole setup. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com