
Ameresco (AMRC) Could Be 47% Undervalued On Its Latest Earnings Numbers
Ameresco (AMRC) just put fresh numbers on the table, reporting third quarter 2026 earnings that combined higher sales with sharply lower profit and set the tone for how investors parse the stock now.
Ameresco's recent earnings surprise and record backlog have not reversed a tougher share price story. The stock is up 3.89% on the day and 7.11% over the past week but remains down 26.80% on a year to date share price basis, delivering a 1 year total shareholder return decline of 37.48%. This suggests that recent momentum is improving from a low base while longer term holders remain deeply underwater.
Spot opportunities that rhyme with Ameresco's rebound attempt by scanning a curated set of 42 power grid technology and infrastructure stocks tied to the same energy transition and infrastructure themes driving interest today.Bulls point to Ameresco's record backlog and recent earnings surprise. Bears focus on compressed profit and a long slide in total returns. Which side does the valuation math lean toward next?
Most Popular Narrative: 47% Undervalued
Ameresco closed at $22.45, while the analyst consensus Narrative on Simply Wall St anchors fair value at $42.70 using a 12.54% discount rate. This creates a wide gap that the backlog and earnings assumptions need to justify.
Analysts expect earnings to reach $148.8 million (and earnings per share of $2.74) by about October 2029, up from $28.2 million today. However, there is some disagreement amongst the analysts with the more bullish ones expecting earnings as high as $184.2 million.
See why 7 investors see Ameresco as 47% undervalued.
On this view, the market price is treating Ameresco as if execution, funding and timing risks will bite harder than the analyst model assumes. The Narrative leans on a record US$6.7b project backlog, an expanding US$1.5b long term O&M base and an earnings trajectory that would lift margins from the current 1.4% level to 5.2% in three years, then support a P/E of 22.0x on those 2029 profits.
For you, the key test is how comfortable you are with those inputs. That includes forecast revenue of $2.9b by 2029, earnings growth that would take net income from $28.2m to $148.8m, and a required return of 12.5% to discount all of that back to today. The more confident you are that Ameresco converts its backlog, manages leverage and avoids heavy dilution, the closer your own estimate may sit to the $42.70 fair value implied here.
Result: Fair Value of $42.70 (UNDERVALUED)
Still, Ameresco’s story can break if long project timelines keep pushing cash flow further out, or if funding needs force equity issuance that dilutes shareholders.
Find out about the key risks to this Ameresco narrative.
Another View: Ameresco Looks Expensive On Earnings Today
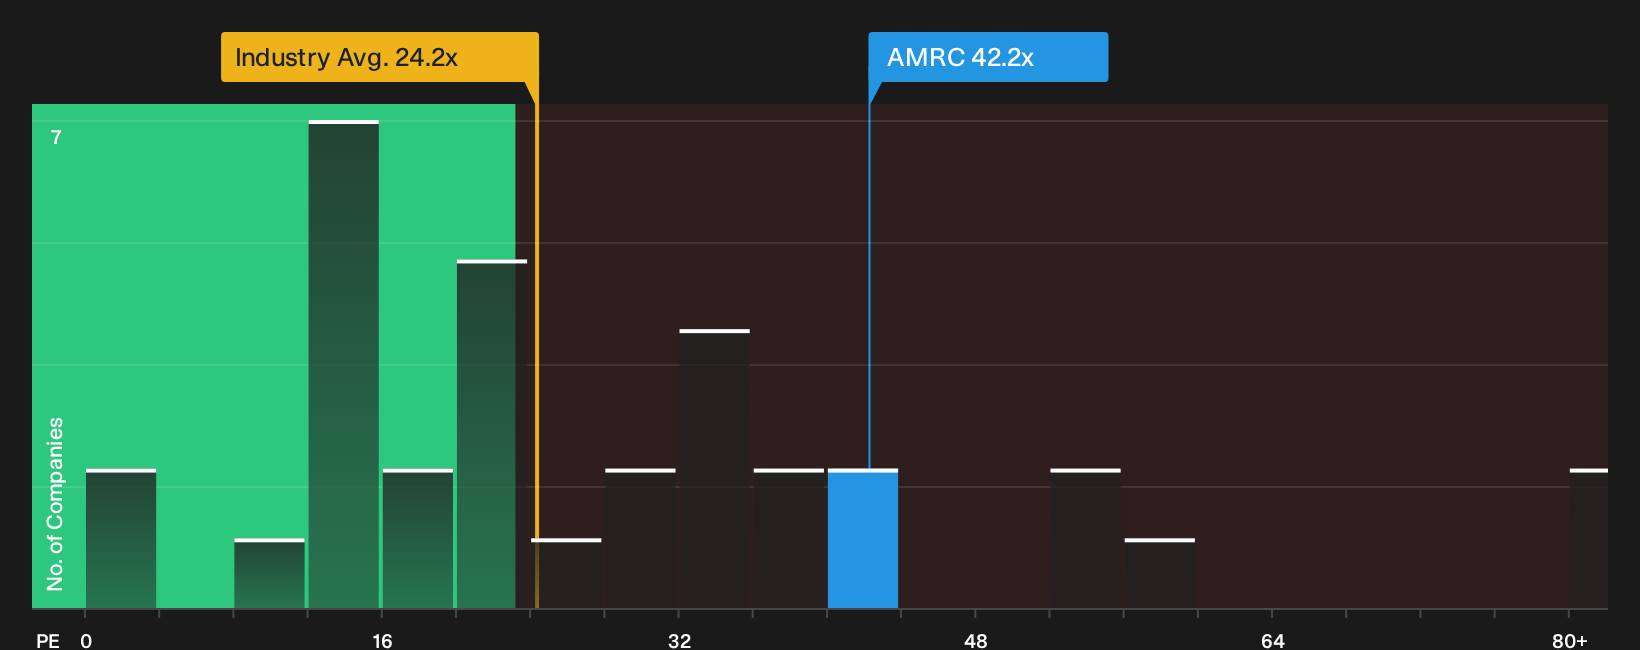
Our DCF work points to upside for Ameresco, yet the plain P/E snapshot sends a colder message. The stock trades on 42.2x earnings compared with a 23x average for the US Construction industry and 29.9x for peers, and even above a 34.6x fair ratio that the market could eventually drift toward. That premium can reward patience if analyst forecasts land close to plan, or it can amplify disappointment if profitability stumbles again. The key question is which signal you trust more right now.
For a closer view of how this earnings based check fits alongside backlog, cash flow assumptions and debt, have a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Ameresco is split, with both real concerns and real upside on the table. Move quickly, review the underlying data, and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ameresco?
If Ameresco's setup has you thinking harder about risk, reward and timing, use that momentum to widen your watchlist with focused screeners that surface clear themes.
- Target resilient cash generators with stronger downside protection by scanning a 30 resilient stocks with low risk scores that filters for sturdy balance sheets and more stable track records.
- Hunt for potential bargains by reviewing a curated 33 high quality undervalued stocks that pairs solid fundamentals with prices that still look conservative.
- Stack your income goals by checking a focused 6 dividend fortresses that highlights higher-yielding payouts supported by financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com