
CNH Industrial (CNH) Faces A Fresh Test On Earnings And Joint Venture Valuation
CNH Industrial (NYSE:CNH) just put out third quarter numbers and a major construction equipment joint venture update, giving investors fresh data on profitability, cash generation, and the future shape of the business.
The sharp 10.9% one-day share price return to US$12.82 and 37.11% year-to-date share price return suggest momentum is picking up as investors react to CNH Industrial's joint venture plan and recent earnings update, even though the 5-year total shareholder return is still down 11.19%.
Scan how CNH Industrial's joint venture pivot compares with other machinery and capital goods stocks showing strong financials by checking the hand-picked list of solid balance sheet and fundamentals (25 results) in this space.
After a sharp move in CNH Industrial’s share price and only a modest discount to both intrinsic value estimates and analyst targets, the real tension is whether that caution reflects earnings reality or leaves mispriced upside on the table.
Most Popular Narrative: 10% Undervalued
On Simply Wall St, the analyst consensus Narrative puts CNH Industrial's fair value at $14.25 per share, a touch above the recent $12.82 close. This frames the stock as modestly undervalued based on long term revenue and earnings forecasts.
The integration of advanced connectivity and precision technologies such as the FieldOps platform and AI enabled tools continues to position CNH Industrial to draw more recurring, higher margin revenue from software, data and tech based services, which can support net margins and earnings.
See why 21 investors see CNH Industrial as 10% undervalued.
Result: Fair Value of $14.25 (UNDERVALUED)
Still, CNH Industrial faces pressure from tariffs that weigh on margins and elevated credit risk in South America, which could affect Financial Services earnings.
Find out about the key risks to this CNH Industrial narrative.
Another View: CNH Industrial Looks Expensive On Earnings
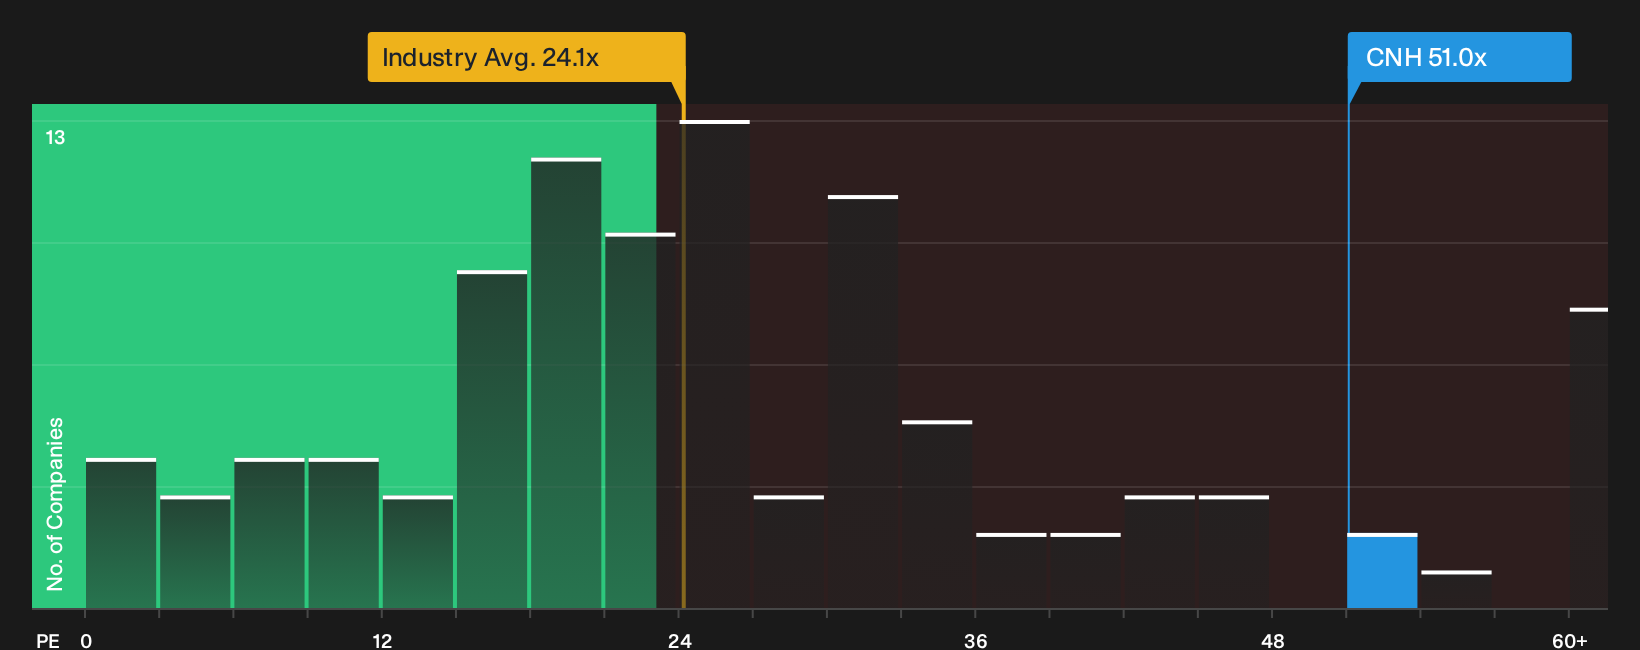
On future cash flows, CNH Industrial screens as only 1.3% below the Simply Wall St fair value estimate, which points to a fairly tight gap. On current earnings though, the picture flips. The stock trades on a P/E of 51x compared with a fair ratio of 36.8x and a US Machinery sector average of 23.2x, which pushes a lot more valuation risk onto execution. The question is whether you treat that premium as justified optimism or a margin of error you are not paid for.
For a closer look at how those earnings based signals stack up against other methods, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed messages around CNH Industrial leave you unsure, move quickly from headline impressions to hard numbers and stress test your own thesis. Start by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CNH Industrial?
Do not park capital in one story when the wider market offers fresh angles. Diversify your watchlist with a few data backed shortlists.
- Target resilient balance sheets and cleaner fundamentals by scanning the list of solid balance sheet and fundamentals (25 results), which filters for financial strength you can actually quantify.
- Hunt for quality at a marked discount by reviewing the 33 high quality undervalued stocks, which surfaces companies combining robust cash flows with compressed valuations.
- Prioritise income and staying power by checking out the 6 dividend fortresses, which focuses on higher yielding businesses with the potential to support regular payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com