
How Investors May Respond To Chemours (CC) Earnings Miss And Lawsuit Risk
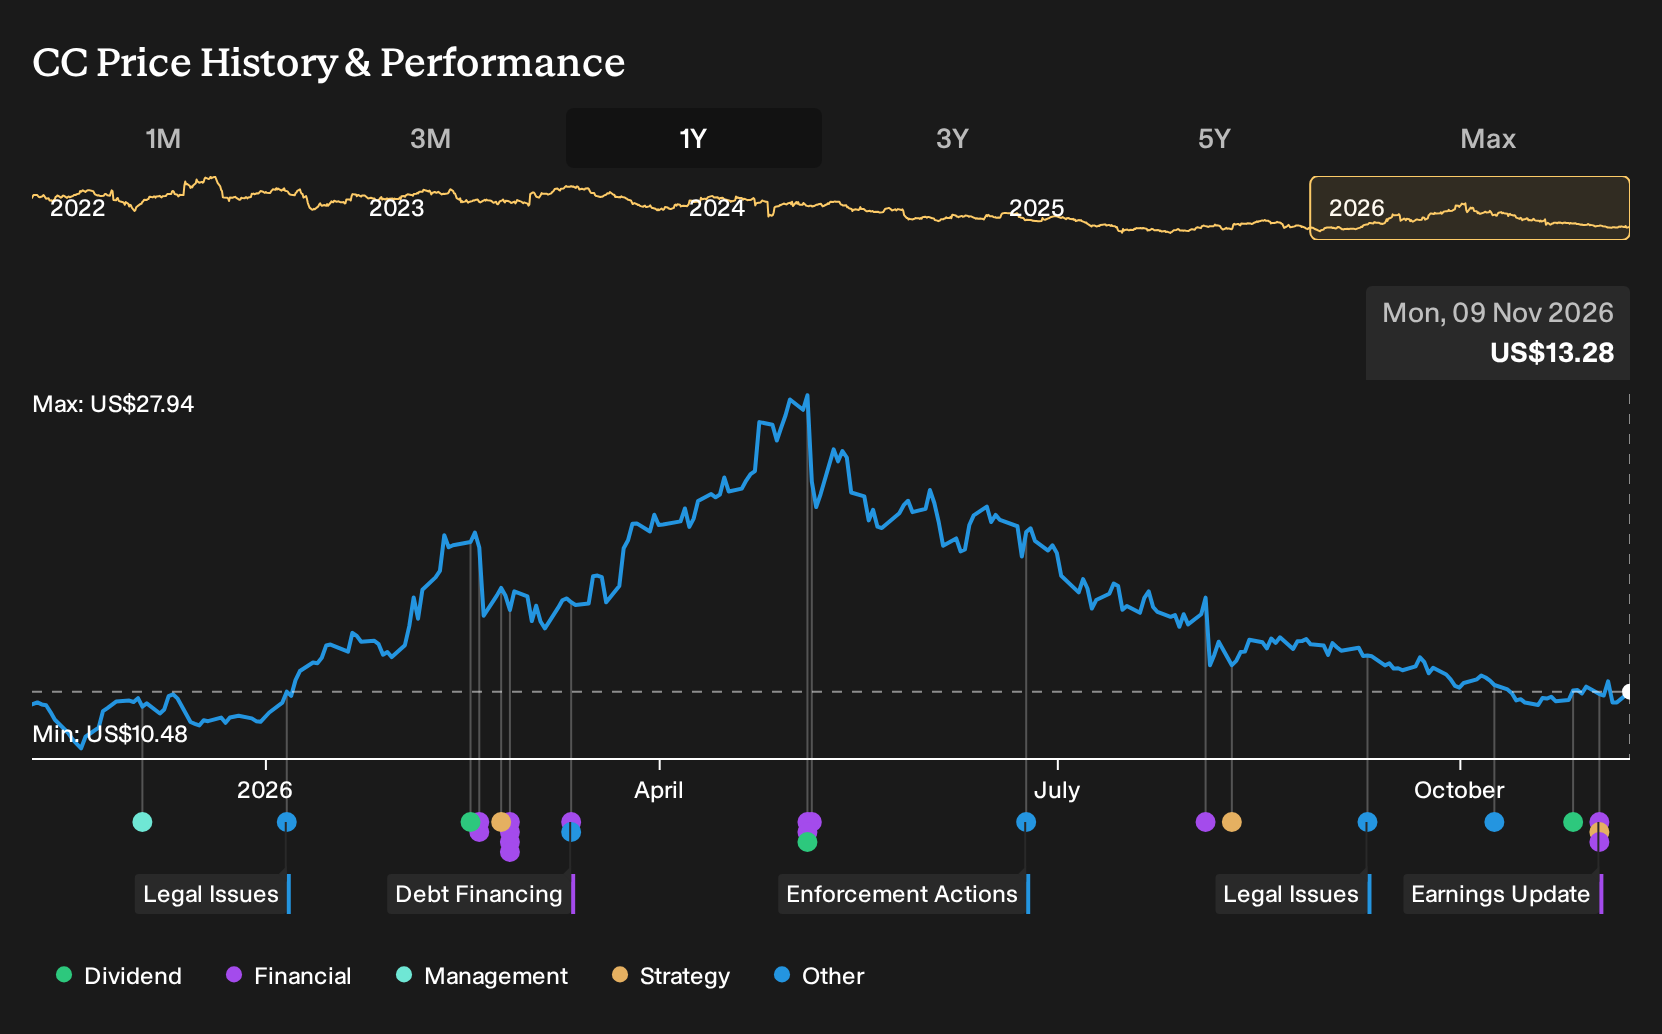
- Chemours recently reported third quarter 2026 results showing US$1,540 million in sales and US$196 million in net income, issued guidance for softer fourth quarter sales, and confirmed a US$0.0875 quarterly dividend payable on December 15, 2026.
- The launch of Faizeon two phase liquid cooling fluids for AI and high density data centers adds a new thermal management portfolio. This sits alongside Chemours' existing refrigerant and titanium dioxide businesses at a time when a class action lawsuit is challenging past guidance reliability.
- The focus now turns to Chemours' broader investment narrative and how it incorporates weaker Thermal & Specialized Solutions guidance within that story.
Compare Chemours' mix of AI cooling exposure, litigation risk, and low P/S with a curated set of other potential value ideas in our 33 high quality undervalued stocks list.
Chemours Investment Narrative Recap
To own Chemours, you need to be comfortable with a chemicals group that is trying to shift more of its mix toward higher value thermal management and advanced materials while still dealing with cyclical TiO2 and refrigerants. The analyst consensus narrative on Simply Wall St leans on that mix shift. The fresh fourth quarter guidance for a 5% to 10% sales decline keeps near term pressure on Thermal & Specialized Solutions, as channel destocking and softer volumes run through.
The biggest near term swing factor is whether refrigerant and broader TSS demand stabilize enough to support the earnings targets embedded in the Pathway to Thrive program. The key risk remains on the legal and balance sheet side. PFAS related exposure, the class action around prior Opteon commentary, and interest costs that are not well covered by earnings could all absorb more cash if outcomes are worse than expected.
The Faizeon launch is the announcement that ties most directly to the current Chemours story. These two phase liquid cooling fluids plug straight into AI, high performance computing, and dense data centers, where the need to pull heat out of racks touches system design and power costs. Independent testing detail, such as GPUs running up to 19 degrees Celsius cooler at lower flow rates with Faizeon 200, gives investors a concrete operational proof point rather than just a marketing claim.
For catalysts, Faizeon sits beside existing low global warming potential refrigerants as another way to lean into thermal management demand. It also links into the earlier narrative about Performance Solutions exposure to semiconductors, data centers, and advanced electronics. The opportunity is clear, but execution risk is real while Chemours is under litigation scrutiny and while TSS volumes are under strain, so the speed and profitability of any Faizeon ramp will be closely watched.
Chemours' current loss of US$304.0 million is projected to shift to earnings of US$268.4 million by 2029. This implies an earnings improvement of about US$572 million, alongside analyst assumptions for 4.3% yearly revenue growth and revenues of US$6.6 billion in that same year.
Uncover why Chemours' fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate take on Chemours leans hard into Faizeon and AI cooling as the real swing factor. Those bullish analysts were modeling about US$7.1b of revenue and US$1.7b of earnings by 2029, far above consensus. Since those forecasts pre date the latest guidance and launch news, treat them as one lens among several and compare multiple viewpoints before deciding how you feel about the story.
Explore 4 other Chemours fair value estimates, including one that suggests as much as 89% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Chemours research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Chemours. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Chemours' overall financial health at a glance.
Looking For More Ideas Beyond Chemours?
If Chemours has sharpened your thinking about risk, balance sheets, and upside potential, use that same lens on a wider watchlist. The Simply Wall St Screener gives you ready made starting points so you spend more time weighing trade offs and less time trawling tickers.
- If you care most about quality at a reasonable P/S or P/E, start with a focused group of potential bargains in the 33 high quality undervalued stocks that pair stronger fundamentals with compressed expectations.
- For readers who want balance sheet resilience front and center, scan the list of solid balance sheet and fundamentals (25 results) and filter for businesses with financial structures that better align with your risk comfort.
- When you prefer resilience and sleep at night potential over drama, sift through the 30 resilient stocks with low risk scores to see which stocks currently screen with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com