
Hokuhoku Financial Group (TSE:8377) Could Be 25% Undervalued After Lifting Earnings And Dividends
Dividend and earnings revisions put Hokuhoku Financial Group in focus
Hokuhoku Financial Group (TSE:8377) has raised both its interim and full year earnings forecasts, alongside higher interim and year end dividend guidance, after firmer deposits, loans, and funds related income.
Recent price action shows that Hokuhoku Financial Group’s share price has pulled back, with a 1 month share price return of down 14.8% and a 3 month move of down 9.7%. However, the year to date share price return of 47.1% and a 1 year total shareholder return of 72.7% indicate that longer term momentum remains strong. Recent guidance and dividend revisions are being weighed against an already very large 5 year total shareholder return of almost 9x for existing investors.
Spot 35 dividend fortresses that, like Hokuhoku Financial Group, pair updated payout guidance with robust recent shareholder returns.After a near 9x five year total return and a sharp pullback in recent weeks, the key tension around Hokuhoku Financial Group is simple. Is the meaningful rerating already done, or does the upgraded guidance still leave room in the valuation?
Preferred Price-to-Earnings of 12.2x: Is it justified?
Valuation for Hokuhoku Financial Group currently leans on earnings rather than cash flows, with the stock trading on a P/E of 12.2x that sits slightly below both the wider JP market on 12.6x and the JP Banks industry on 12.5x.
The P/E ratio compares the share price to earnings per share and, for a bank like Hokuhoku Financial Group, it gives a quick read on how the market is weighing profitability against perceived risk. A lower multiple than peers often suggests investors are either cautious about how durable current profits are or have not fully priced in recent progress.
Earnings growth has been strong, with profit up 49% over the past year and an average increase of 27.8% per year across five years. Forecasts point to earnings expanding by about 14.97% a year, ahead of the broader JP market expectation of 9.2%. In that context, the current 12.2x P/E compares with an estimated fair P/E of 15.3x, so the market is valuing Hokuhoku Financial Group at a discount to where that fair ratio could move if the earnings profile and perceived quality persist.
On a pure comparison basis, the stock trades at what appears to be good value versus both direct peers and the domestic banking sector averages. The gap to the fair P/E suggests investors are assigning a more cautious multiple than the earnings track record and forecasts might otherwise indicate.
Explore the SWS fair ratio for Hokuhoku Financial Group.
Result: Price-to-Earnings of 12.2x (UNDERVALUED)
Still, Hokuhoku Financial Group faces very real risks if loan quality weakens or if higher payout expectations prove hard to sustain given future profit trends.
Find out about the key risks to this Hokuhoku Financial Group narrative.
Another view on Hokuhoku Financial Group’s valuation
The story looks different when using the SWS DCF model. On this approach, Hokuhoku Financial Group’s current share price of ¥702.4 sits above an estimated future cash flow value of ¥527.63, which frames the stock as overvalued on cash flows even while the earnings multiple suggests room left.
For investors weighing which signal matters more right now, understanding how that cash flow view is built can help sharpen conviction on either side of the trade. Look into how the SWS DCF model arrives at its fair value.
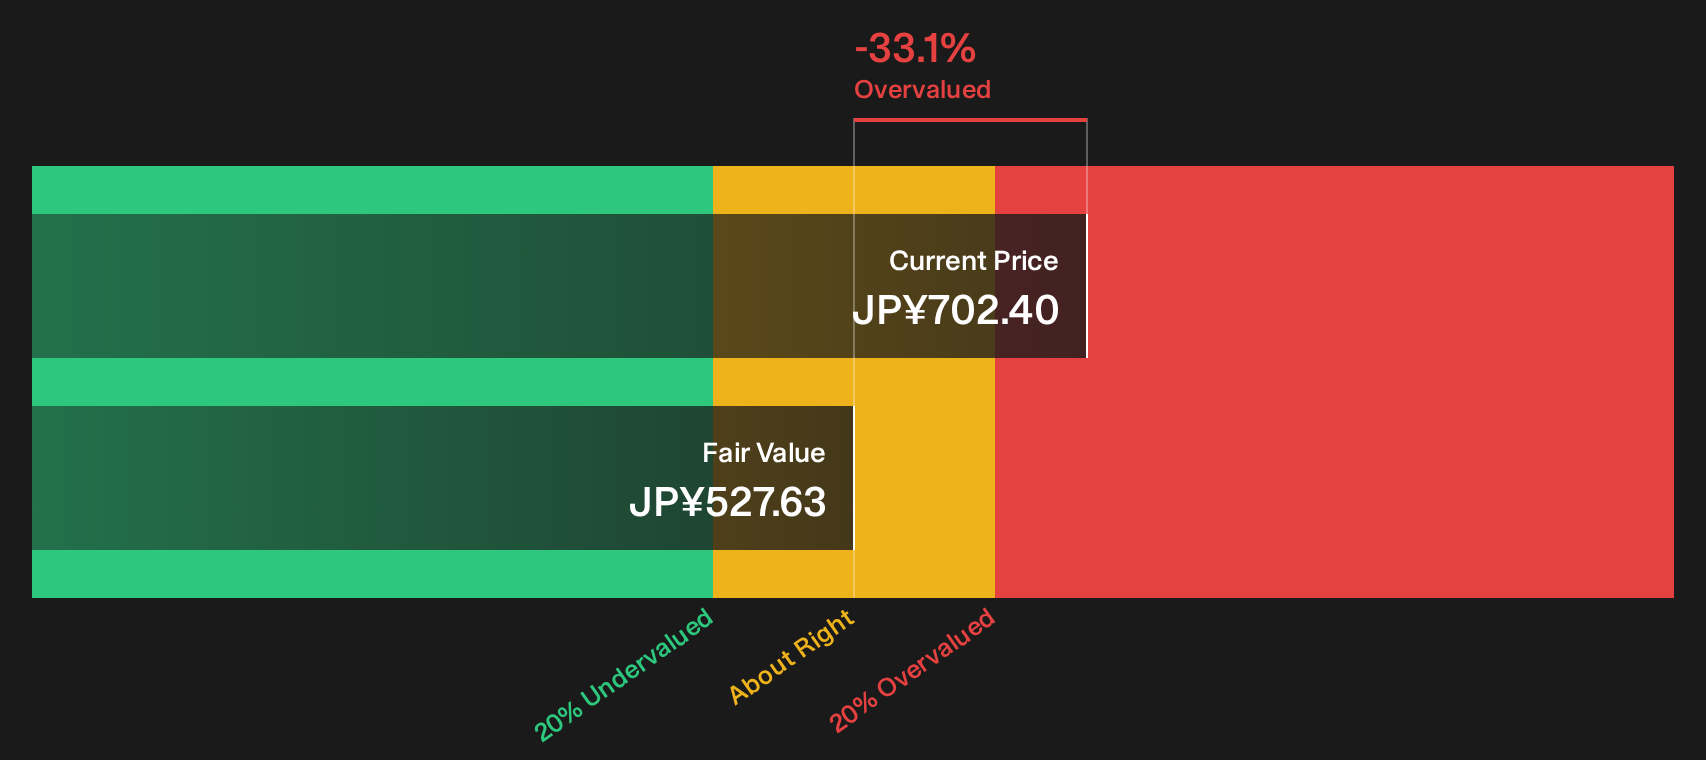
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hokuhoku Financial Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 22 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Hokuhoku Financial Group’s valuation and guidance can feel messy, so move quickly, review the numbers carefully, and form your own view using the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hokuhoku Financial Group?
If Hokuhoku Financial Group has sharpened your focus on valuation and income, it may be worth widening the lens and lining up a few fresh candidates.
- Target reliable cash generators by reviewing companies with strong balance sheets and fundamentals using the list of solid balance sheet and fundamentals (23 results).
- Hunt for potential mispriced opportunities and compare Hokuhoku Financial Group with 22 high quality undervalued stocks that combine quality metrics with marked-down valuations.
- Strengthen your income watchlist by scanning 35 dividend fortresses built around higher yields supported by solid financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com