
Custom Truck One Source (CTOS) Could Be 24% Undervalued As Earnings Turn Positive
Custom Truck One Source earnings shift draws investor focus
Custom Truck One Source (CTOS) returned to profitability in the third quarter of 2026, as fresh earnings results and new full-year revenue guidance put the stock firmly on investors’ radar.
That earnings swing has arrived after a sharp run in the Custom Truck One Source share price, with a year-to-date share price return of 72.76% and a 1-year total shareholder return of 70.12%. However, the 90-day share price return declined 5.83%, suggesting recent momentum has cooled after a strong multi-year total shareholder return of 106.17%.
Capitalize on Custom Truck One Source’s profitability turn by scanning a hand picked set of 33 high quality undervalued stocks that also pair earnings momentum with balance sheet strength.Custom Truck One Source has swung back to profit and the share price has already run hard. The real tension now is whether that improving business is still on offer at a reasonable valuation.
Most Popular Narrative: 24% Undervalued
On the analyst consensus Narrative on Simply Wall St, Custom Truck One Source screens as undervalued, with a fair value of $13.17 versus the last close at $10.02. The gap is tied directly to rental demand and project visibility rather than sentiment alone.
Early stage transmission and distribution project visibility out to 2027 and 2028, combined with record rental utilization and strong OEC on rent tied to grid work, supports the idea that Custom Truck One Source could see sustained rental revenue growth and healthier adjusted EBITDA margins for longer than the current P/E multiple implies.
See why 4 investors see Custom Truck One Source as 24% undervalued.
Result: Fair Value of $13.17 (UNDERVALUED)
Still, the Custom Truck One Source story can be knocked off course if heavy rental fleet spending keeps absorbing cash, or if high P/E expectations fade without cleaner margins.
Find out about the key risks to this Custom Truck One Source narrative.
Another View: Custom Truck One Source through the earnings multiple lens
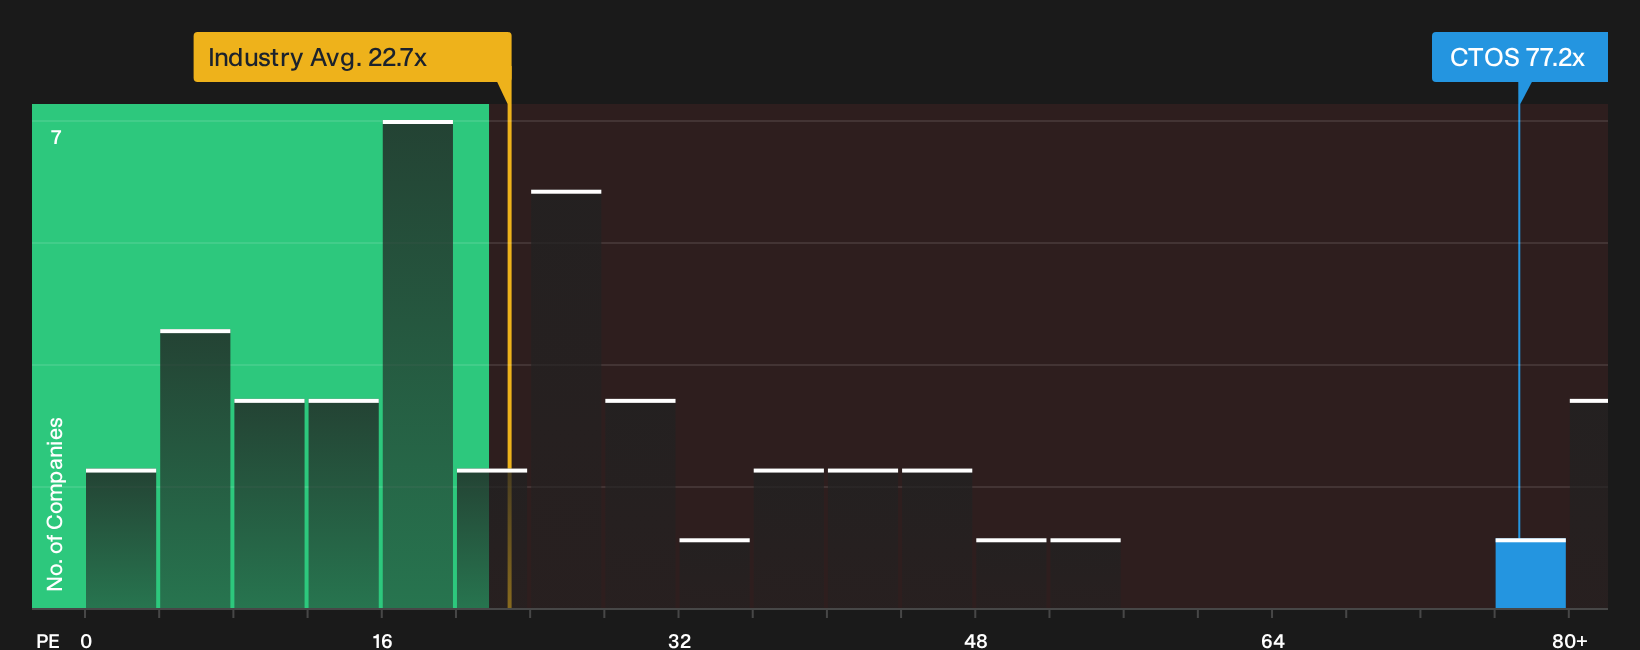
The first take presents Custom Truck One Source as undervalued against a $13.17 fair value, yet the P/E story points in the opposite direction. At roughly 77.2x earnings versus a US Trade Distributors average of 22.7x and a fair ratio of 36.1x, investors are paying a heavy premium. That gap can reward if forecasts are met precisely, but it also leaves far less room for error. Which signal appears more compelling at this point: the earnings multiple or the narrative fair value?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Custom Truck One Source can pull you in both directions, so act while the data is fresh and decide where you land by weighing 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Custom Truck One Source?
Do not stop at Custom Truck One Source. Broaden your watchlist with focused stock ideas that connect your view on value, balance sheet strength, and risk control.
- Target potential bargains by scanning a curated pool of 33 high quality undervalued stocks that combine quality fundamentals with pricing that has not fully reflected them yet.
- Strengthen your downside protection by filtering for a list of solid balance sheet and fundamentals (25 results) so you focus on companies built to handle tougher conditions.
- Calm your portfolio swings by zeroing in on 30 resilient stocks with low risk scores that score well on financial resilience and business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com