
Invesco Stock What Changed After Earnings And New AI Advisor Tools
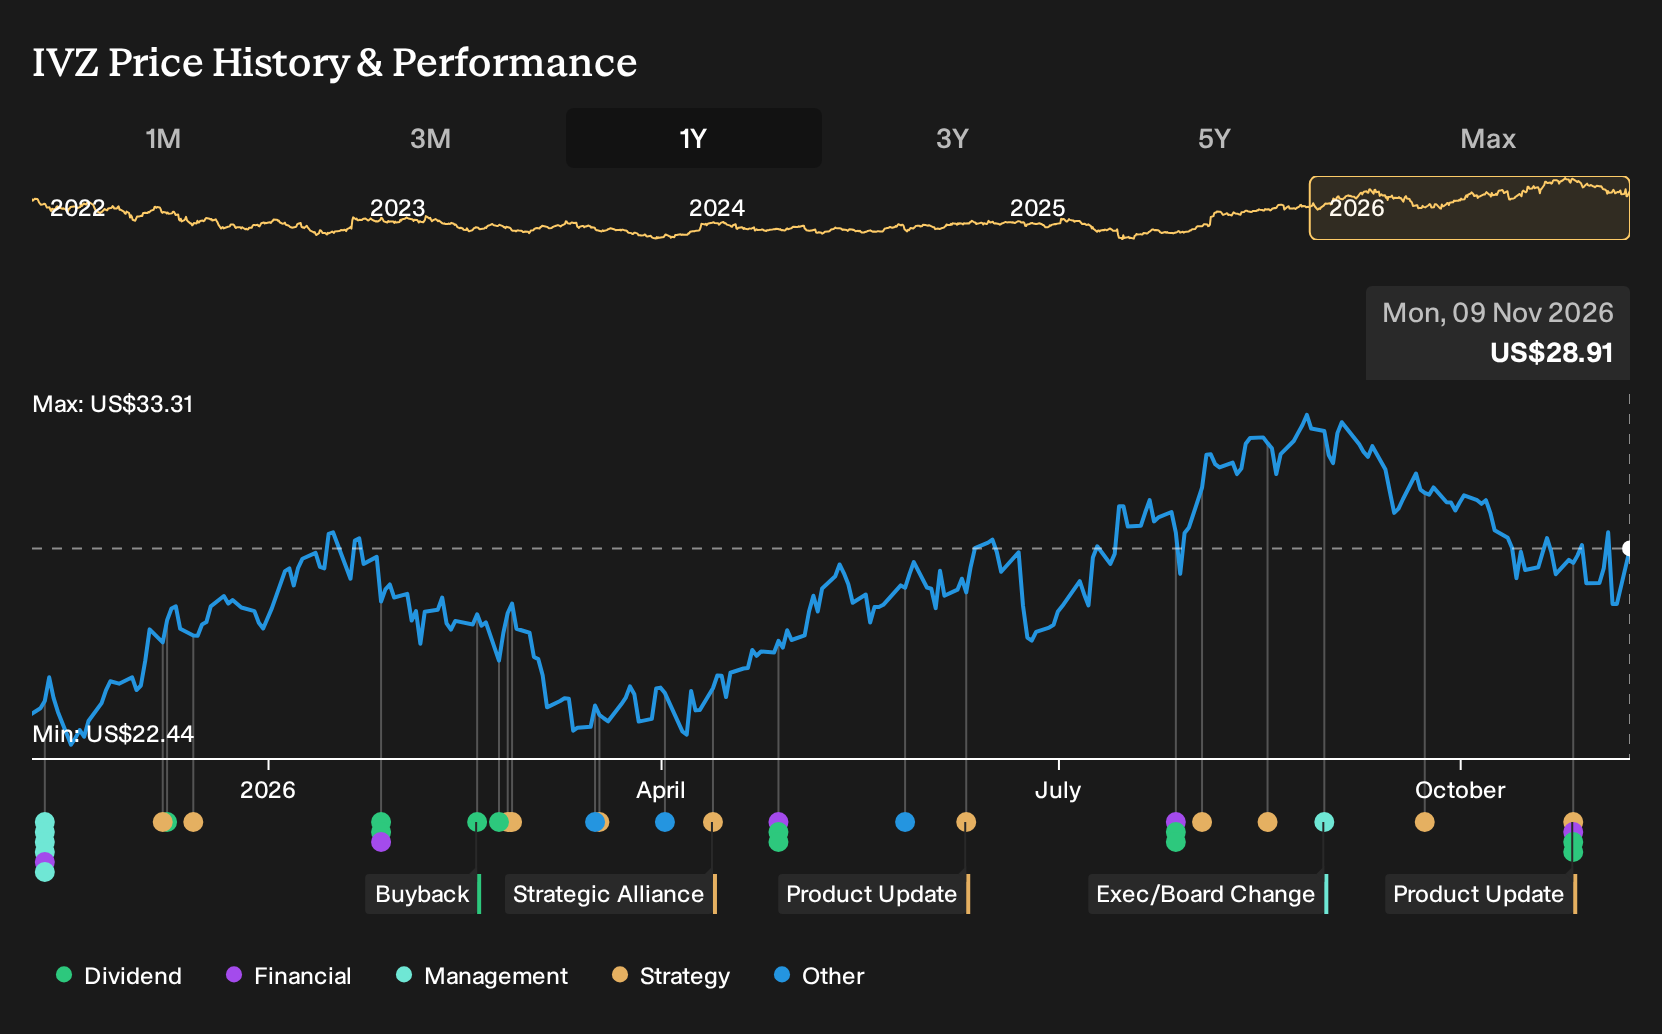
- Invesco reported third quarter 2026 revenue of US$1,873.2 million and net income of US$331.5 million, alongside cash dividends on both common and preferred shares and updated buyback activity details.
- The newly announced Invesco connector for Claude for Financial Advisors brings the firm’s model portfolios and portfolio intelligence directly into advisor workflows, signaling a push to tie its investment expertise more tightly to day to day practice management.
- We will now look at how Invesco's new Anthropic powered advisor tools could influence the investment narrative built around its platform shift.
Scan how Invesco's AI push fits alongside other wealth managers already leaning on data driven advice in our curated list of list of solid balance sheet and fundamentals (25 results).
Invesco Investment Narrative Recap
To stay invested in Invesco, you need to believe the shift toward ETFs, SMAs, model portfolios and private markets can offset pressure on fee rates and the cost of building its hybrid platform. The analyst consensus narrative on Simply Wall St leans on earnings growth and margin improvement. The latest quarter, with higher revenue but slightly softer net income, does not materially alter that thesis on its own.
The near term catalyst is execution on the hybrid platform and Anthropic partnership, and whether that starts to show up in operating efficiency while Core Real Estate USA is being supported with lower fees and capital. The biggest risk remains the mix drift toward lower fee products without enough volume and alternatives growth, which could restrain margins while technology expenses stay elevated.
The Anthropic partnership and new Invesco connector for Claude for Financial Advisors looks most relevant to this story. It ties portfolio intelligence, model portfolios and practice management research into tools advisors already use, which directly links to the distribution and efficiency angles that many investors focus on for Invesco.
If the connector helps advisors scale model portfolios, SMAs and custom strategies, it could support the catalysts around asset growth in lower fee vehicles while still aiming for operating leverage. At the same time, any missteps in AI outputs, adoption, or integration costs would play into the existing risk that technology spending, now including AI workflow tools, runs ahead of revenue traction for longer than investors are comfortable with.
Invesco's current analyst narrative points to revenues of US$5.8b and earnings of US$1.5b by 2029, alongside an assumed yearly revenue decline of 6.6% and a move from an earnings loss of US$316.0m today to that forecast, which would require an earnings increase of about US$1.8b.
Uncover how Invesco's fair value indicates a 30% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Invesco, the alternate, more upbeat storyline hinges on AI enabled workflows turning into a profit engine. Some analysts were already penciling in revenue of about US$6.2b and earnings of roughly US$2.0b by 2029. Those forecasts came before this Anthropic connector news, so your own view on AI execution could push you closer to or further from that optimistic camp.
Explore 3 other Invesco fair value estimates, including one that suggests there may be as much as 87% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Invesco research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Invesco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Invesco's overall financial health at a glance.
Looking for more investment ideas beyond Invesco?
Once you have a view on Invesco, it often helps to line it up against a broader watchlist so you can see what else competes for your capital and attention.
- If you care most about resilience and balance sheet strength, scan through a curated 31 resilient stocks with low risk scores that may help anchor the more volatile parts of your portfolio.
- For investors hunting for potential mispricings, weigh Invesco against a carefully filtered pool of 40 high quality undervalued stocks that pair fundamentals with pricing signals.
- If you want future frontrunners that fewer people are talking about, broaden your research to a focused group of 19 high quality undiscovered gems that still show solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com