
Is Zai Lab (ZLAB) A Bargain After New Trial Data And Fresh Funding?
Zai Lab (ZLAB) is back on investors’ screens after fresh Phase 1 data for its lead cancer drug, new funding, and third quarter 2026 results that outlined a packed development agenda.
That mix of fresh drug data, new equity funding and third quarter results has fed directly into the share price. Zai Lab’s 1 day share price return of 12.7% and 7 day share price gain of 15.5% point to building momentum after a 47.0% year to date move, even though the 5 year total shareholder return is still down 70.1%.
Ride this renewed interest in Zai Lab to reassess your own watchlist by scanning a curated set of 19 high quality undiscovered gems that share strong fundamentals and under-the-radar potential.After a 47.0% year to date climb, fresh zoci data and new cash in the bank reset the story. Does Zai Lab’s risk reward still lean toward buyers at today’s US$25.48?
Most Popular Narrative: 24% Undervalued
Against the last close at $25.48, the analyst consensus Narrative on Simply Wall St anchors Zai Lab’s fair value at $33.48, implying a material gap that the market has not closed yet. That view rests on explicit assumptions about future revenue, margins and funding rather than vague optimism.
The planned shift for Zai Lab from a mainly China-focused commercial business to a global biopharma company, including the first U.S. regulatory submission in 2027 and a potential first U.S. launch in 2028, points to a larger addressable market that could influence long term revenue and earnings.
See why 13 investors see Zai Lab as 24% undervalued.
Result: Fair Value of $33.48 (UNDERVALUED)
Still, Zai Lab’s reliance on partnered assets and a China franchise that saw product revenue of US$105.8 million in Q2 2026, down 3.3% year on year, could challenge that upbeat narrative.
Find out about the key risks to this Zai Lab narrative.
Another View on Zai Lab’s Valuation
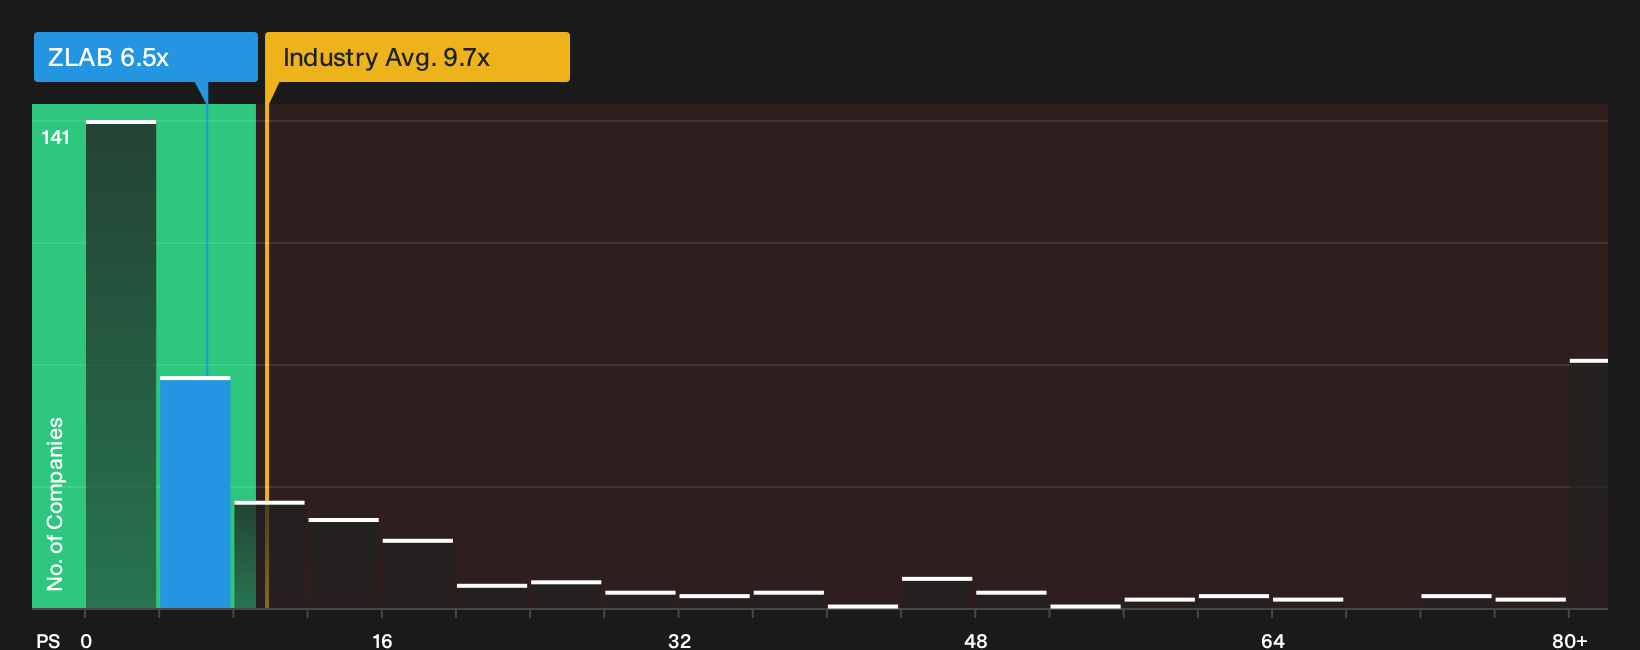
The analyst narrative relies on future earnings and a fair value of $33.48, yet the current P/S of 6.5x presents a different picture. That ratio appears expensive compared to a fair ratio of 3.5x, even though it is below the US Biotechs average of 9.6x and the peer average of 10.4x. Is the market overpaying for growth or underestimating long term cash flows?
To see how these sales multiples compare with the underlying cash flow story, and where the fair ratio might eventually converge, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the Zai Lab story are clear, so move quickly, focus on testing the numbers that matter most to you, then weigh the 3 key rewards and 1 important warning sign
Looking for more Zai Lab sized opportunities?
Do not stop at Zai Lab. Put the same disciplined lens over a broader watchlist by scanning focused stock ideas tailored to different risk and return preferences.
- Target potential mispricing by reviewing a curated group of 40 high quality undervalued stocks that pair quality fundamentals with compressed expectations.
- Strengthen portfolio resilience by filtering for a list of solid balance sheet and fundamentals (25 results) that can better handle funding swings and economic shocks.
- Lower portfolio volatility by concentrating on 31 resilient stocks with low risk scores that score well on stability and financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com