
Learn Why The Bull Case For PepsiCo (PEP) Could Change Following KFC Deal Renewal
- PepsiCo and KFC have renewed PepsiCo as the preferred beverage partner across key international markets including Australia, India, the UK and several European countries, extending a decades-long collaboration that aligns drink and menu offerings with local tastes.
- The renewed KFC agreement, together with PepsiCo's emphasis on zero-sugar and better-for-you drinks, highlights how its global distribution and product mix are being shaped around changing consumer health preferences.
- We will examine how PepsiCo's income focused investment narrative relates to this renewed KFC partnership around zero sugar beverages.
Scan how other dividend focused consumer brands are positioning around health trends by reviewing the hand picked 7 dividend fortresses alongside PepsiCo's renewed KFC partnership and its zero sugar push.
PepsiCo Investment Narrative Recap
To own PepsiCo, you need to believe in a slow and steady consumer staple that mixes modest earnings growth with a long dividend track record. According to Lijo, a Simply Wall St Community investor who wrote the Narrative, the appeal is a growth and income compounder rather than a fast mover. The renewed KFC deal outside the US helps keep that story intact and offsets some concern around the loss of US KFC volumes.
The near term catalyst is clear execution on cost cuts and stable cash generation while PepsiCo retools around zero sugar and better for you drinks. The biggest operational risk sits in pressured PepsiCo Foods North America trends and the high debt load. Investors will likely keep watching whether management holds margins and service levels even as it leans into healthier offerings and away from legacy products.
The renewed KFC partnership across Australia, India, the UK and parts of Europe links directly to another recent focus area: zero sugar and lower sugar beverages. PepsiCo is leaning on Pepsi Zero Sugar, Mountain Dew Zero Sugar and Gatorade Lower Sugar, and this KFC footprint gives more away from home exposure where Gen Z and younger families are already choosing meals.
That matters for the same catalysts Lijo highlights around dependable cash generation and dividend support. If zero sugar and better for you drinks keep gaining share inside large customers like KFC, it can help PepsiCo balance softer US categories and support continued investment in brands, even while servicing its higher debt levels and maintaining its equity income profile.
Lijo sets a narrative fair value for PepsiCo at $200.01, assuming annual revenue growth of 14.9% and a future profit margin of 10.8%. Together, these inputs suggest a higher earnings base that can support ongoing dividends and reinvestment while maintaining the company’s income profile.
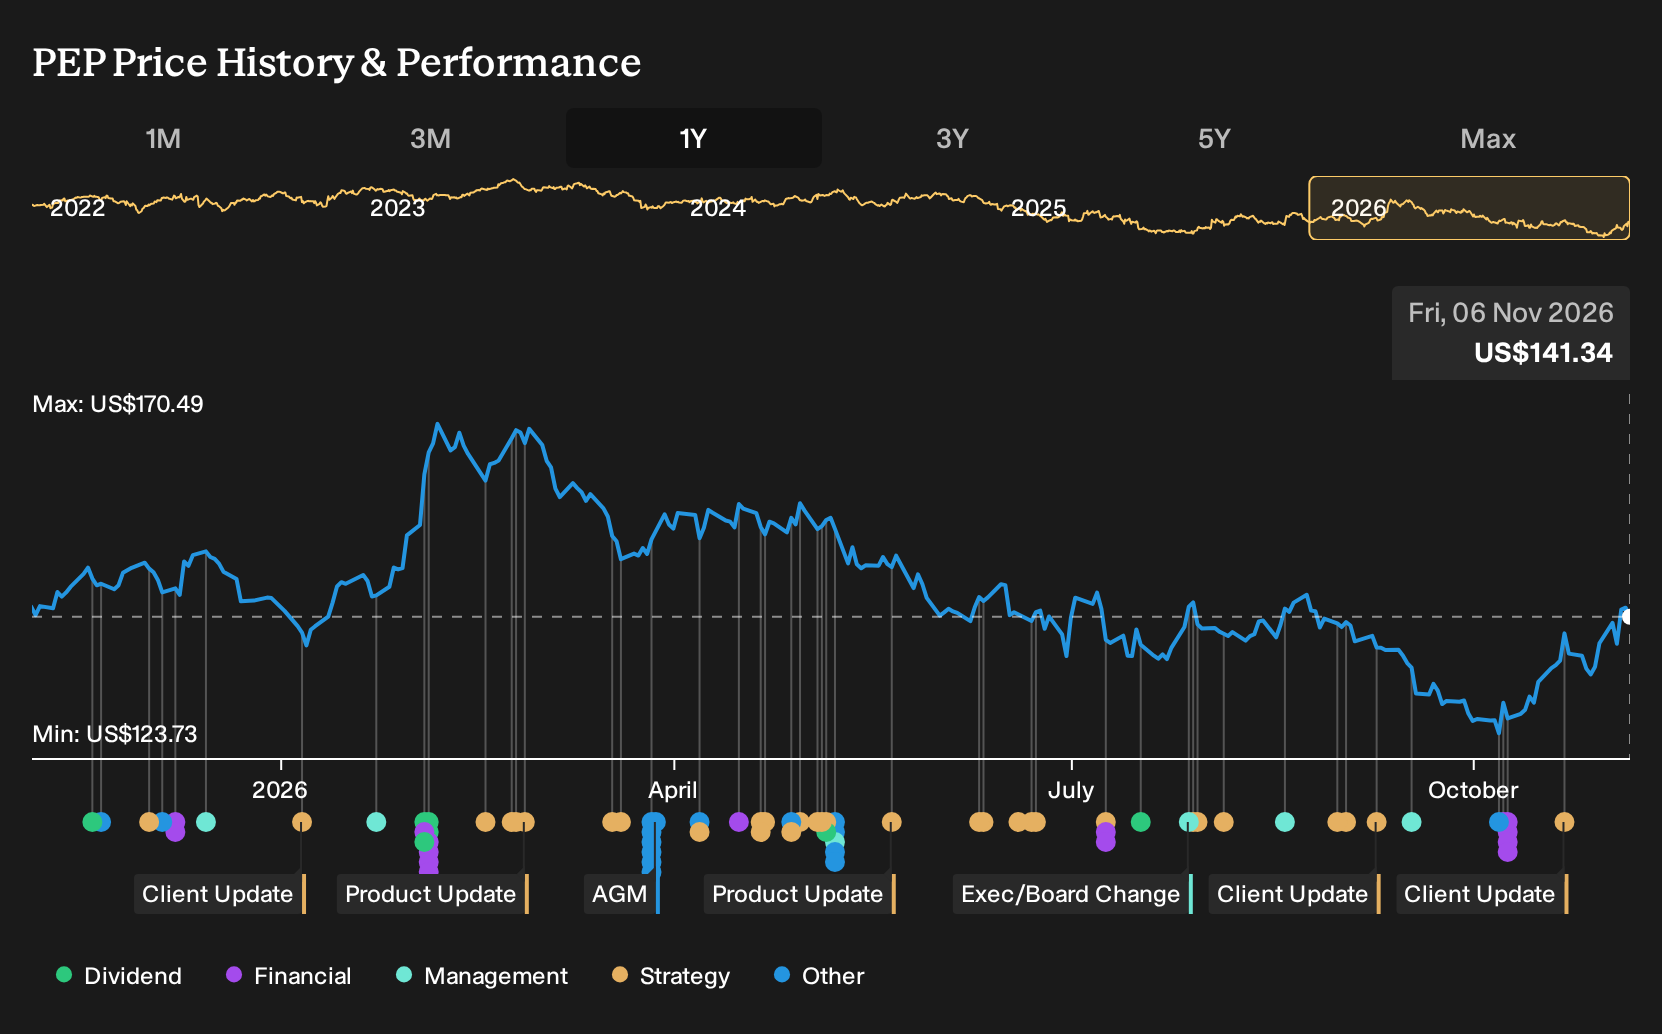
Uncover how PepsiCo's fair value indicates a 42% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fifteen fair value estimates from the Simply Wall St Community span PepsiCo at about US$116 on the low end to roughly US$273 at the top, which is a wide spread for one ticker. That gap meets fresh catalysts, including the renewed KFC partnership and zero sugar push, so you should compare several Community viewpoints before deciding how PepsiCo fits your own income plan.
Explore 14 other PepsiCo fair value estimates, including one that suggests potential upside of as much as 93% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PepsiCo research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PepsiCo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PepsiCo's overall financial health at a glance.
Looking for more PepsiCo style income ideas?
If the PepsiCo story around dependable cash flows and dividends appeals to you, it can help to compare it with other opportunities that share similar traits or offer a different risk and yield mix.
- For investors who want income potential with a value tilt, scan a curated group of companies trading at attractive valuations using the Simply Wall St screener built around 40 high quality undervalued stocks.
- If balance sheet strength is a priority, especially when relying on dividends, focus on businesses with robust finances by reviewing the screener built on a list of solid balance sheet and fundamentals (25 results).
- When you want income ideas that are off the beaten path, broaden your watchlist with a hand picked set of underfollowed opportunities through the screener highlighting 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com