
Should Earnings Miss Require Action From Flagstar Bank (FLG) Investors?
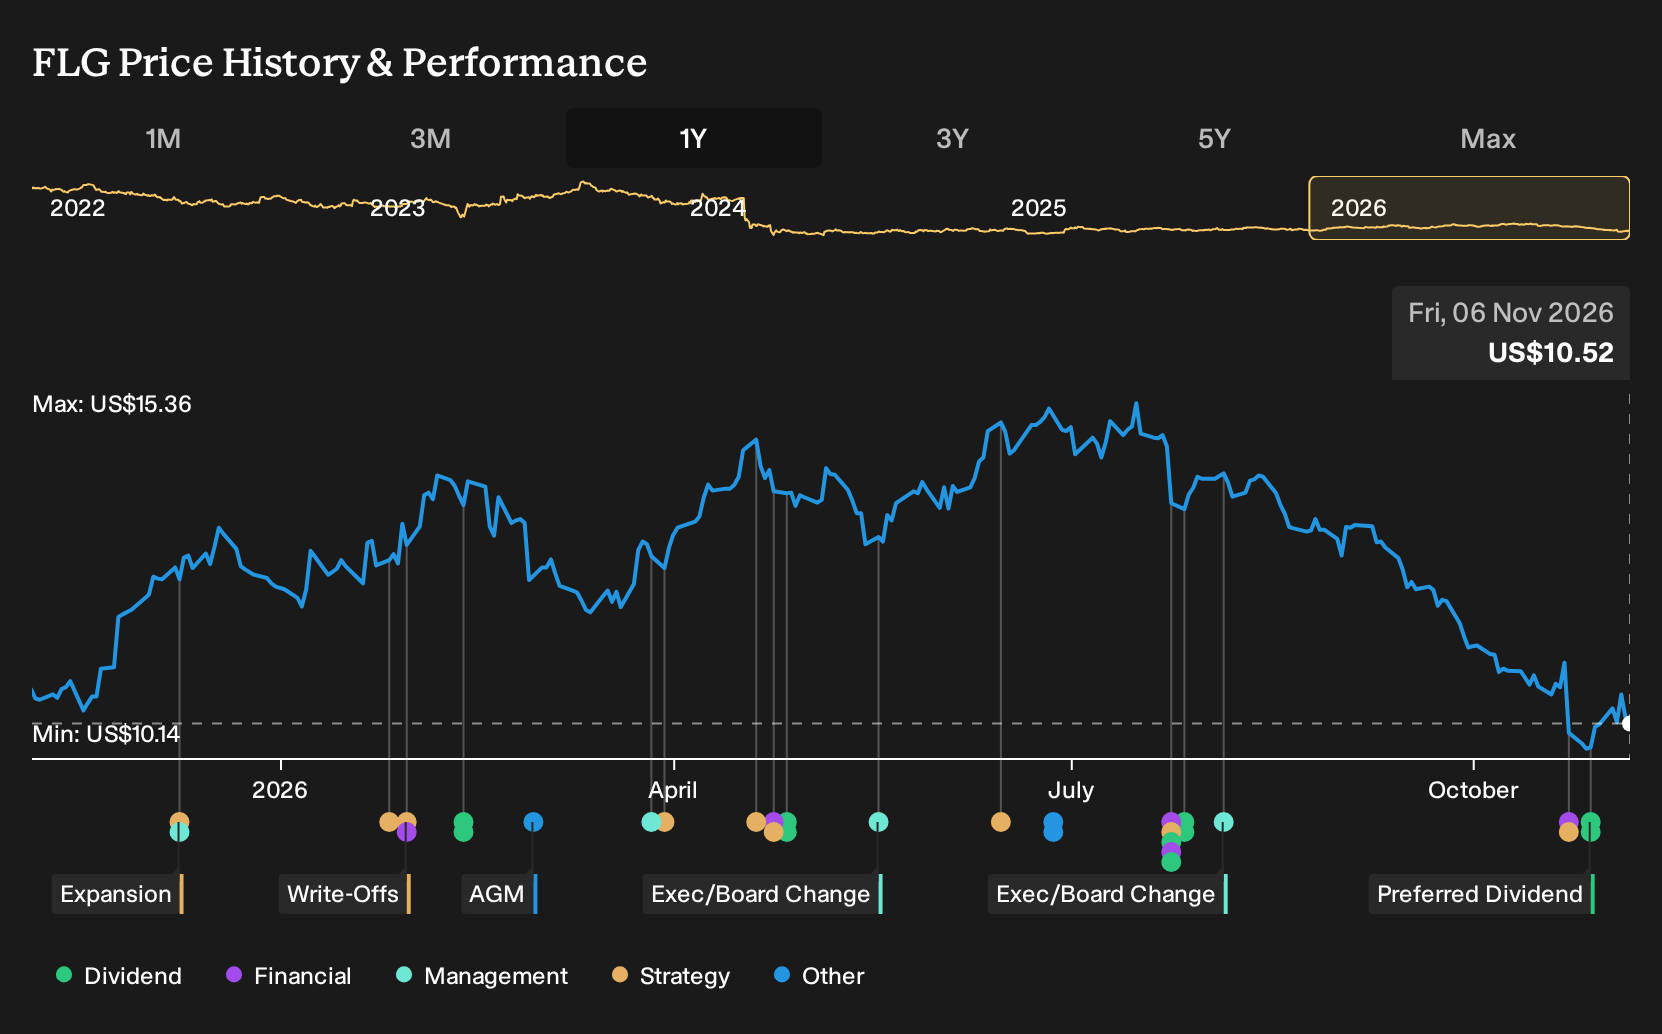
- Flagstar Bank National Association declared a quarterly cash dividend of US$0.01 per common share and confirmed quarterly payouts on its Series A, B and D preferred stock, all payable on 17 December 2026 to holders of record on 7 December 2026.
- The dividend moves come shortly after a third quarter earnings miss and a delayed turnaround timeline that has prompted a shareholder investigation, putting Flagstar Bank’s capital return decisions under closer scrutiny relative to its operating challenges.
- We will now assess how Flagstar Bank’s earnings miss and extended turnaround plan could reshape its previously outlined investment narrative.
Compare Flagstar Bank’s dividend stance and earnings reset with a hand picked group of resilient income and balance sheet plays in our list of solid balance sheet and fundamentals (25 results).
Flagstar Bank National Association Investment Narrative Recap
An investor in Flagstar Bank National Association needs to believe the commercial and industrial lending buildout and balance sheet reshuffle can eventually support consistent profitability. The analyst consensus narrative on Simply Wall St focuses on expanding net interest margin, lower noninterest expense and strong capital ratios to underpin that view. The recent earnings miss and delayed turnaround timeline suggest execution is proving harder than initially expected.
The key short term catalyst is whether management can show cleaner credit metrics and steady progress on nonaccrual reductions while keeping funding costs in check. The shareholder investigation highlights the main current risk, which is pressure on credibility if credit trends, bad loan ratios or costs weaken from here.
The most relevant update is the US$0.01 common dividend and continued preferred dividends. On the surface, the common payout is modest, especially against a market value of about US$4.19b and a P/E of 66.5x. It still signals that Flagstar Bank National Association is not currently prioritizing higher common cash returns as a key part of the near term story.
For investors, the announcement matters because it keeps the focus on balance sheet repair and operational execution rather than aggressive capital returns. With earnings having only recently moved into profit and credit risk indicators, including a 4.5% bad loan ratio and 31% allowance, still in focus, the dividend decision sits alongside the extended turnaround timeline as another reminder that this remains a clean up and rebuild phase.
Flagstar Bank National Association is framed around analysts expecting revenues of US$3.3b and earnings of US$1.1b by 2029, which implies forecast revenue growth of 18.4% a year, and an earnings increase of about US$1.04b from current earnings of US$63.0m.
Uncover why Flagstar Bank National Association's fair value indicates a 25% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community span roughly US$1.67 to US$13.18 per share, which is a wide gap for Flagstar Bank National Association. You are seeing very different views from private investors. Set that against the earnings miss, delayed turnaround and legal investigation, and you have a mix of upside scenarios and credibility risk that is worth exploring across multiple viewpoints.
Explore 2 other Flagstar Bank National Association fair value estimates, including one that suggests there could be as much as 25% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Flagstar Bank National Association research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Flagstar Bank National Association. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flagstar Bank National Association's overall financial health at a glance.
Looking For More Investment Ideas Beyond Flagstar Bank National Association?
Once you have a view on Flagstar Bank National Association, it can help to compare that thesis with other opportunities that have different risk, income and balance sheet profiles. The Simply Wall St Screener lets you scan for companies that better match the mix of stability, value or yield you want in your portfolio.
- If capital preservation is high on your list, scan for 31 resilient stocks with low risk scores that pair resilient financial profiles with more measured volatility.
- For potential mispricings based on fundamentals, look through the 40 high quality undervalued stocks and see which opportunities fit your return and risk preferences.
- If you want quality that is not heavily followed yet, the 19 high quality undiscovered gems can surface under the radar ideas worth a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com