
Price Hike Could Be A Game Changer For Whirlpool Stock (WHR)
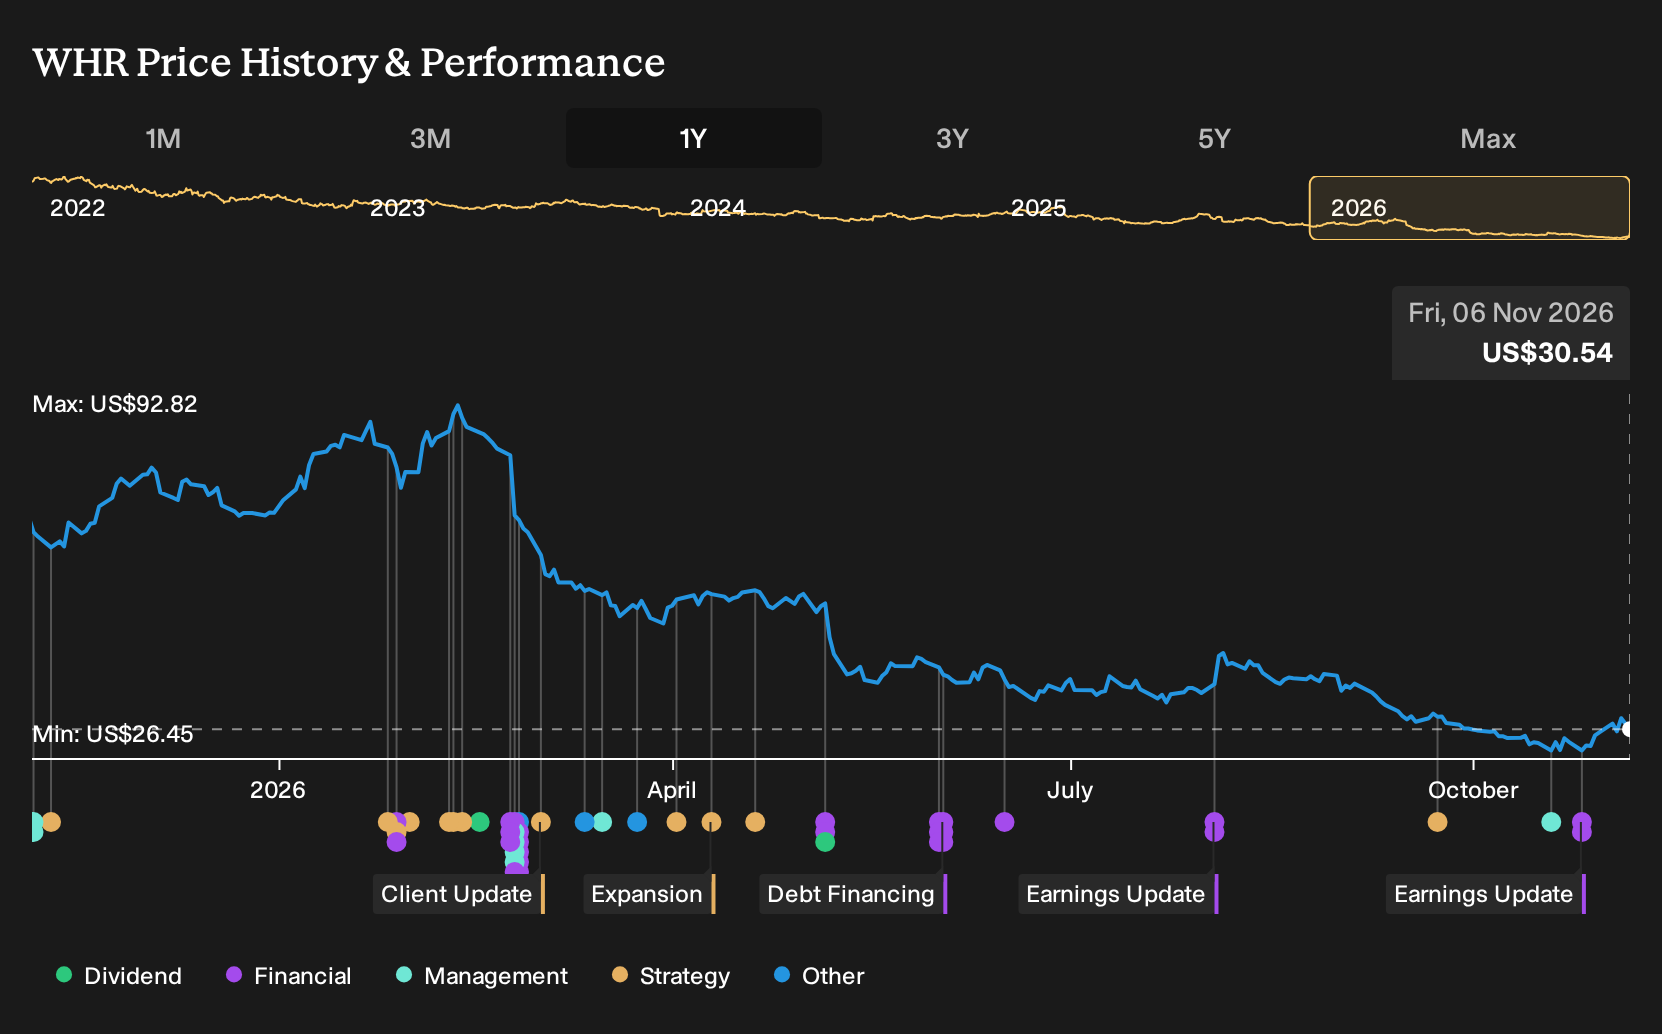
- Whirlpool reported third quarter 2026 sales of US$3,677 million and a net loss of US$237 million, alongside guidance that points to a full year GAAP loss and a planned 7% average appliance price increase from December to address supply cost pressures and softer demand.
- The combination of ongoing operating losses, expected 2026 net sales of about US$14.5b and price hikes in a weak housing market highlights how Whirlpool is leaning on both cost cuts and higher pricing to protect margins while appliance demand remains under strain.
- The next focus is on how Whirlpool’s planned 7% price increase could reshape the existing investment narrative around cost restructuring and efforts to repair margins.
Scan Whirlpool’s pricing reset against peers by zeroing in on companies with sturdier finances using our curated list of solid balance sheet and fundamentals (25 results) as your starting universe.
Whirlpool Investment Narrative Recap
To own Whirlpool today, an investor needs to believe the current loss making period can eventually give way to a healthier appliance business built on cost savings, better product mix and a more rational pricing structure. The third quarter loss of US$237 million, together with nine month net sales of US$10,467 million, underlines how much work is still in front of the company.
The analyst consensus narrative on Simply Wall St leans on factory consolidation and automation benefits from 2027. However, the near term story is different. Whirlpool now expects about US$14.5b of 2026 sales and a GAAP net loss margin of 2.2%. The key near term catalyst is whether price hikes and cost cuts slow the cash burn before demand weakens further.
The most relevant recent disclosure for this story is Whirlpool’s full year 2026 outlook. Management is guiding to US$14.5b of net sales, a GAAP loss per share of US$4.95 and ongoing loss per share of US$1.30. That sits alongside the third quarter swing from a US$73 million profit a year ago to a US$237 million loss.
Together with the December average 7% price increase, that guidance frames the next test for the stock. Execution on factory consolidation and logistics changes, which analysts expect to yield at least US$150 million of 2026 savings, has to offset weak housing driven volumes and higher interest expense. The risk is that industry demand stays soft and keeps Whirlpool’s margins pinned down for longer.
On current analyst assumptions, Whirlpool's story rests on revenues reaching US$15.6b and earnings of US$201.3 million by 2029. This implies forecast revenue growth of 2.4% a year and an earnings swing of about US$353 million from earnings today of a US$152.0 million loss.
Uncover why Whirlpool's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate Whirlpool narrative puts much greater emphasis on recurring cash burn risk. Before this earnings miss and the 7% price hike news, the most cautious analysts were already bracing for about US$16.0b of 2029 revenue and only US$223.2 million of earnings. That is a much harsher earnings path than consensus, so use it as a prompt to compare several viewpoints and stress test your own assumptions.
Explore 4 other Whirlpool fair value estimates, including one that suggests as much as 51% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own independent analysis.
- A great starting point for your Whirlpool research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Whirlpool. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Whirlpool's overall financial health at a glance.
Looking For More Ideas Beyond Whirlpool?
Once you have a view on Whirlpool, it can help to set it alongside other opportunities so you can judge risk, quality and income potential on your own terms.
- If capital preservation is your priority, start by scanning a 31 resilient stocks with low risk scores that aims to pair steadier balance sheets with more resilient business models.
- For investors hunting for mispriced quality, weigh Whirlpool against a 40 high quality undervalued stocks that combines solid fundamentals with more attractive valuations.
- If you want income to do more of the work, compare its payout profile with a 7 dividend fortresses that focuses on higher yielding stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com