
Should Updated 2026 Guidance Require Action From American Tower Stock Investors?
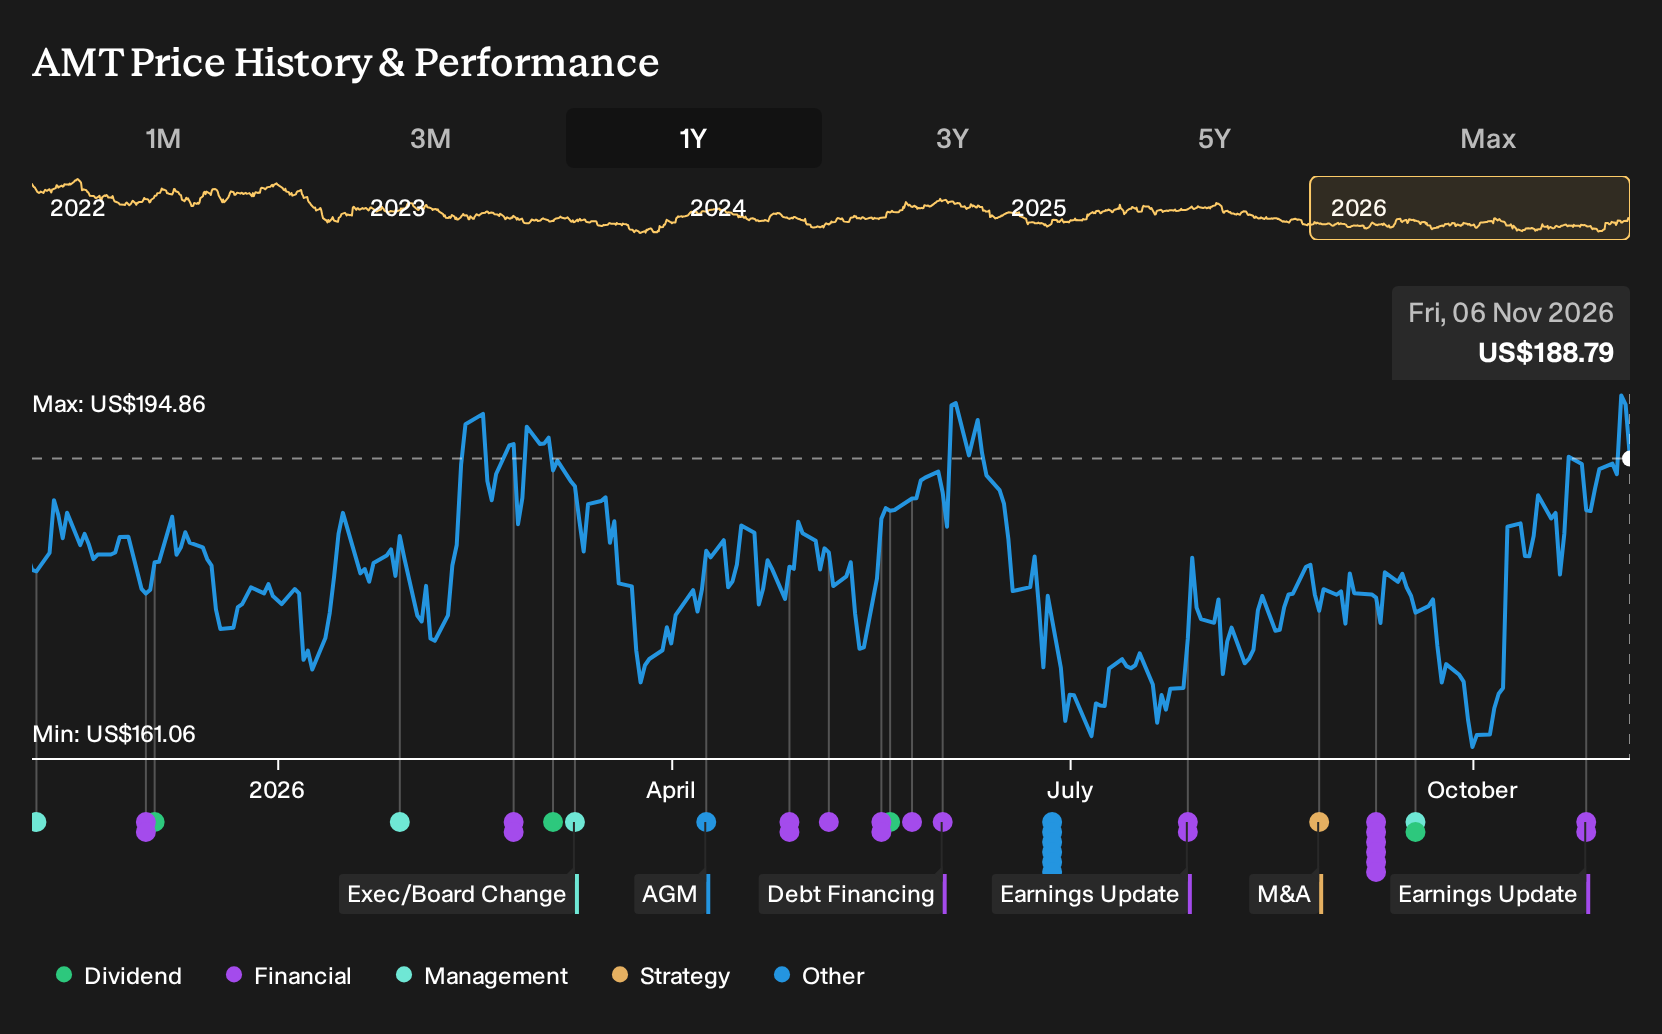
- American Tower reported third quarter 2026 basic earnings per share from continuing operations of US$1.65, compared with US$1.82 a year earlier, while basic EPS for the first nine months reached US$5.35, compared with US$3.65 for the same period in 2025.
- The company updated its 2026 outlook and projected total property revenue between US$10.785b and US$10.865b and net income attributable to common stockholders between US$3.183b and US$3.238b, which gives investors clearer visibility into American Tower's earnings power and capital needs for its tower and data center assets.
- We will examine how American Tower's investment narrative around digital infrastructure is reshaped by the new 2026 property revenue and earnings guidance.
Scan beyond American Tower and see how other digital infrastructure plays are positioned for the AI workload build out with our hand picked 53 AI infrastructure stocks in one place.
American Tower Investment Narrative Recap
To own American Tower, you need to believe that mobile data and AI related traffic will keep feeding demand for its towers and data centers, and that carriers eventually translate that into more equipment on sites rather than slower 5G rollouts. The recent third quarter results, where basic EPS from continuing operations moved from US$1.82 to US$1.65 year on year, do not change that long term thesis on their own.
In the near term, the key swing factor is how quickly operators choose to densify networks and lease more space on existing infrastructure, set against funding costs that already pressure cash flow coverage of debt. The main risk remains that higher interest expenses and churn events, such as exits or consolidation among carriers, absorb more of American Tower's earnings power just as it leans harder into developed markets and AI heavy data center demand.
The most relevant recent data point is the updated 2026 outlook that pegs total property revenue at US$10.785b to US$10.865b and net income attributable to common stockholders at US$3.183b to US$3.238b. That range effectively becomes the new scorecard for how well American Tower is converting carrier and cloud demand into rent, margins and capacity to fund its capital plan.
For investors, that guidance ties directly into both catalysts and risks. It frames what success looks like for U.S. and European tower amendments, CoreSite data center leasing to AI and cloud customers, and the cost of servicing debt. Any gap between these targets and actual results would feed directly into the debate over whether American Tower can keep growing earnings while managing interest expense and churn from carrier consolidation.
American Tower's current earnings are US$3.4b, and analysts forecast consensus earnings of US$3.8b by 2029, which implies an increase of about US$0.4b. They also model revenue climbing to US$12.5b in the same year on 4.4% yearly revenue growth.
Uncover why American Tower's fair value indicates a 14% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$216 to US$307 per share, so some retail investors see American Tower as heavily undervalued, while others price in a richer future. Those views sit against risks around carrier spending, interest costs and AI data center demand, all of which could shift how the business performs.
Explore 3 other American Tower fair value estimates, including one that suggests it could be worth just $215.70.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your American Tower research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for American Tower. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Tower's overall financial health at a glance.
Looking For More Investment Ideas Beyond American Tower?
Once the American Tower story is clear in your mind, the next step is to widen your watchlist and compare it with other opportunities that fit different risk and income profiles.
- If capital protection sits high on your priority list, check out a basket of 31 resilient stocks with low risk scores that may suit a more cautious approach.
- If you care most about balance sheet resilience and underlying fundamentals, scan through the list of solid balance sheet and fundamentals (25 results) to see which businesses match your quality filter.
- If you are hunting for companies that the market may not be fully focused on yet, run your eye over the 19 high quality undiscovered gems and see which ones deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com