
Earnings And Revenue Outlook Altering The Investment Case For Lennox International Stock?
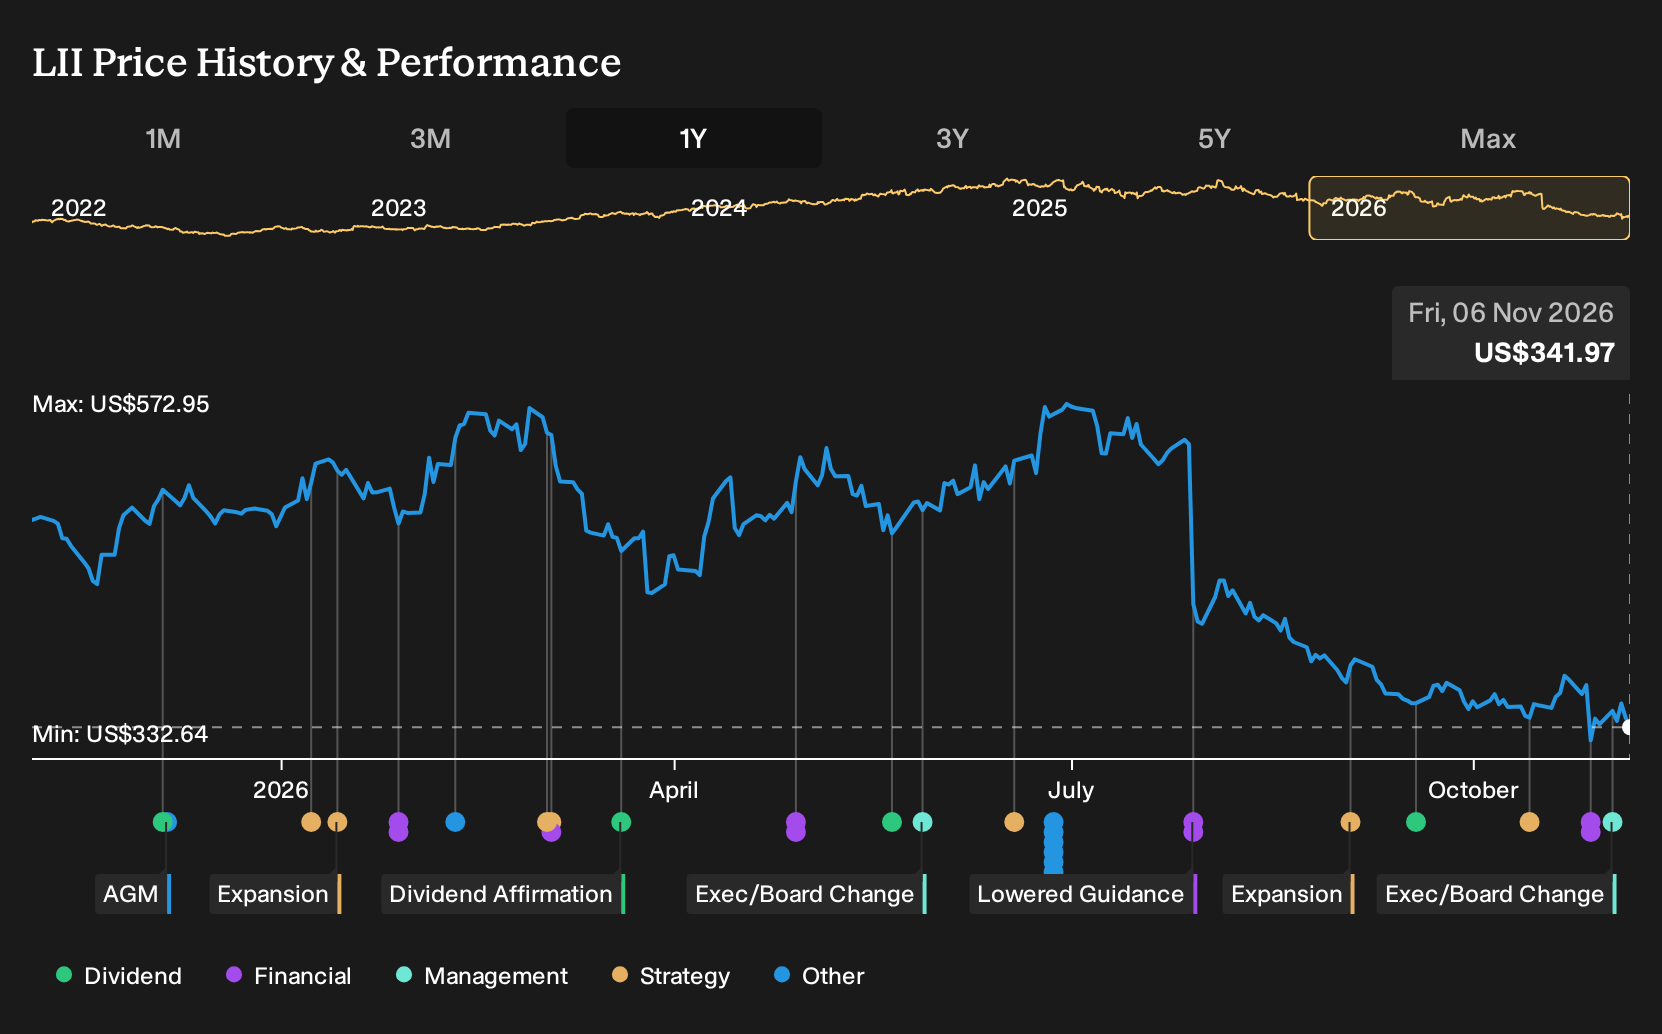
- Lennox International reported third quarter 2026 sales of US$1,572.5 million and net income of US$221.2 million, alongside revised full year 2026 revenue growth guidance of about 6% that includes a 5% contribution from completed acquisitions.
- The mix of higher sales with lower earnings, plus guidance that leans heavily on acquisition driven expansion, highlights the current pressure on Lennox International’s profitability, even as management leans into deal making to support top line progress.
- Attention now shifts to how Lennox International's investment narrative absorbs higher third quarter sales alongside lower earnings and updated revenue guidance.
Compare Lennox International’s acquisition driven playbook with other companies that screen well for resilient fundamentals in this environment by scanning our curated list of solid balance sheet and fundamentals (25 results).
Lennox International Investment Narrative Recap
To own Lennox International, you need to believe the commercial expansion, parts and service focus, and higher efficiency product mix can offset pressure in residential markets and on margins. The recent third quarter showed higher sales with lower earnings, so the near term hinge is whether profitability stabilises as acquisitions are integrated and factory throughput normalises.
The biggest risk right now is that residential weakness and factory under absorption persist or deepen, keeping net margins under strain and limiting earnings from Home Comfort Solutions. The latest earnings and guidance tweak do not radically change that equation, but they keep execution risk on cost control and integration squarely in focus.
The leadership transition in Building Climate Solutions is the announcement that matters most against this backdrop. Joe Nassab moves to a strategic advisor role at the end of 2026 and Geoff Dethlefsen steps in from January 2027. For a segment built up through acquisitions, manufacturing investment and service capability, continuity of execution is critical.
For you as an investor, the question is whether Lennox International can keep Building Climate Solutions growing and improving mix while dealing with residential softness and legal overhang. Management depth, including Dethlefsen’s industrial and operations background, will be tested as the business leans on commercial HVAC, parts and services as key catalysts.
Lennox International's narrative projects US$6.6b revenue and US$1.1b earnings by 2029. This assumes 7.5% yearly revenue growth and an earnings increase of about US$311.5m from US$788.5m today.
Uncover why Lennox International's fair value indicates a 28% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You might see Lennox International very differently if you focus on margin pressure instead of growth potential. The most cautious analysts were penciling in about US$6.3b revenue and US$971.5m earnings by 2029 before this leadership change and the latest earnings, which is well below the US$6.6b and US$1.1b consensus path. Those lower forecasts reflect a view that commercial gains and acquisitions may not fully offset weaker residential trends and higher costs. Opinions clearly span a wide range. Treat this news as a prompt to compare several narratives and decide which assumptions feel closest to your own.
Explore 3 other Lennox International fair value estimates, including one that suggests it could be worth just $371.92.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Lennox International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lennox International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lennox International's overall financial health at a glance.
Looking For More Ideas Beyond Lennox International?
If Lennox International has sharpened your thinking about quality, risk and earnings power, you can use that same lens across the wider market with the Simply Wall St Screener. It helps you quickly surface companies that fit the balance of resilience, income and upside potential that suits your approach.
- If you want potential upside with a margin of safety, start by reviewing our 38 high quality undervalued stocks that currently pass a blend of quality and valuation checks.
- If portfolio resilience matters most to you, filter for companies on the 31 resilient stocks with low risk scores and see which businesses pair steadier risk profiles with solid fundamentals.
- If you are hunting for strong balance sheets and durable fundamentals, scan the list of solid balance sheet and fundamentals (25 results) to compare alternatives to Lennox International that still keep financial strength front and centre.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com