
Earnings Pressure Might Change The Case For Investing In Nike (NKE)
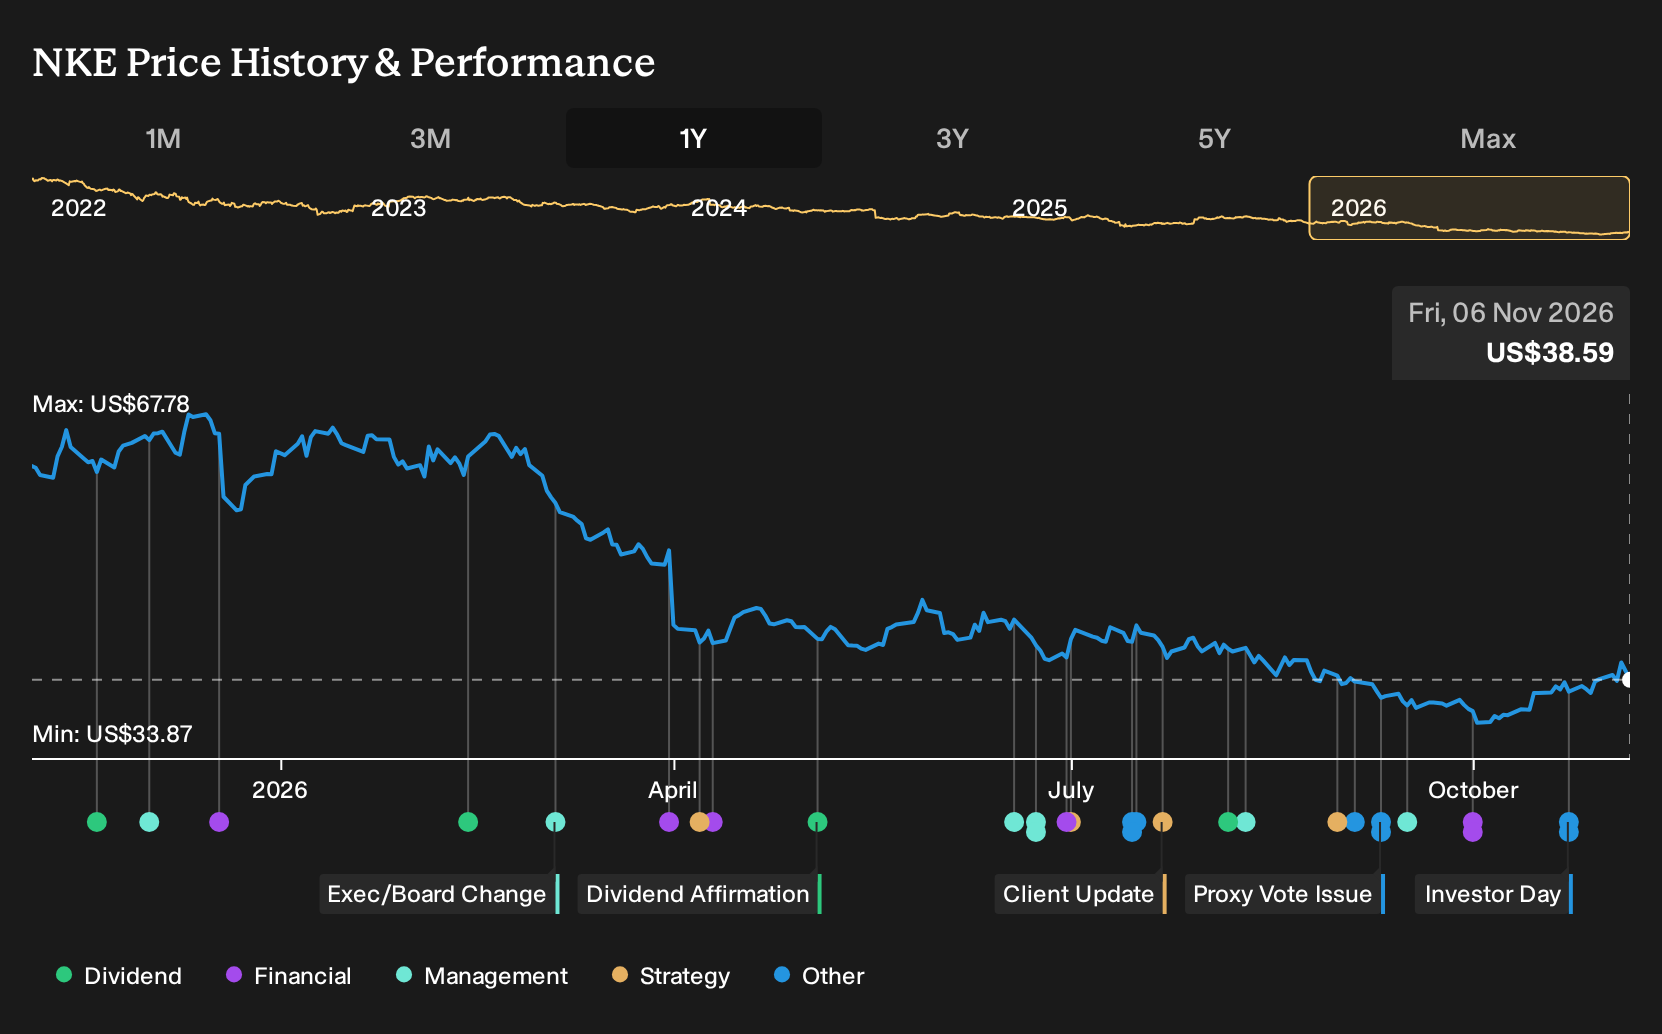
- Nike is cutting supply of classic lifestyle lines such as Sportswear and Jordan, accepting weaker near term revenue as it resets discounting, margins, and brand health, while earnings estimates and forecasts for fiscal 2027 and beyond have been revised lower.
- The company is leaning harder into performance products, cost reduction under the Pace program, and tightly controlled drops, such as the Travis Scott and GTA 6 Air Force 1 collaboration, to support a shift toward higher quality full price demand.
- We will now look at how Nike's reset of Sportswear and Jordan supply, alongside ongoing earnings pressure, reshapes the broader investment narrative.
NIKE Investment Narrative Recap
To own NIKE here, you need to believe the reset in Sportswear and Jordan, plus the shift toward performance product, eventually produces healthier full price demand. In the near term, the key catalyst is whether the Pace cost program and product mix changes can offset pressure from lower classic footwear volumes and softer wholesale orders.
The biggest risk sits in continued revenue and earnings pressure as NIKE intentionally cuts supply while facing weaker demand in Greater China and digital channels. Recent downgrades and lower earnings estimates underline that risk, but they do not fundamentally change the fact that execution on this reset is the main swing factor.
The clearest recent announcement for that debate is NIKE’s plan for fiscal 2027. Management expects revenue to decline in the high single digits and EBIT to fall by an even larger percentage. That guidance aligns directly with the current supply pullback in Sportswear and Jordan and keeps the focus on how deeply profits get hit during the clean up.
For you as an investor, the November 2026 Investor Day is the checkpoint. That event should lay out how Pace savings, performance product growth and NIKE Digital changes might rebuild margins after this reset period, and how management sees the trade off between brand health, inventory discipline and the sustainability of the 4.25% dividend.
What The Current NIKE Forecasts Are Really Asking You To Believe
NIKE's narrative projects US$45.4b revenue and US$3.0b earnings by 2029, with analysts assuming fairly flat yearly revenue growth and an earnings decrease of US$0.1b from US$3.1b today.
Uncover why NIKE's fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view on Nike focuses on the Pace cost program as a powerful long term catalyst. The most optimistic analysts were modeling about US$50.7b of revenue and US$4.4b of earnings by 2029. That is much higher than consensus and reflects confidence that cost savings and premium distribution could matter more than this latest reset. These projections were all set before the recent news, so you should expect opinions to move as fresh data comes through and explore how both narratives might evolve.
Explore 11 other NIKE fair value estimates, including one that suggests as much as 33% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NIKE research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NIKE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NIKE's overall financial health at a glance.
Looking For More Investment Ideas Beyond NIKE?
If NIKE's reset has you rethinking portfolio balance, it can help to line it up against other companies with different risk and income profiles. Use the Simply Wall St Screener to quickly filter for businesses that match your preferred mix of quality, stability and potential upside.
- For investors who want income resilience to help offset single stock risk, check out a curated set of 7 dividend fortresses that focus on higher yields with support from underlying fundamentals.
- If capital preservation sits high on your list, scan a hand picked group of 31 resilient stocks with low risk scores that score well on balance sheet strength and volatility metrics.
- When you are hunting for future leaders before they hit the spotlight, review a targeted collection of 19 high quality undiscovered gems that pair cleaner financials with room to grow into their potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com