
Is Melexis (ENXTBR:MELE) Undervalued Following Q3 Earnings And India Expansion?
Why Melexis Stock Is Back In Focus After Q3 2026
Melexis (ENXTBR:MELE) moved back onto investors' radar after its Q3 2026 update combined three signals in quick succession. Fresh quarterly figures, confirmed second half guidance, and a push into India all arrived on the same day.
Across 2026, Melexis has seen short term pressure with a 1 month share price return down 17.3% and a 3 month share price return down 25.6%, while the 1 year total shareholder return is down 3.1%. Recent momentum has been fading, even as the Q3 results, confirmed second half guidance and the India expansion all reset expectations around growth potential and risk.
Scan how Melexis compares with other chip makers aiming at electrification and smart energy by lining it up against 90 robotics and automation stocks in your next round of research.
For Melexis, a falling share price set against steady guidance and new investment in India raises a simple tension: Are markets reassessing the business, or just resetting sentiment around the current valuation?
Most Popular Narrative: 70% Overvalued
Melexis last closed at €53.40, while the most followed valuation narrative, according to StoxEurope, puts fair value at €31.49 per share. That gap frames the current debate around how much optimism is already embedded in the price.
The StoxEurope estimate for Melexis is €31,49 per share, as at 25 September 2026. The share price that day was €66,80.
The estimate comes from the primary model, a discounted cash flow of the whole business. That model was chosen for this company before any value was computed. Across three scenarios it gives:
• Downside: the downturn lingers: €22,82
• Base: the guided recovery holds: €31,49
• Upside: the business moves back towards its 2023 peak: €40,85
These are three described futures, not a statistical confidence interval.
See why 1 investors see Melexis as 70% overvalued.
Result: Fair Value of €31.49 (OVERVALUED)
Still, the StoxEurope view could be challenged if Melexis delivers stronger cash generation or adjusts dividends in order to keep the balance sheet tighter.
Find out about the key risks to this Melexis narrative.
Another View On Melexis Valuation
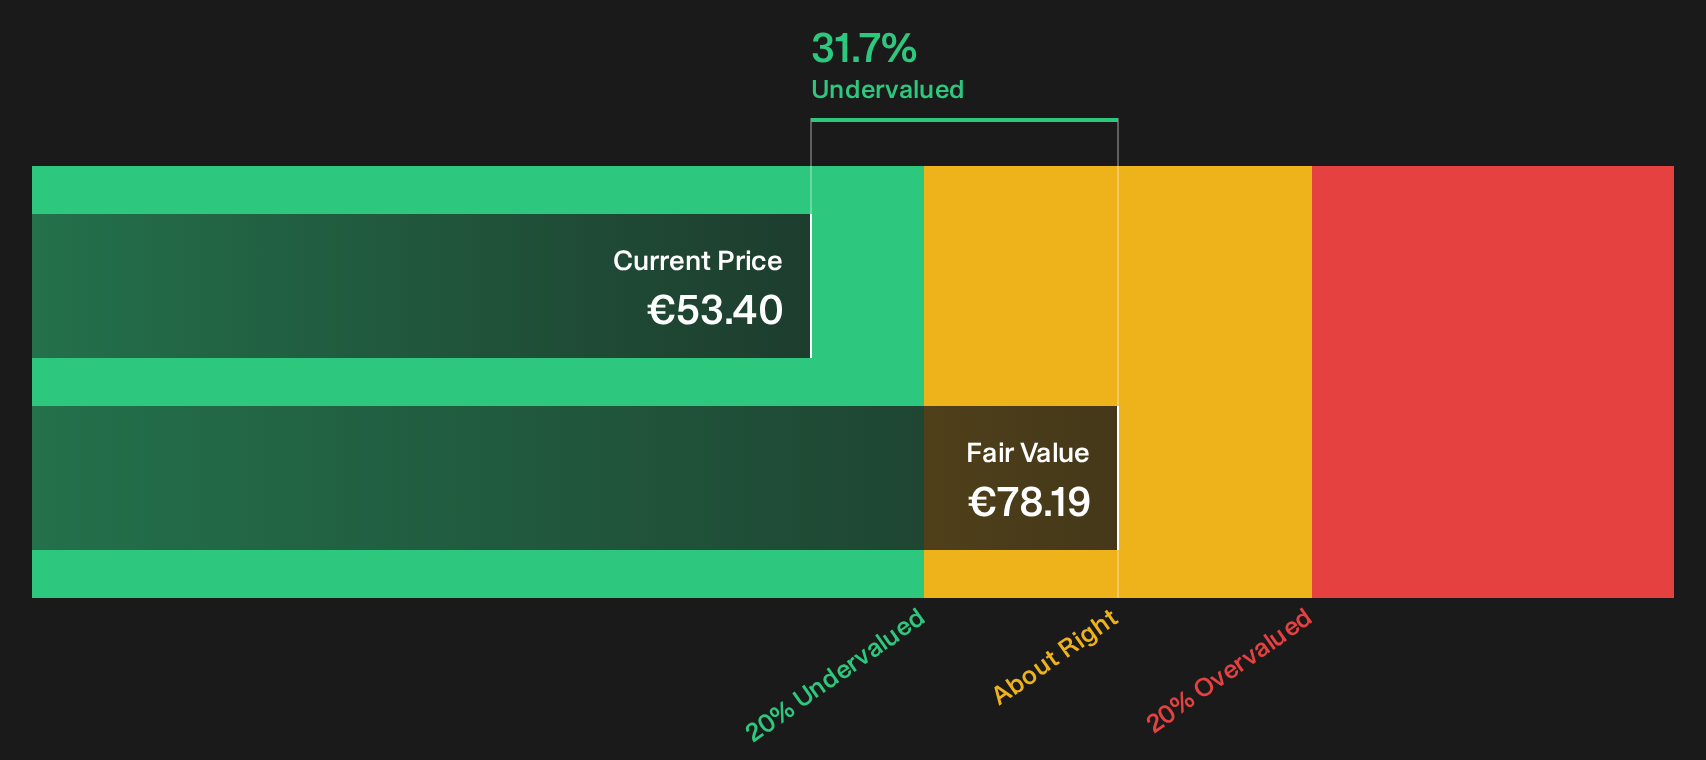
The StoxEurope work presents Melexis as heavily overpriced at €53.40. Our DCF model points in the opposite direction. It values the equity at €78.19 per share, which frames the current quote as trading 31.7% below that future cash flow estimate. Which set of assumptions appears more realistic to you?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of caution and optimism around Melexis feels familiar, consider acting while the data is fresh and test the thesis yourself by weighing the 2 key rewards and 2 important warning signs.
Looking for more Melexis sized investment ideas?
Do not stop your research at Melexis. The strongest portfolios usually come from testing multiple angles, so press your advantage and widen the opportunity set while this is top of mind.
- Target resilient income by scanning companies that offer durable yields and payout profiles through the 228 dividend fortresses.
- Spot potential value candidates early by reviewing a 225 high quality undervalued stocks that pair quality fundamentals with discounted pricing.
- Protect the downside by focusing on businesses with sturdier finances using a list of solid balance sheet and fundamentals (192 results) before the crowd catches up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com