
Is Centrus Energy (LEU) Still Cheap On Its Centrifuge Milestone And 2040 Backlog?
Centrus Energy (LEU) just checked off a key milestone for investors. The company shipped its first new centrifuge ahead of schedule and locked in a larger uranium enrichment backlog that now extends through 2040.
The centrifuge shipment lands at a time when Centrus Energy’s 1-day share price return of 17.49% contrasts sharply with a year-to-date share price decline of 61.61% and a 1-year total shareholder return that is down 64.44%, even though the 3-year total shareholder return is more than double where it was three years ago. Recent earnings, fresh revenue guidance for 2026 in the US$450 million to US$500 million range, heavier capital plans for its enrichment build out, and a new shelf registration filing together help explain why the latest move looks more like a sharp bounce in sentiment rather than a smooth, uninterrupted uptrend.
Spot similar nuclear build-out stories and compare Centrus Energy with a hand picked set of 17 nuclear energy infrastructure stocks.Centrus Energy now pairs a long dated enrichment backlog with a share price that has swung hard in both directions this year. The real tension is whether that stronger business is already fully reflected in today’s valuation.
Most Popular Narrative: 45% Undervalued
Centrus Energy closed at $104.60, while the most followed valuation storyline pins fair value closer to $190. That gap frames the stock as a pure play on whether fuel bottlenecks matter more than recent earnings pressure.
Centrus Energy (LEU) offers the most direct public-market exposure to U.S. HALEU production, a critical bottleneck for advanced nuclear deployment.
HALEU fuel scarcity could constrain next-gen reactor rollouts, making LEU's enrichment capabilities strategically vital as AI-driven electricity demand surges.
See why 44 investors see Centrus Energy as 45% undervalued.
Result: Fair Value of $190 (UNDERVALUED)
Still, the HALEU story around Centrus Energy could unravel if government support slows or if rival enrichment projects scale faster than expected.
Find out about the key risks to this Centrus Energy narrative.
Another View: Centrus Energy Through The P/E Lens
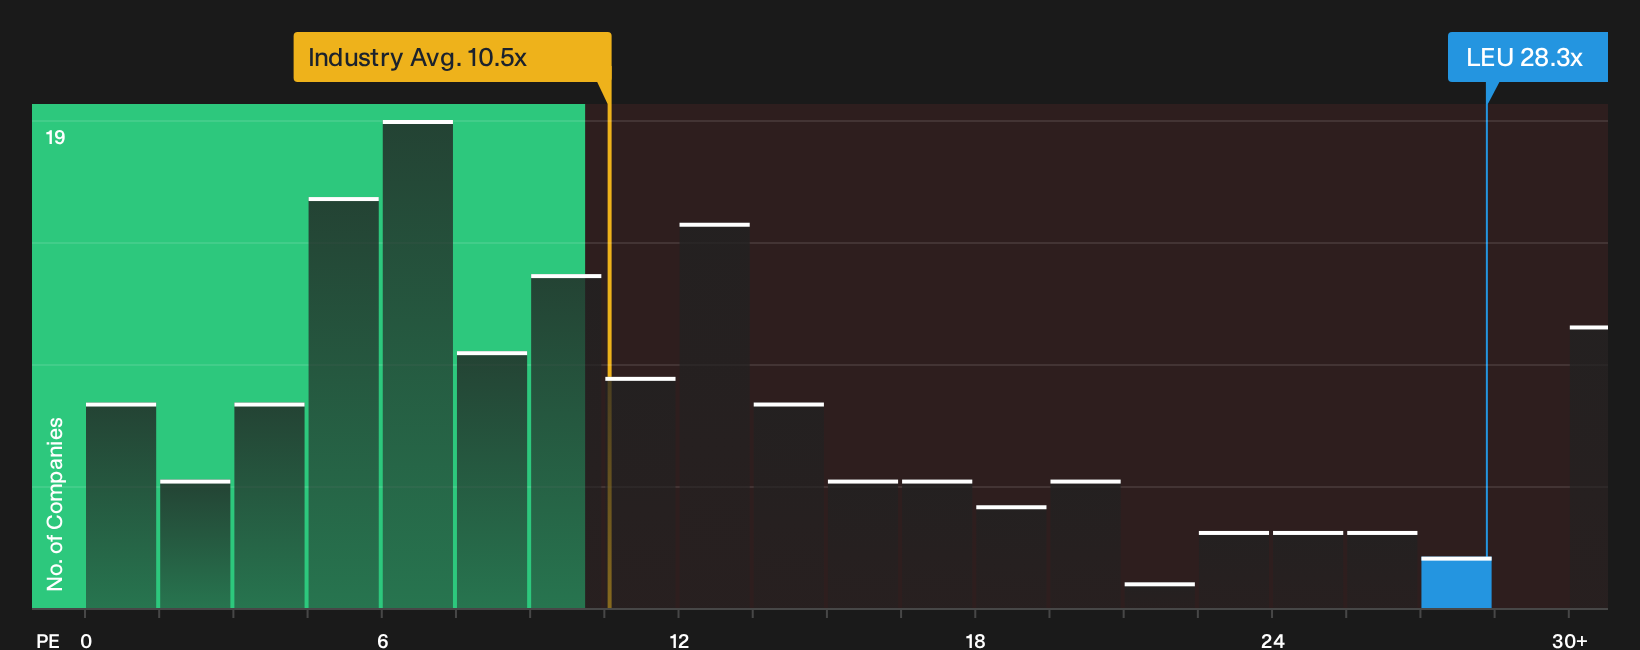
The fair value story around Centrus Energy points to $190, yet the P/E picture tells something very different. At $104.60, the stock trades on a 28.3x P/E, compared with 23.2x for direct peers and 10.5x for the wider US Oil and Gas industry. The gap versus an estimated fair ratio of 7.9x suggests investors are already paying a premium for the HALEU narrative. That raises a simple question: How comfortable are you paying above market and above fair ratio levels for this kind of earnings profile?
For a closer look at how this earnings multiple stacks up against peers and the fair ratio, our breakdown goes deeper into the numbers See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big upside stories always sound tempting, yet the real edge comes from testing the thesis against the numbers yourself before momentum shifts again. Take a closer look at the 3 important warning signs.
Looking for more Centrus Energy style ideas?
If Centrus Energy has sharpened your focus on where capital goes next, do not stop at one ticker when the wider opportunity set is this rich.
- Target resilient upside by scanning a curated spread of companies that look undervalued on cash flows and balance sheet strength using the 38 high quality undervalued stocks.
- Prioritize capital preservation and smoother ride potential by filtering for businesses that show up in the 31 resilient stocks with low risk scores.
- Hunt for future leaders before the crowd catches on by working through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com