
Q3 Earnings Might Change The Case For Investing In Rubis Stock (ENXTPA:RUI)
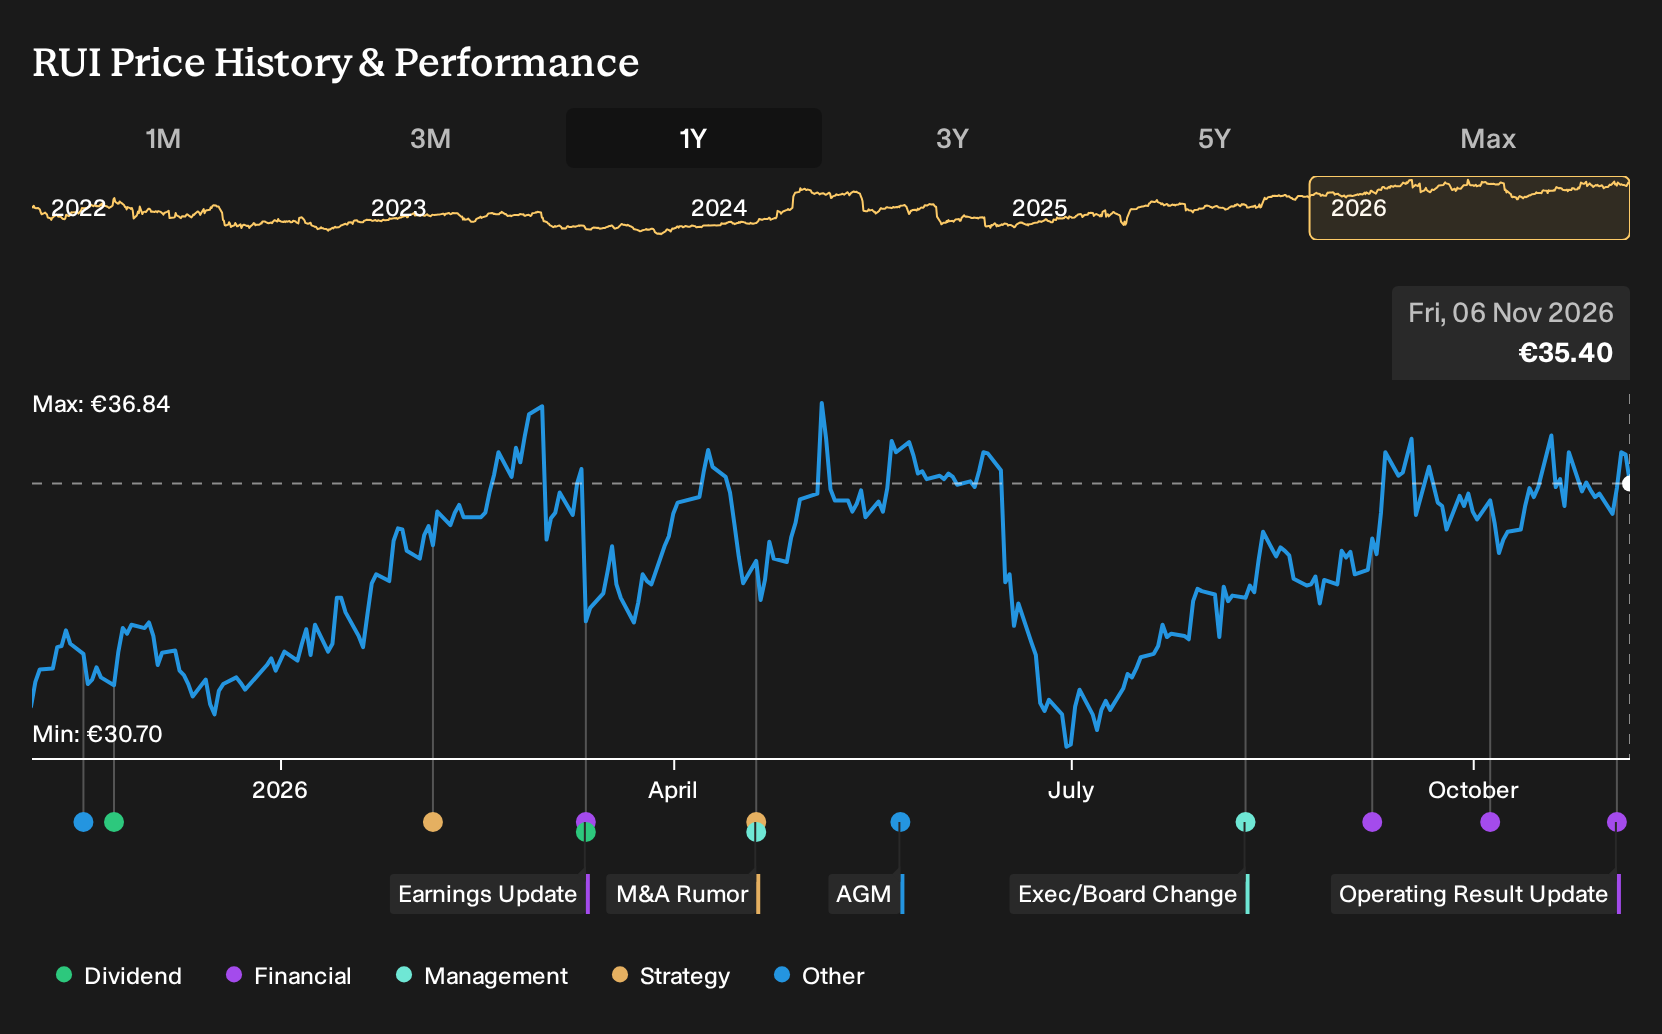
- Rubis released third quarter 2026 figures that show sales of €2,275 million compared with €1,580 million a year earlier, nine month revenue of €6,342 million versus €4,855 million, and Photosol electricity production of 286 GWh against 197 GWh.
- The group paired this operational update with news of a 1.5 GWp Photosol portfolio, a partial sale of the Creil solar park, and a proposed shift to French limited company status. Together these elements highlight an active renewables build out and a governance refresh.
- We will now look at how Rubis' investment narrative could be influenced by the expanding Photosol portfolio and related transaction activity.
Scan how Rubis' latest trading update compares with peers by reviewing hand picked list of solid balance sheet and fundamentals (192 results) in similar capital intensive sectors.
Rubis Investment Narrative Recap
To own Rubis, you need to be comfortable with a fuel distributor that is trying to grow a renewable power arm while still relying heavily on Africa and the Caribbean for earnings. The latest trading update keeps that story intact. Higher sales and larger Photosol output support the idea that operating momentum is still there in the near term.
The key short term catalyst remains execution on the 1.5 GWp Photosol pipeline, moving from secured to producing assets. The biggest risk still sits in emerging market exposure and currency swings, together with higher debt and upfront renewable capex. This update does not materially change those risk reward anchors.
The most relevant new data point for that catalyst is the Photosol production figure. Electricity output of 286 GWh in the third quarter, compared with 197 GWh a year earlier, gives you a clearer sense of how Rubis is turning that secured capacity into actual generation and Power EBITDA over time.
This sits alongside the 1.5 GWp portfolio and the partial sale of the Creil solar park. Together these point to more capital going into power projects while recycling some cash. For you as a shareholder, the execution watchpoints are project delivery, uptime, contract performance and whether this build out offsets FX, inflation and country risk in Rubis key fuel markets.
Rubis' narrative projects €8.1 billion revenue and €384.8 million earnings by 2029. This assumes 3.6% yearly revenue growth and an earnings increase of about €48 million from €336.8 million today.
Uncover how Rubis' fair value indicates a 14% potential upside to its current price. This suggests a discount that may not last much longer.
Exploring Other Perspectives
Some analysts focus less on FX risk and more on Photosol as a possible upside swing factor for Rubis. Before this trading update, the most optimistic forecasts were already pencilling in revenue of about €8.7b and earnings of roughly €426.0 million by 2029. After the latest numbers, those bullish narratives may shift again, so it is useful to compare several viewpoints before deciding what best fits your own expectations.
Explore 3 other Rubis fair value estimates, including one that suggests as much as 53% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rubis research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rubis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rubis' overall financial health at a glance.
Looking For More Investment Ideas Beyond Rubis?
Once you have a view on Rubis, it can help to stress test that thesis against other businesses with different balance sheets, risk profiles and income streams using the Simply Wall St Screener.
- If capital preservation is high on your list, consider resilient businesses screened for lower risk profiles through the 207 resilient stocks with low risk scores.
- If income is the priority, check out companies with stronger yields and payout histories by reviewing the 228 dividend fortresses.
- If you want to focus on quality first, scan for companies with healthier leverage and fundamentals via the 574 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com