
Rogers (ROG) Could Be 37% Undervalued Following Strong Q3 Earnings Guidance
Rogers (ROG) surprised the market with stronger third quarter earnings and fresh fourth quarter sales guidance, yet the stock dropped sharply, forcing investors to reassess how near term expectations line up with longer term ambitions.
Rogers is coming off a sharp pullback, with a 7 day share price return of down 8.34% and a 30 day move of down 17.26%. However, the year to date share price return of 32.61% and 1 year total shareholder return of 44.71% still point to earlier momentum that has started to fade.
Compare Rogers with a curated group of peers riding similar AI and EV themes by scanning the 53 AI infrastructure stocks that are shaping data center and connectivity build outs.
After a 44.71% 1 year total return that has started to unwind on the latest selloff, the question around Rogers now is simple. Is meaningful upside still ahead, or has most of the move already happened before the valuation work even starts?
Most Popular Narrative: 37% Undervalued
Rogers closed at $121.96 while the most widely followed narrative centers on a fair value of $193.33, creating a wide gap that hinges on execution in high margin growth areas.
Expansion into AI data center connectivity and cooling through next generation PTFE-based laminates that already meet and exceed M9 performance requirements, with a path to M10, and direct-to-chip microchannel coolers now being prototyped with several major AI chip and data center customers, alongside management’s expectation that these adjacencies contribute meaningfully to roughly US$450 million of targeted incremental revenue by 2030, provides a potential new leg of growth and margin mix improvement.
Find out how 2 investors see Rogers as 37% undervalued.
Result: Fair Value of $193.33 (UNDERVALUED)
Still, if the new ceramic substrate facility stays underutilized or supply chain setbacks keep recurring, the bullish Rogers narrative could unravel more quickly than expected.
Find out about the key risks to this Rogers narrative.
Another View: Rogers Looks Expensive On Earnings
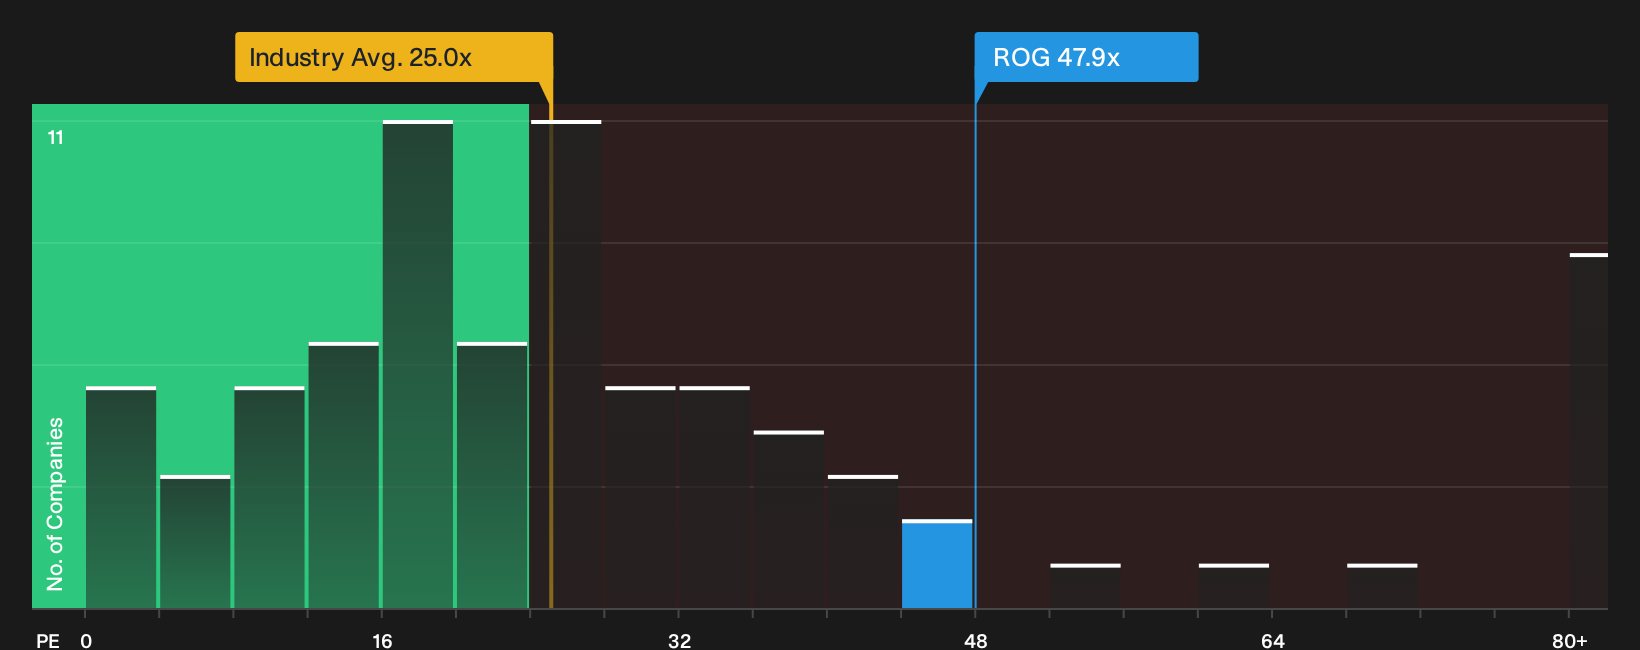
The story changes once the focus shifts from that $193.33 fair value to what investors are actually paying for Rogers today. The stock trades at a P/E of 47.9x, which is far richer than the US Electronic industry at 25.1x, the peer average at 33.7x, and even the fair ratio of 30.7x that the market could gravitate toward over time. If the investment case leans heavily on rapid profit growth, how comfortable are you paying such a premium entry price?
See what the numbers say about this price in more detail by checking the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Rogers is clearly split, so move quickly from reading headlines to testing the numbers yourself and pressure testing every assumption. To see what the current optimism is built on, review the 3 key rewards.
Looking for more Rogers investment ideas?
If you stop with Rogers, you miss the bigger picture. Use the Simply Wall Street Screener to line up fresh ideas before the crowd moves.
- Target resilient value by scanning the 38 high quality undervalued stocks that pair stronger balance sheets with pricing that still looks reasonable.
- Protect against nasty surprises by reviewing the 31 resilient stocks with low risk scores that score well on financial strength and earnings stability.
- Get ahead of the next potential story by checking the 19 high quality undiscovered gems before they appear on everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com