
How Investors Are Reacting To Energy Fuels (TSX:EFR) Rare Earth Expansion Plans
- Energy Fuels reported Q3 2026 sales of US$29.18 million and a net loss of US$52.21 million, and appointed veteran mining executive Jeffrey Olsen to its Board and Audit Committee.
- The firm is pushing deeper into rare earth integration, using the Australian Strategic Materials acquisition and planned White Mesa expansions to build a more complete supply chain from ore to advanced materials.
- We will now look at how Energy Fuels' integrated rare earth buildout, including the White Mesa expansion, could reshape its investment narrative.
Scan beyond Energy Fuels and consider other nuclear and rare earth companies on our hand picked list of 17 nuclear energy infrastructure stocks.
Energy Fuels Investment Narrative Recap
To own Energy Fuels, you need to believe the rare earth and uranium buildout at White Mesa and across the portfolio can eventually support a more balanced mix of revenue and costs. The Q3 2026 results, with US$29.18 million in sales and a net loss of US$52.21 million, underline that this is still a heavy investment phase rather than a profit story.
The key near term catalyst remains execution on the rare earth integration plan at White Mesa and related projects, including staying on schedule and on budget. The biggest risk is that ongoing losses like the US$96.43 million for the first nine months of 2026 persist while capital spending remains high. That could pressure funding options and slow the buildout.
The most relevant recent update for that thesis is management’s decision to start Phase 1B and 1C heavy rare earth processing expansions at the White Mesa Mill, targeting completion in early 2028. That ties directly into the aim of turning Energy Fuels into a more complete rare earth supplier, from ore through to higher value oxides and advanced materials.
That same announcement highlighted sizable growth capex and reliance on anticipated government funding, alongside a final investment decision on the Donald Project expected by year end. For you as an investor, the catalyst is disciplined project delivery and securing that financing on acceptable terms. The operational risk sits in cost control, construction execution and integrating the Australian Strategic Materials assets without further widening losses.
Energy Fuels' narrative projects US$563.3 million revenue and US$194.1 million earnings by 2029. This rests on analysts assuming 74.6% yearly revenue growth and an earnings swing of about US$275.8 million from earnings today of a US$81.7 million loss.
Uncover why Energy Fuels' fair value indicates a 306% potential upside to its current price that could narrow quickly.
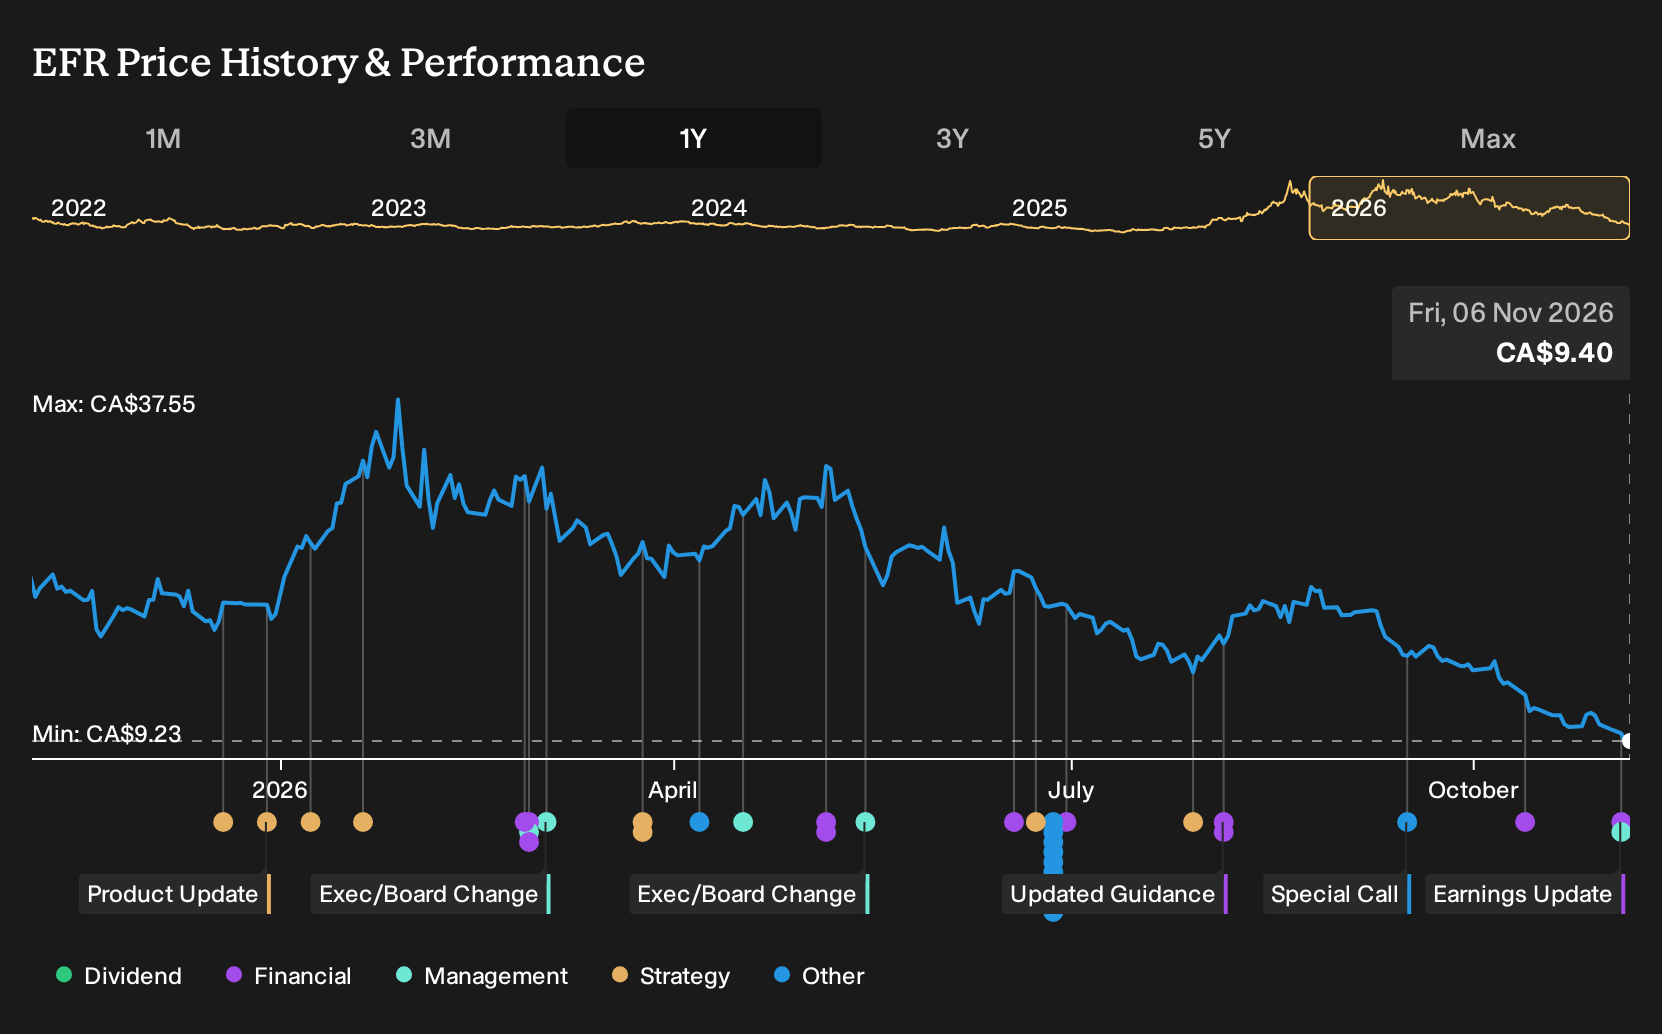
Exploring Other Perspectives
Another lens focuses on execution risk across Energy Fuels' entire mine to magnet chain, rather than just White Mesa schedules. The most cautious analysts were working off pre news forecasts of about US$380.0 million in 2029 revenue and US$166.4 million in earnings. That is still optimistic, yet far below the top forecasts, so you can compare several competing stories and decide which feels more realistic as this latest update filters into future models.
Explore 4 other Energy Fuels fair value estimates, including one that suggests it could be worth just CA$30.00!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Energy Fuels research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Energy Fuels. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Energy Fuels' overall financial health at a glance.
Looking For More Ideas Beyond Energy Fuels?
Once you have a view on Energy Fuels, it can help to cross check that opinion against other opportunities that fit different risk and return profiles. The Simply Wall St Screener lets you move quickly from one focused list of stocks to another so you can see how Energy Fuels compares across quality, balance sheet strength and income potential.
- For investors who want potential upside in smaller companies but still care about balance sheets and fundamentals, start with this 16 elite penny stocks with strong financials and see which ones meet your risk tolerance.
- If capital preservation and stability sit higher on your priority list, filter for companies with steadier profiles through a 9 resilient stocks with low risk scores that narrows the field to more resilient options.
- For a blend of quality and mispricing potential, use the 7 high quality undervalued stocks to focus on businesses where fundamentals and current pricing appear out of sync.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com