
Raised Outlook Could Be A Big Moment For ITT Stock (ITT)
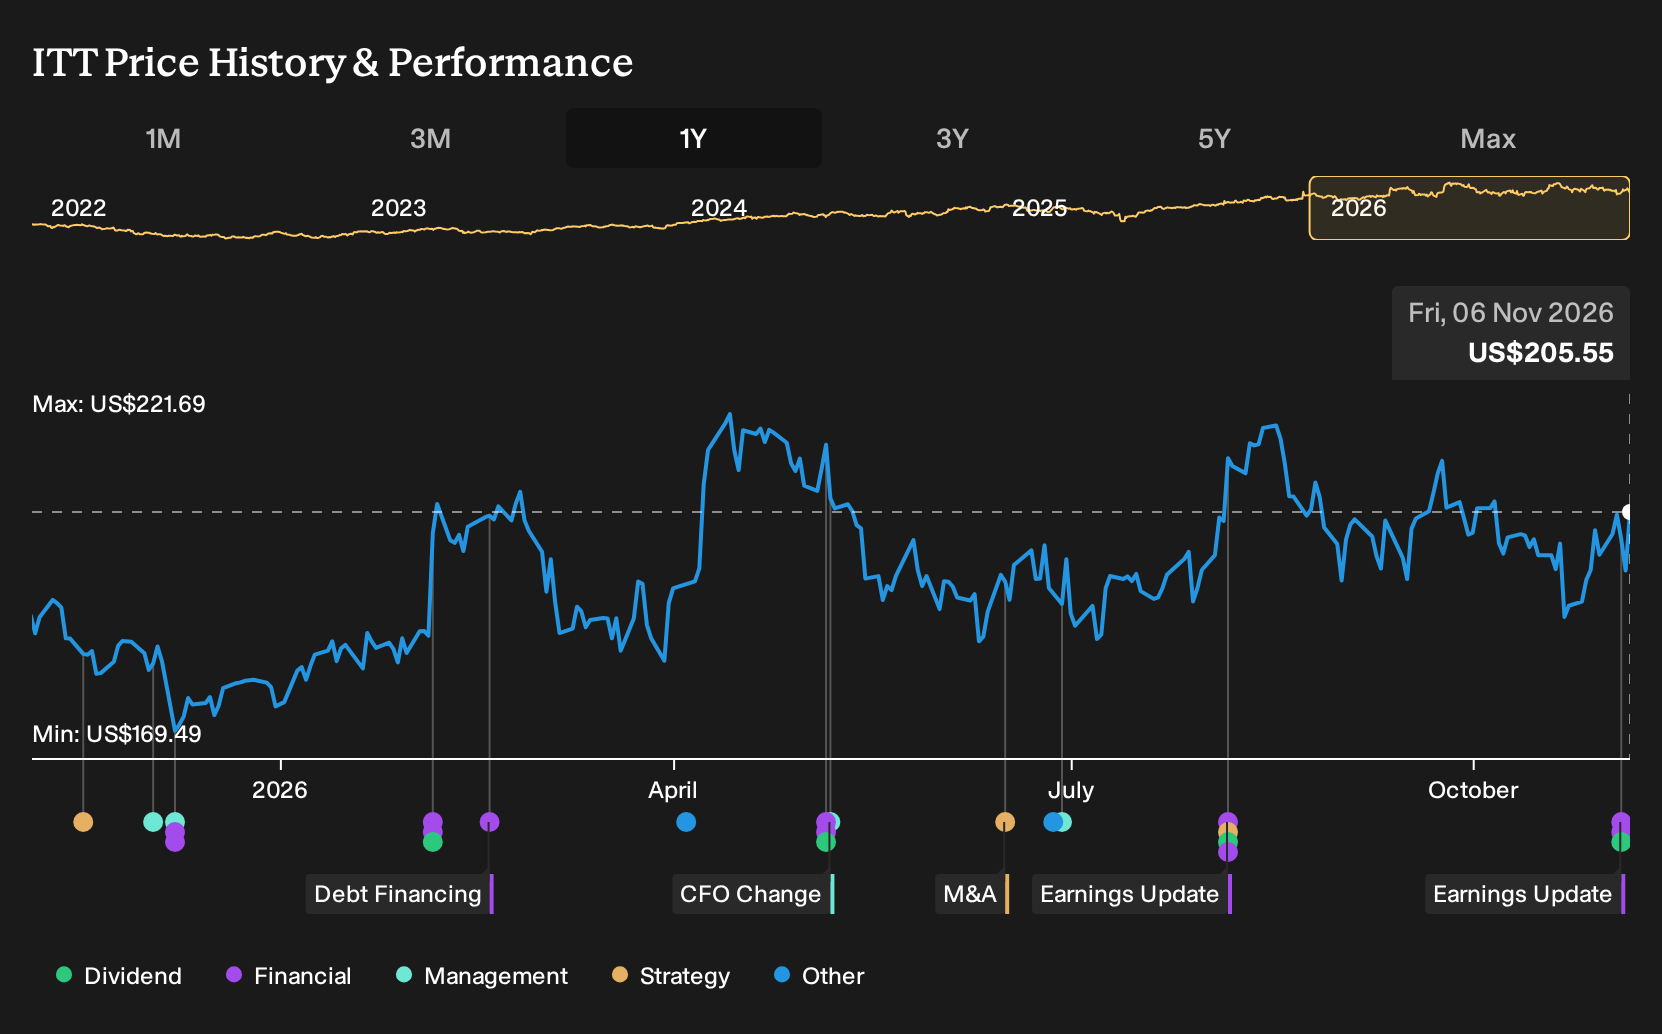
- ITT Inc. reported third quarter 2026 sales of US$1,440.6 million with net income of US$123.6 million, raised full year guidance, and affirmed a US$0.386 quarterly dividend payable on December 31, 2026.
- The higher outlook for 2026 organic and total revenue, earnings, and operating margin reflects management’s stated expectations for SPX FLOW integration benefits and cost synergies.
- The focus now turns to how ITT's raised full year guidance could influence the longer term investment narrative around earnings power.
Compare ITT's raised guidance story with other potential compounders by scanning our curated list of 38 high quality undervalued stocks that pair solid cash generation with disciplined balance sheets.
ITT Investment Narrative Recap
To own ITT, you need to believe that a larger, more complex industrial platform can steadily turn its expanded backlog, including SPX FLOW, into higher earnings and cash generation. The raised 2026 outlook for organic and total revenue, EPS and operating margin points to execution that is tracking ahead of earlier expectations rather than a one quarter anomaly.
The near term catalyst is clear: management delivery against integration and cost synergy goals that support the upgraded guidance. The biggest risk is project and backlog timing, especially in long cycle flow and marine work, which could still create uneven quarterly earnings even if the overall demand picture remains constructive.
The most relevant update is the new 2026 guide that calls for 7% to 9% organic revenue growth, 41% to 43% total revenue growth, EPS of US$4.65 to US$4.73 and operating margin of 13.3% to 14.1%. That framework gives you a concrete yardstick to judge whether ITT is turning its enlarged portfolio into better profitability.
How those numbers intersect with catalysts such as SPX FLOW integration and margin catch up at underperforming sites will likely drive sentiment. Any slippage in synergy capture, or renewed pressure on automotive friction pricing, would matter for that margin range, while steady progress against the targets would help support the longer term earnings narrative.
ITT's current analyst framework points to revenue of US$6.5b and earnings of US$802.9 million by 2029, based on an assumed yearly top line expansion of 11.3% and an earnings increase of roughly US$381 million from the US$421.6 million reported today.
Uncover how ITT's fair value indicates a 26% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One alternate view on ITT focuses on Middle East order deferrals as the key risk. The lowest analysts were previously penciling in revenue of about US$6.7b and earnings of US$653.5 million by 2029, far below the US$802.9 million consensus path. That more cautious script may shift after this guidance news, so investors may wish to explore both narratives.
Explore another ITT fair value estimate, including one that suggests it could be worth just $250.82!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ITT research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ITT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ITT's overall financial health at a glance.
Looking For More Ideas Beyond ITT?
If ITT has sharpened your thinking about earnings power and guidance, it can help to set it alongside other candidates that fit different roles in your portfolio. Use the Simply Wall St Screener to widen your field of vision and test where ITT belongs in your watchlist.
- For investors who want potential mispricings with quality behind them, scan through a curated set of 19 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- If capital preservation and steadier profiles matter more to you than chasing every upswing, compare ITT with a 31 resilient stocks with low risk scores that score well on resilience and financial strength.
- Income focused readers can cross check ITT against a 7 dividend fortresses that combine higher yields with balance sheets built to support regular payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com