
Walker & Dunlop (WD) Holds Its Dividend As Losses Put Valuation Back In Focus
Dividend, loss and more liquidity arrive together for Walker & Dunlop
Walker & Dunlop (WD) just paired a third quarter net loss tied to legacy loan issues and fraud related write downs with a maintained dividend and a larger revolving credit facility.
Recent trading shows a sharp rebound in momentum over the past week and month, with a 7 day share price return of 12.24% and a 30 day share price return of 18.30%, even though the year to date share price return is down 33.50% and the 1 year total shareholder return is down 40.46%. This signals that investors have started to reassess Walker & Dunlop after the fraud related write downs, dividend affirmation and expanded credit lines, but are still pricing in meaningful longer term damage.
Spot opportunities beyond Walker & Dunlop by scanning a curated 31 resilient stocks with low risk scores that have weathered recent volatility with stronger risk profiles and steadier performance histories.Walker & Dunlop now trades below the average analyst target after a sharp bounce, while still carrying fresh loss headlines. Is the discount compensation for risk, or is it a sign that caution has gone too far?
Most Popular Narrative: 19% Undervalued
Walker & Dunlop closed at $39.05 against a most-followed fair value estimate of about $48.33, so the narrative points to a meaningful valuation gap that hinges on how refinancing flows and fee income evolve over time.
Ongoing refinancing and construction activity in a higher rate setting, including recent large multifamily, mixed use, office and workforce housing deals in Miami, Manhattan, Jersey City and other markets, keeps Walker & Dunlop well positioned to generate fee income from a sustained recapitalization cycle that can support revenue and earnings.
See why 1 investors see Walker & Dunlop as 19% undervalued.
Result: Fair Value of $48.33 (UNDERVALUED)
Still, the Walker & Dunlop story only holds if refinancing volumes remain healthy and underwriting does not leave it exposed to weaker multifamily and office assets.
Find out about the key risks to this Walker & Dunlop narrative.
Another View: DCF Flags A Very Different Walker & Dunlop Story
The analyst fair value narrative paints Walker & Dunlop as about 19% undervalued at $48.33 versus $39.05. The SWS DCF model points the other way, with an estimated future cash flow value of $20.15. That implies the current quote is rich, not cheap. Which framework do you trust more for a lender tied to complex commercial real estate cycles?
Our DCF model is heavily driven by long range cash flow assumptions and discount rates that can swing a lot as the outlook for refinancing volumes, loss content and funding costs shifts. Look into how the SWS DCF model arrives at its fair value.
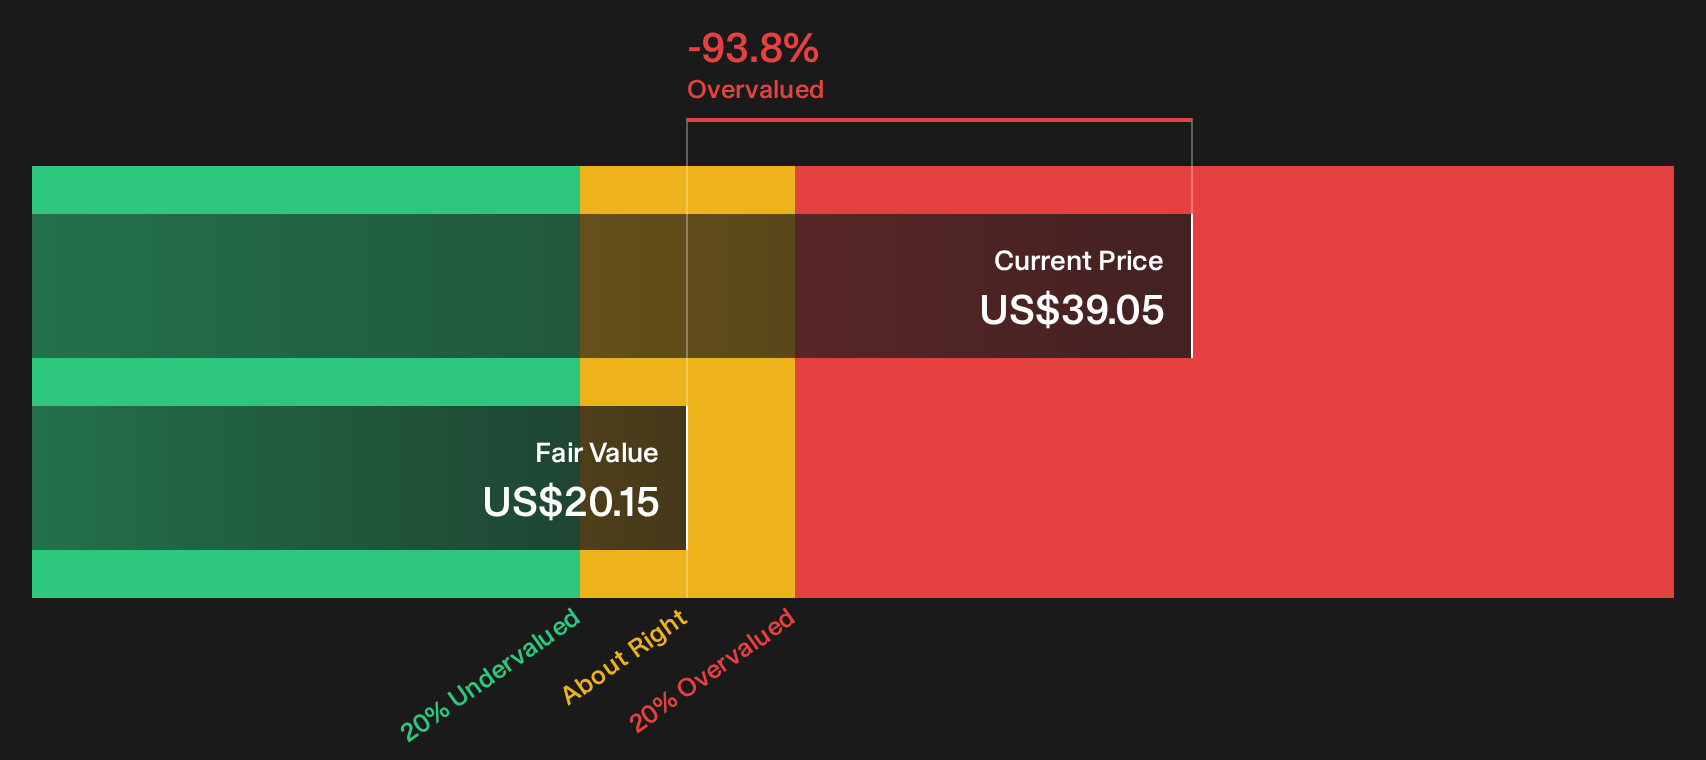
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Walker & Dunlop for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Walker & Dunlop so far. If you want to move fast and build your own view from the ground up, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Walker & Dunlop?
Do not let your research stop with Walker & Dunlop. A few focused stock lists can surface opportunities you have not even considered yet.
- Target resilience first by reviewing a curated 31 resilient stocks with low risk scores that aims to hold up better when conditions turn choppy.
- Hunt for potential bargains by scanning a 38 high quality undervalued stocks that combines quality fundamentals with prices that may not fully reflect them yet.
- Build income potential by focusing on a 7 dividend fortresses that offers stronger yields while still keeping an eye on financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com