
How Earnings Guidance Update At Hilton Worldwide Holdings (HLT) Has Changed Its Investment Story
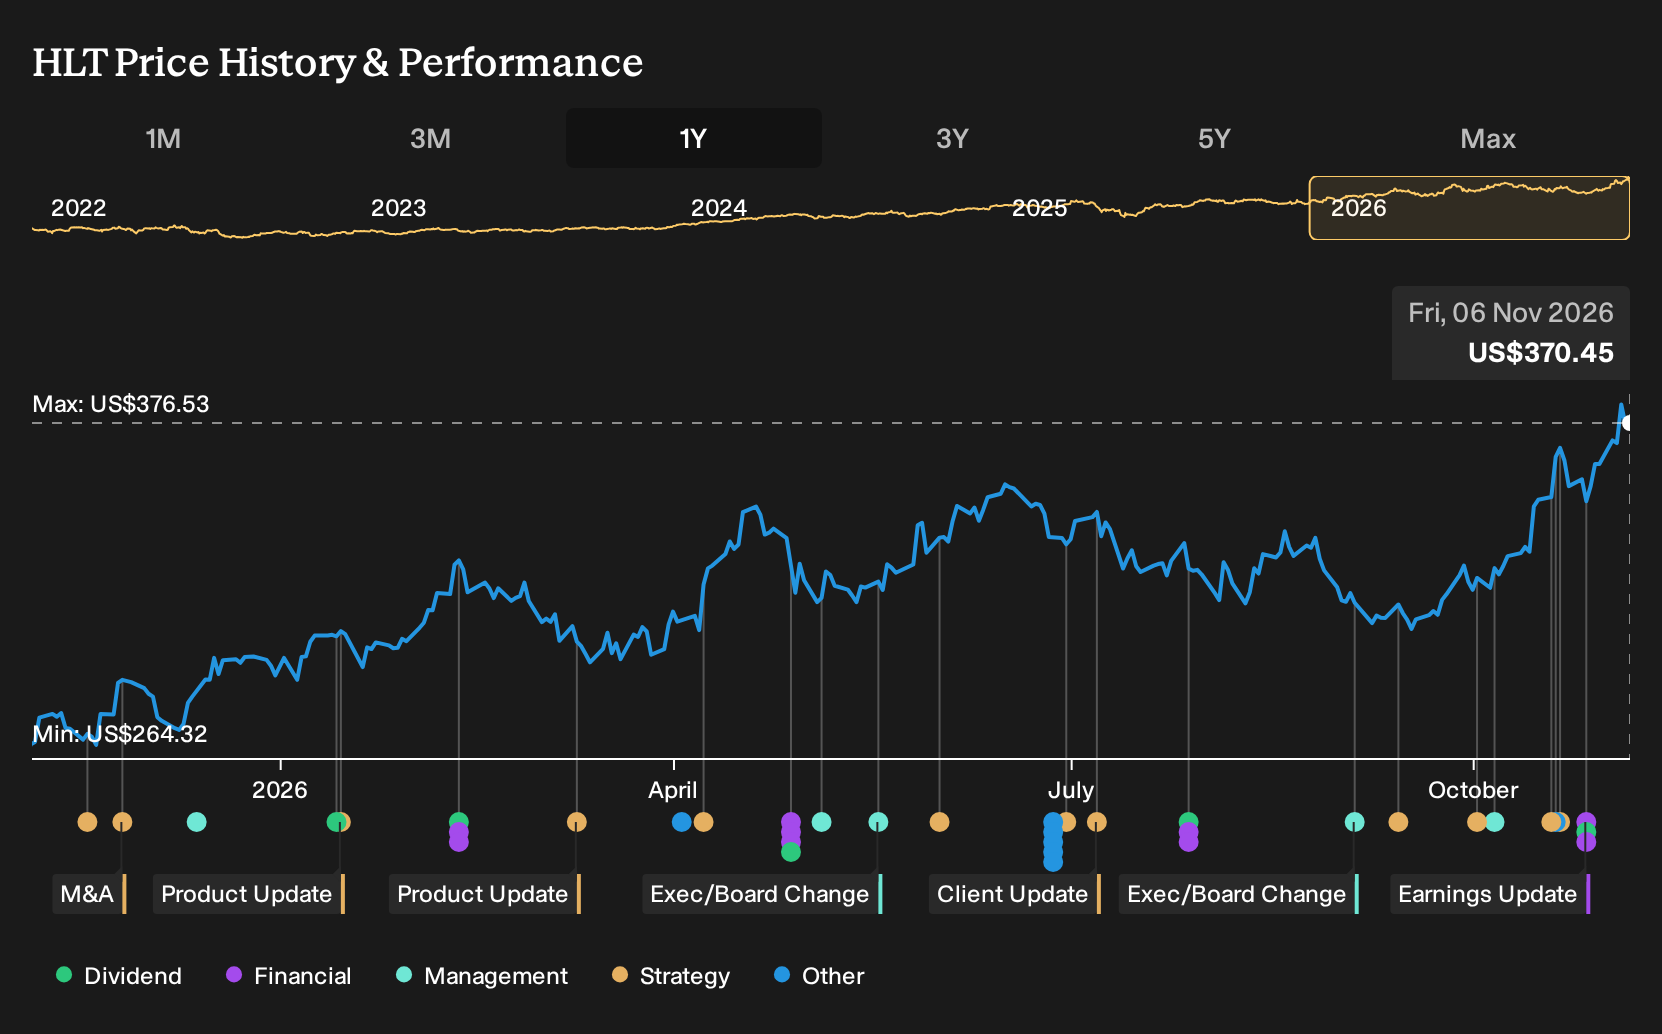
- Hilton Worldwide Holdings reported higher third quarter 2026 earnings per share compared with a year earlier, issued detailed EPS and net income guidance for the fourth quarter and full year 2026, affirmed a US$0.15 quarterly dividend, and was added to the NASDAQ Composite Index, events which all occurred before early November 2026.
- The combination of stronger recent EPS figures and fresh earnings guidance gives investors more clarity on Hilton Worldwide Holdings' fee based model and profit outlook. In addition, the index inclusion and ongoing dividend indicate that management is pairing growth ambitions with continued capital return.
- We will now look at how Hilton Worldwide Holdings' investment narrative is influenced by its higher third quarter earnings per share.
Scan opportunities with a similar earnings and income focus as Hilton Worldwide Holdings by reviewing our hand picked 38 high quality undervalued stocks, which combines established cash generation with disciplined balance sheets.
Hilton Worldwide Holdings Investment Narrative Recap
To own Hilton Worldwide Holdings, you need to be comfortable with a fee driven hotel model that depends on converting its large pipeline into opened rooms while keeping owners profitable. The recent third quarter EPS figures and 2026 guidance give more visibility on near term earnings. In the short term, the key swing factor remains how resilient global travel demand stays across regions with very different RevPAR trends.
The biggest risk still sits in softer markets such as the Middle East and China, where weaker demand or pricing can dilute system wide fee growth. Renovation heavy owned assets like Munich Park, Amsterdam and Tokyo also matter. If closures or refurbishments run longer or reopen on less favorable economics, segment level profits could come under pressure.
The fresh 2026 earnings guidance is the clearest piece of information to work with right now. Management expects fourth quarter diluted EPS of US$2.25 to US$2.31 and net income of US$508m to US$522m, with full year diluted EPS of US$8.38 to US$8.44 and net income of US$1.909b to US$1.923b. Those numbers help you judge whether Hilton Worldwide Holdings is converting its pipeline and cost initiatives into actual profit.
For investors watching catalysts, this guidance ties directly into questions around RevPAR resilience, owner margins and the drag from renovations. It lets you track how fee revenue holds up against regional softness and whether cost programs like RISE show through in earnings. If reported results stay close to these ranges, it suggests the current expansion plan and digital investments are at least aligning with the operational targets management has put on paper.
Hilton Worldwide Holdings' current analyst story points to US$16.1b in revenue and US$2.7b in earnings by 2029, based on consensus estimates. That path assumes revenue grows at about 46.0% per year and earnings rise by roughly US$1.0b from about US$1.7b today to the projected level in 2029.
Discover why Hilton Worldwide Holdings' fair value is essentially in line with its current price.
Exploring Other Perspectives
The two fair value estimates for Hilton Worldwide Holdings from the Simply Wall St Community span roughly US$247 to US$362 per share, which is a wide gap for a small sample. You can weigh those views against risks around weaker RevPAR in the Middle East and China and renovation drag, which could influence how future earnings track guidance. Investor opinions clearly differ, so it helps to explore several alternative viewpoints before deciding how Hilton Worldwide Holdings fits your portfolio.
Explore another Hilton Worldwide Holdings fair value estimate, including one that suggests there could be as much as 33% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Hilton Worldwide Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hilton Worldwide Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hilton Worldwide Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Hilton Worldwide Holdings?
Once you understand where Hilton Worldwide Holdings fits in your portfolio, it can help to line it up against other opportunities that share similar qualities or offer a different risk and income profile. The Simply Wall St Screener lets you quickly filter for businesses that match the traits you care about most, so you are not just reacting to headlines but building a watchlist that reflects your own criteria.
- If capital preservation is a priority, start with companies that show steadier risk profiles by reviewing our 31 resilient stocks with low risk scores, and see which stocks have characteristics that may better align with a more cautious approach.
- If reliable cash distributions matter to you, scan income focused opportunities through our 7 dividend fortresses, and compare those yields and track records against Hilton Worldwide Holdings' own dividend profile.
- If you want a balance of quality and sensible pricing, broaden your research with our list of solid balance sheet and fundamentals (25 results), and look for businesses that pair stronger financial footing with fundamentals you can understand.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com