
3 Edible Oils Stocks Investors Are Watching As Spain Holds Back Olive Oil Supply
Spain’s decision to withhold 12% of olive oil output until 2027, even as a bigger harvest pushes prices down and squeezes producer margins, has turned a niche commodity story into a global edible oils shake up. Price swings, storage risks and uneven rules across borders can reshape who wins and who loses. This article walks through three stocks exposed to that news and why the ripple effects matter for your portfolio.
The stocks below are just a starter pack, and the full screen surfaced 10 more non Spanish edible oils producers with equally compelling stories that are not covered here. To identify your own highest conviction angles on this theme, head straight into the Non‑Spanish Global Edible Oils Producers screener
Lesieur Cristal (CBSE:LES)
Overview: Lesieur Cristal is a Moroccan refined edible oils and olive oil producer supplying branded cooking oils, condiments, margarines, soaps and oilseed meals.
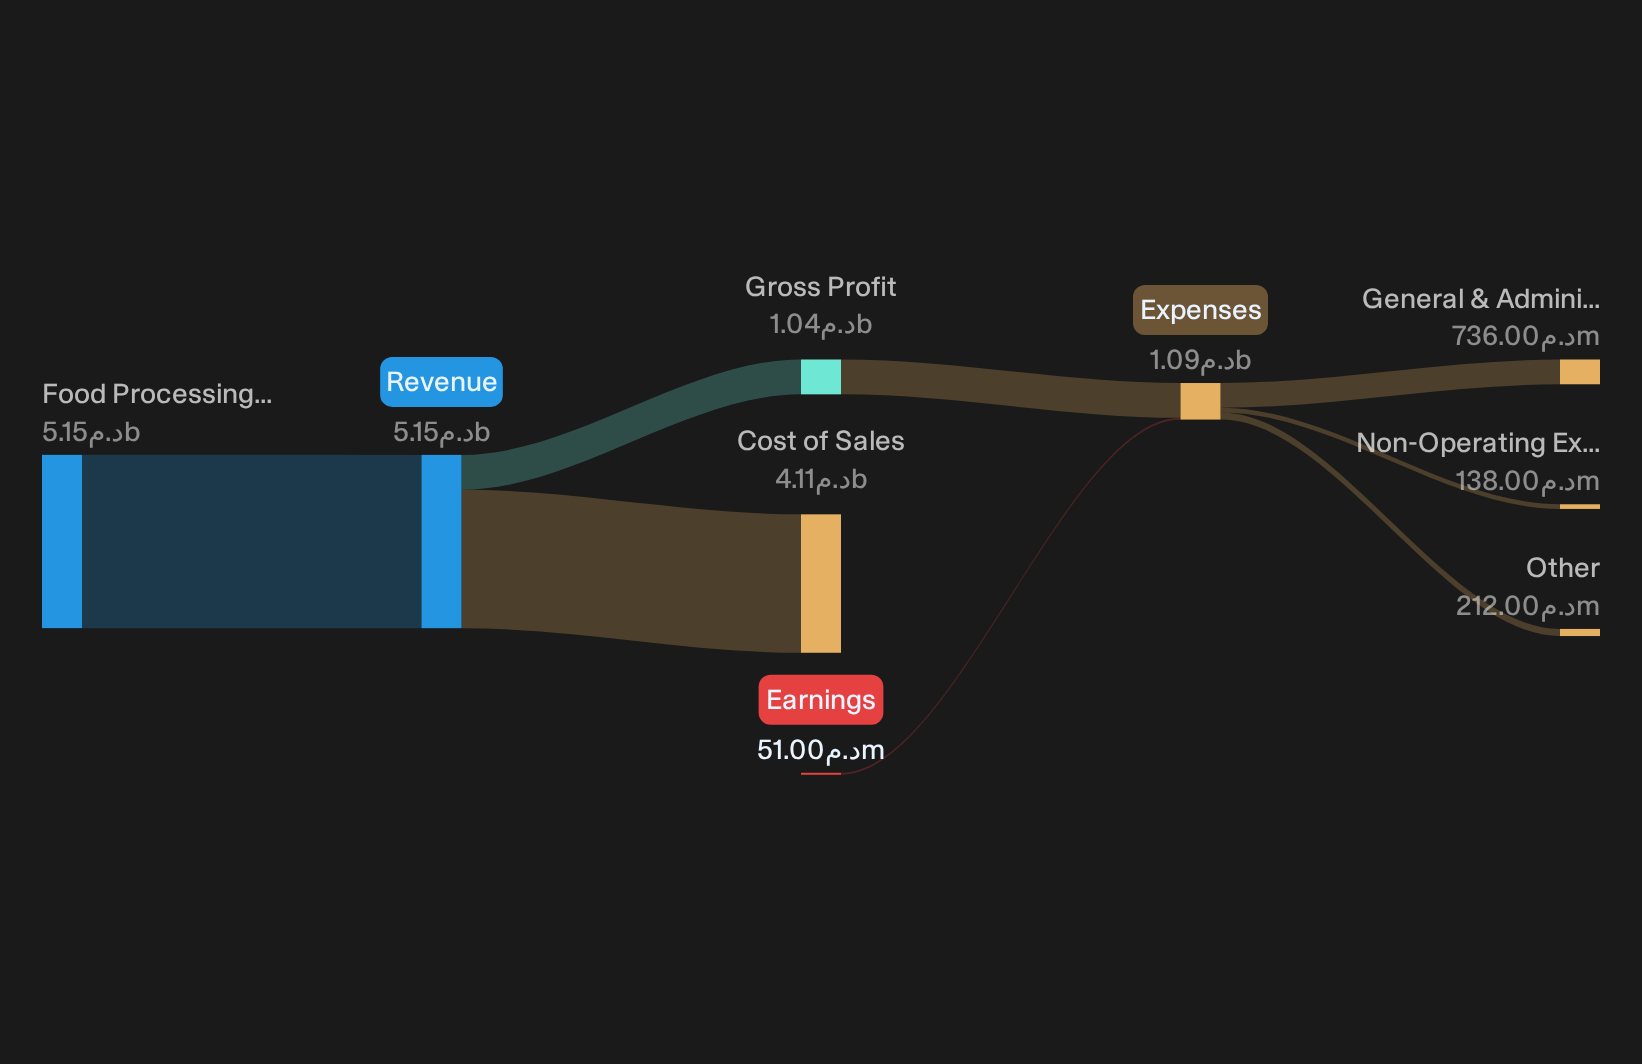
Operations: Lesieur Cristal generates MAD 5,148 million of revenue from food processing activities, all currently sourced from customers in Morocco.
Market Cap: MAD 8.1b
Lesieur Cristal sits squarely in the edible oils theme as a Moroccan supplier of olive, sunflower, rapeseed and soybean products to food and industrial buyers. The group offers a way to get exposure to non Spanish supply as policy limits and storage rules reshape global sourcing. Investor interest hinges on what happens when one unseen pressure on future pricing and margins finally bites.
When that pressure finally shows up in earnings, the 1 key reward and 1 important warning sign can help you see whether Lesieur Cristal’s opportunity outweighs the supply and pricing risk.
Cobram Estate Olives (ASX:CBO)
Overview: Cobram Estate Olives produces and markets branded extra virgin olive oil from integrated groves and processing assets in Australia and the U.S.
Operations: Cobram Estate Olives generates about A$180 million from Australian packaged goods and A$95 million from U.S. packaged goods, with small corporate eliminations.
Market Cap: A$1.3b
For the Non Spanish Global Edible Oils Producers theme, Cobram Estate Olives is the pure olive oil play that directly links grove scale outside Spain to how shoppers respond if supply, pricing and quality expectations shift away from Spanish barrels.
"Ongoing maturation and expansion of Californian groves, where around 37% of area is still immature and a further 1,260 hectares are planned for development in FY2027 and FY2028 with expected output above 11 million litres at full maturity, can lift U.S. segment revenue and support improved earnings over time."
What happens to Cobram Estate Olives margins and pricing power if a single assumption inside that U.S. growth plan proves too optimistic?
If that assumption is stretched, reading the full narrative for Cobram Estate Olives shows how Cobram Estate Olives could still accelerate value as grove output and pricing power decouple.

GrainCorp (ASX:GNC)
Overview: GrainCorp runs a global grain and oilseeds network that stores, trades and processes crops into edible oils, feeds and fuel inputs.
Operations: GrainCorp generates about A$5.5b from Agribusiness and A$2b from Nutrition & Energy, partly offset by A$389 million in eliminations.
Market Cap: A$1.5b
GrainCorp matters in this edible oils theme because its canola and other oilseed flows give buyers non Spanish options when olive oil supply or pricing feels unreliable. That leverage into substitution is where the more interesting part of the story starts.
"GrainCorp's record oilseed crush volumes and continued growth in Animal Nutrition volumes, including 1H26 sales of 390,000 tonnes and FY25 volumes that were 83% higher than FY21, point to ongoing expansion of processing and feed activities that can support future revenue and EBITDA."
What investors really need to watch is how one unresolved pressure on oilseed margins and demand shapes the payoff from that expanding processing footprint.
That pressure point is exactly where the full narrative for GrainCorp pulls the story together and shows how GrainCorp’s processing engine could turn volatility into accelerating upside.

Seeking Alternatives Before The Crowd?
Fresh themes move fast. Some tickers are building breakout momentum while others are still flying under the radar for now. Scan these ideas before sentiment drops and get in early.
- Spot under followed operators with real balance sheet strength by running the list of solid balance sheet and fundamentals (192 results). Consider it while these fundamentals are still ignored by most investors.
- Explore structural demand shifts by checking the curated 41 power grid technology and infrastructure stocks and see which infrastructure players might capture future grid upgrade momentum before it is fully priced in.
- Review high potential automation beneficiaries through the focused 90 robotics and automation stocks and track which production and logistics specialists could gain share while expectations are still muted.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com