
Earnings And Dividend Hike Could Be A Game Changer For CDW Stock (CDW)
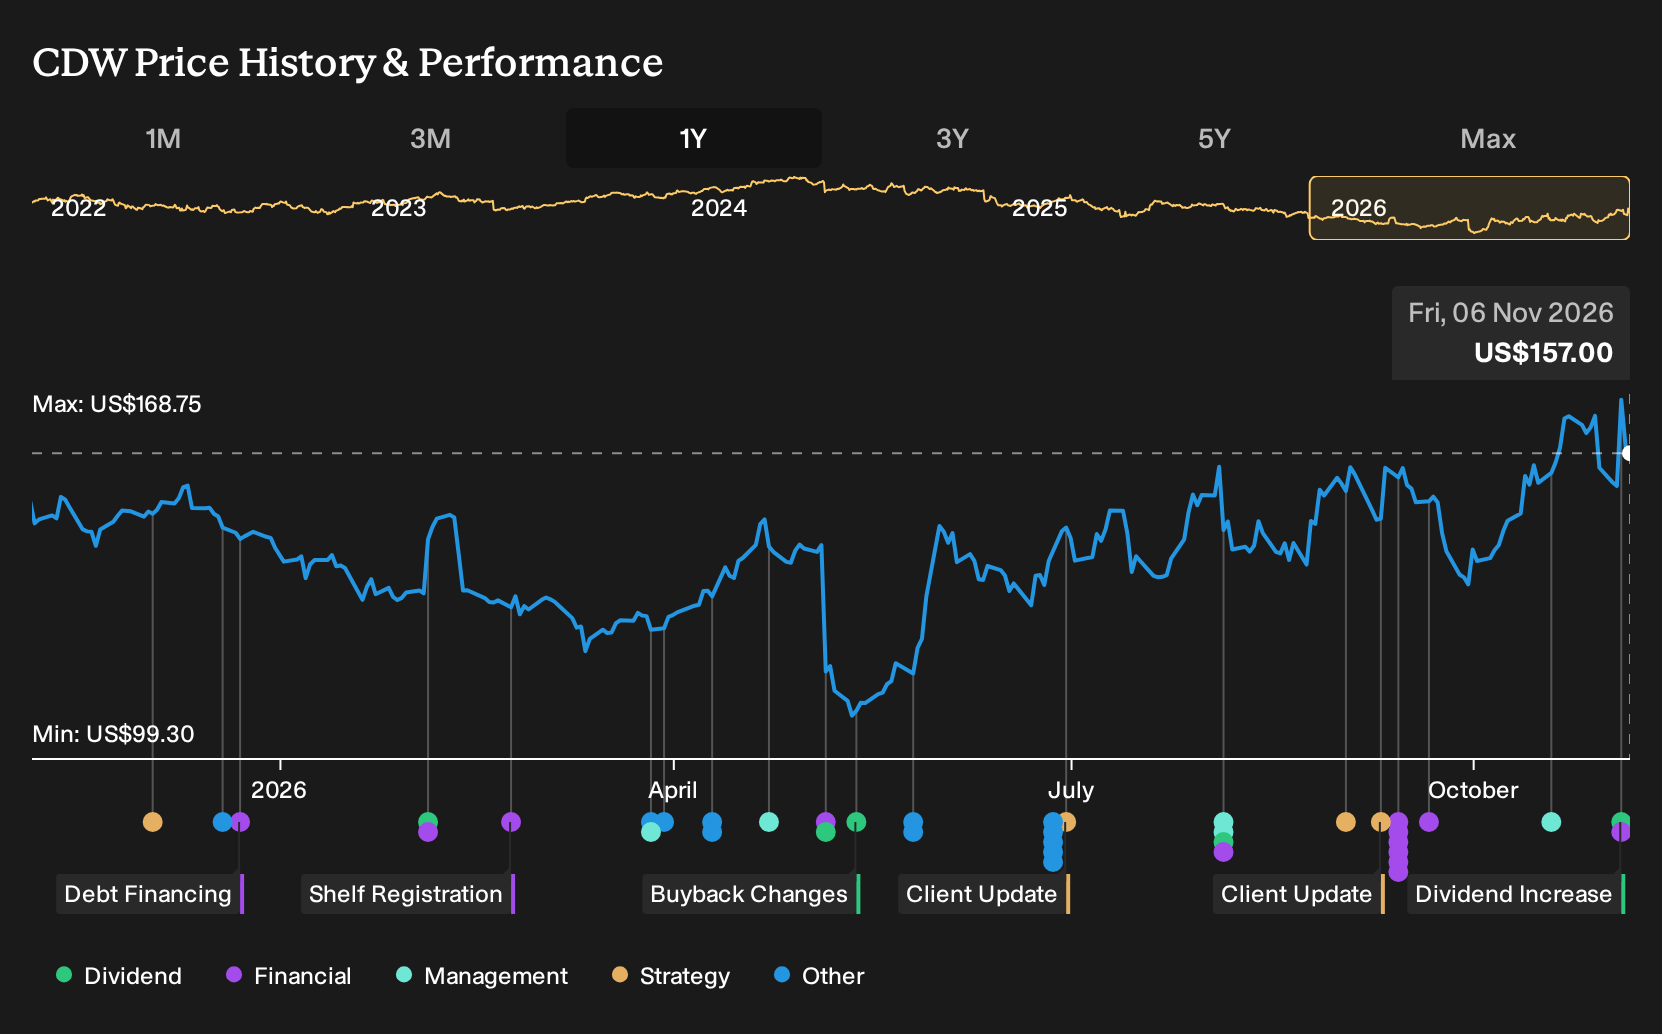
- CDW Corporation reported third quarter 2026 sales of US$6,754.5 million and net income of US$309.8 million, and its board declared a quarterly cash dividend of US$0.680 per share payable on December 10, 2026 to shareholders of record on November 25, 2026.
- Stronger third quarter and year to date earnings per share from continuing operations, alongside a higher quarterly dividend, show how CDW is currently balancing growth investment with ongoing cash returns to shareholders.
- This article considers how CDW's investment narrative is influenced by these higher earnings figures and the increased quarterly dividend.
Extend this earnings and dividend check on CDW to a wider watchlist and review a curated set of 7 dividend fortresses that pair income potential with balance sheet strength.
CDW Investment Narrative Recap
To own CDW, you need to be comfortable with a technology reseller that is leaning into AI, cloud, and security projects while still carrying a sizable hardware mix. The latest third quarter figures show revenue and earnings per share from continuing operations above the prior year, which supports that narrative but does not remove the pressure on mix or margins.
The near term swing factor remains how quickly CDW can tilt more activity toward higher value services and software while managing working capital. The key risk is that hardware heavy demand keeps gross margin and free cash flow conversion tight, which could limit flexibility just as customers are scaling complex infrastructure projects.
The most relevant update here is the third quarter 2026 earnings release. Sales of US$6,754.5 million and net income of US$309.8 million, together with higher basic and diluted earnings per share from continuing operations versus a year ago, indicate that demand for CDW solutions remains healthy across the portfolio.
This matters for catalysts around AI, security, and cloud projects because revenue growth and profit expansion give the business more room to fund services capabilities and internal efficiency programs. It also intersects with risk, since margin pressure and lower than targeted cash conversion could still constrain how CDW balances reinvestment with shareholder returns.
CDW's current analyst narrative points to revenues of US$28.7b and earnings of US$1.6b by 2029, based on forecast annual revenue growth of 5.4% and a move from US$1.1b of earnings today to that 2029 consensus. This implies an earnings increase of about US$0.5b.
Discover how CDW's fair value indicates a 9% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame the key catalyst very differently. They lean hard into CDW converting AI and data work into richer services income, with prior forecasts built on revenue reaching about US$29.4b and earnings of roughly US$1.6b by 2029. Those views were set before this dividend increase and earnings release, so opinions may evolve and it is worth comparing several viewpoints yourself.
Explore 4 other CDW fair value estimates, including one that suggests as much as 32% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment results often come from independent thinking, so consider your own analysis carefully.
- A great starting point for your CDW research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CDW. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate CDW's overall financial position at a glance.
Looking for more ideas beyond CDW?
Once you have formed a view on CDW, it often helps to widen the lens and compare it with other businesses that match your risk, income, and balance sheet preferences. The Simply Wall St Screener can help you build that wider watchlist quickly.
- If capital preservation sits near the top of your priorities, start with a filter focused on resilient companies by checking out 31 resilient stocks with low risk scores, which may offer a steadier ride through different market conditions.
- For investors who like pairing quality with potential mispricing, use a value focused filter to review 38 high quality undervalued stocks, which combine solid fundamentals with prices that screens flag as below their estimated worth.
- If balance sheet strength and underlying fundamentals matter most to you, run a filter centred on financial resilience and consider the list of solid balance sheet and fundamentals (25 results) to surface candidates that might complement or contrast with a position in CDW.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com