
3 US Oil And Gas Stocks Gaining Focus As Hydrogen Projects Stall
Hydrogen megaprojects are stalling, federal support looks shakier, and suddenly the pressure on conventional oil and gas producers feels a little lighter. As billions of dollars in planned clean energy hubs hit speed bumps, investors are rethinking where the more straightforward cash flows might sit. This article breaks down three U.S. Conventional Oil & Gas Producers that are connected to this story and explains how this shift could matter for your portfolio decisions.
The stocks covered next are just a small sample of the U.S. Conventional Oil & Gas Producers that fit this theme. The full screen surfaced 7 more listed businesses with similarly interesting stories that are not included in the article. To see the complete field and quickly identify which producers best match your own thesis, head into the U.S. Conventional Oil & Gas Producers screener to filter, analyze, and focus on your highest conviction ideas.
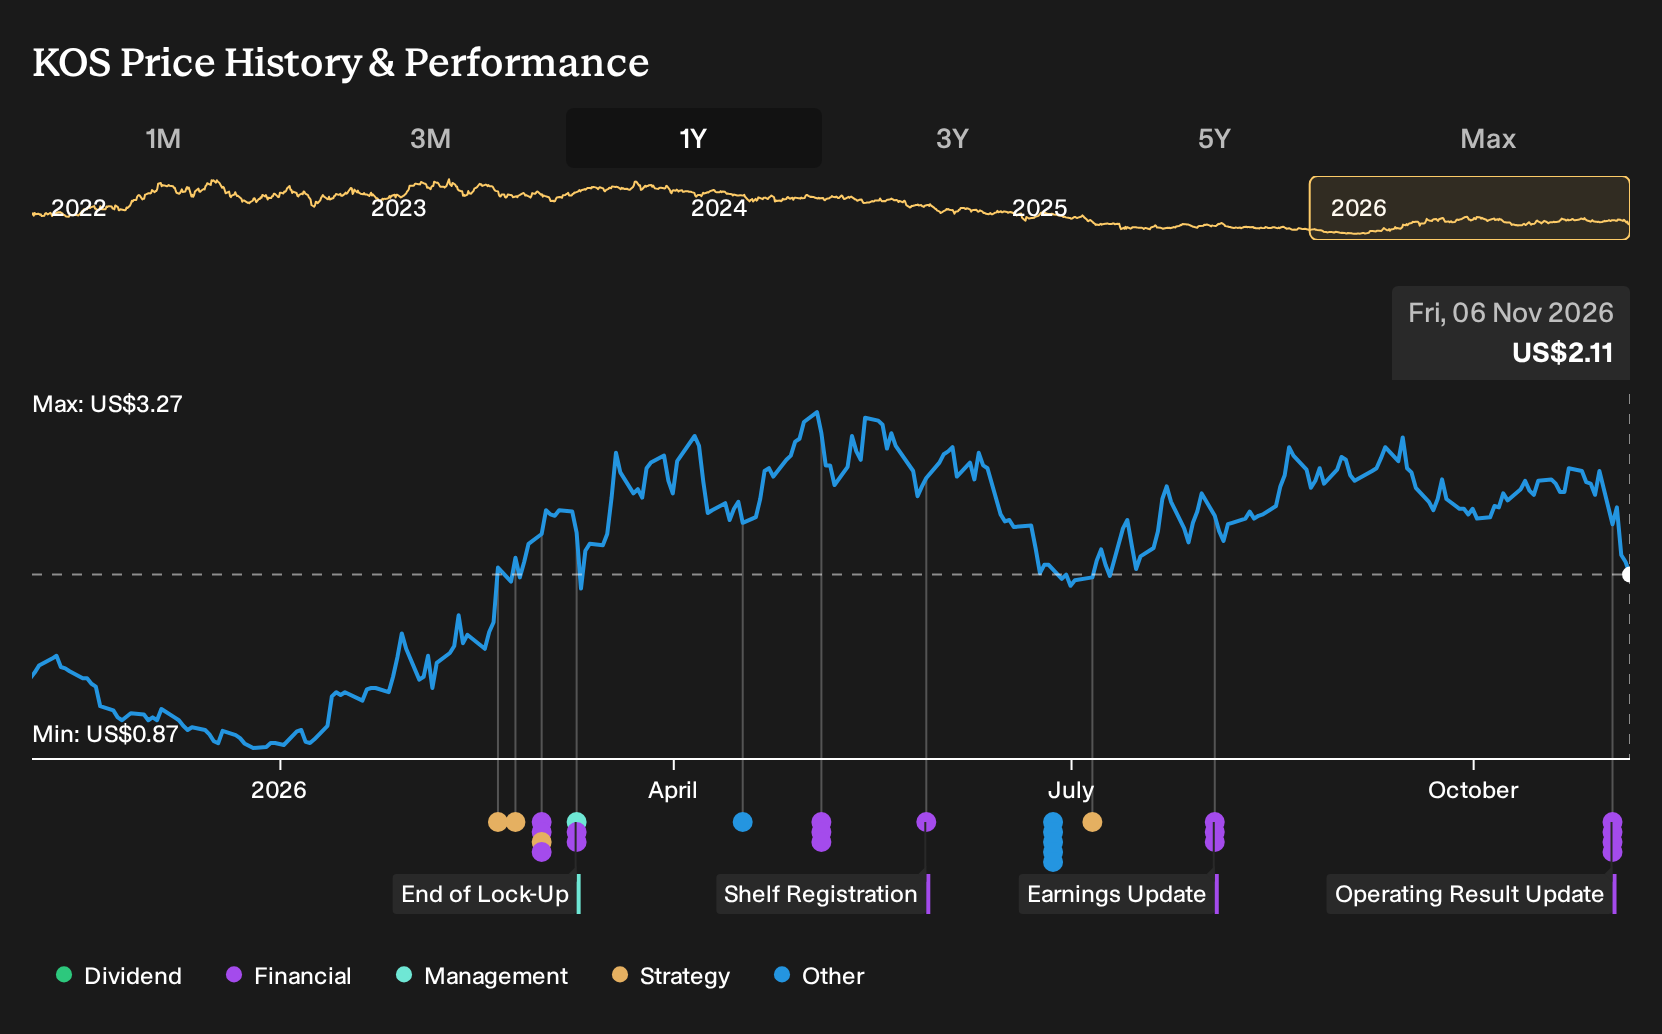
Kosmos Energy (KOS)
Kosmos Energy gives this screener direct exposure to conventional deepwater oil and gas, with cash generation tied to volumes and commodity prices rather than subsidised hydrogen projects. This is exactly why the recent reset in clean energy funding makes its progress worth watching.
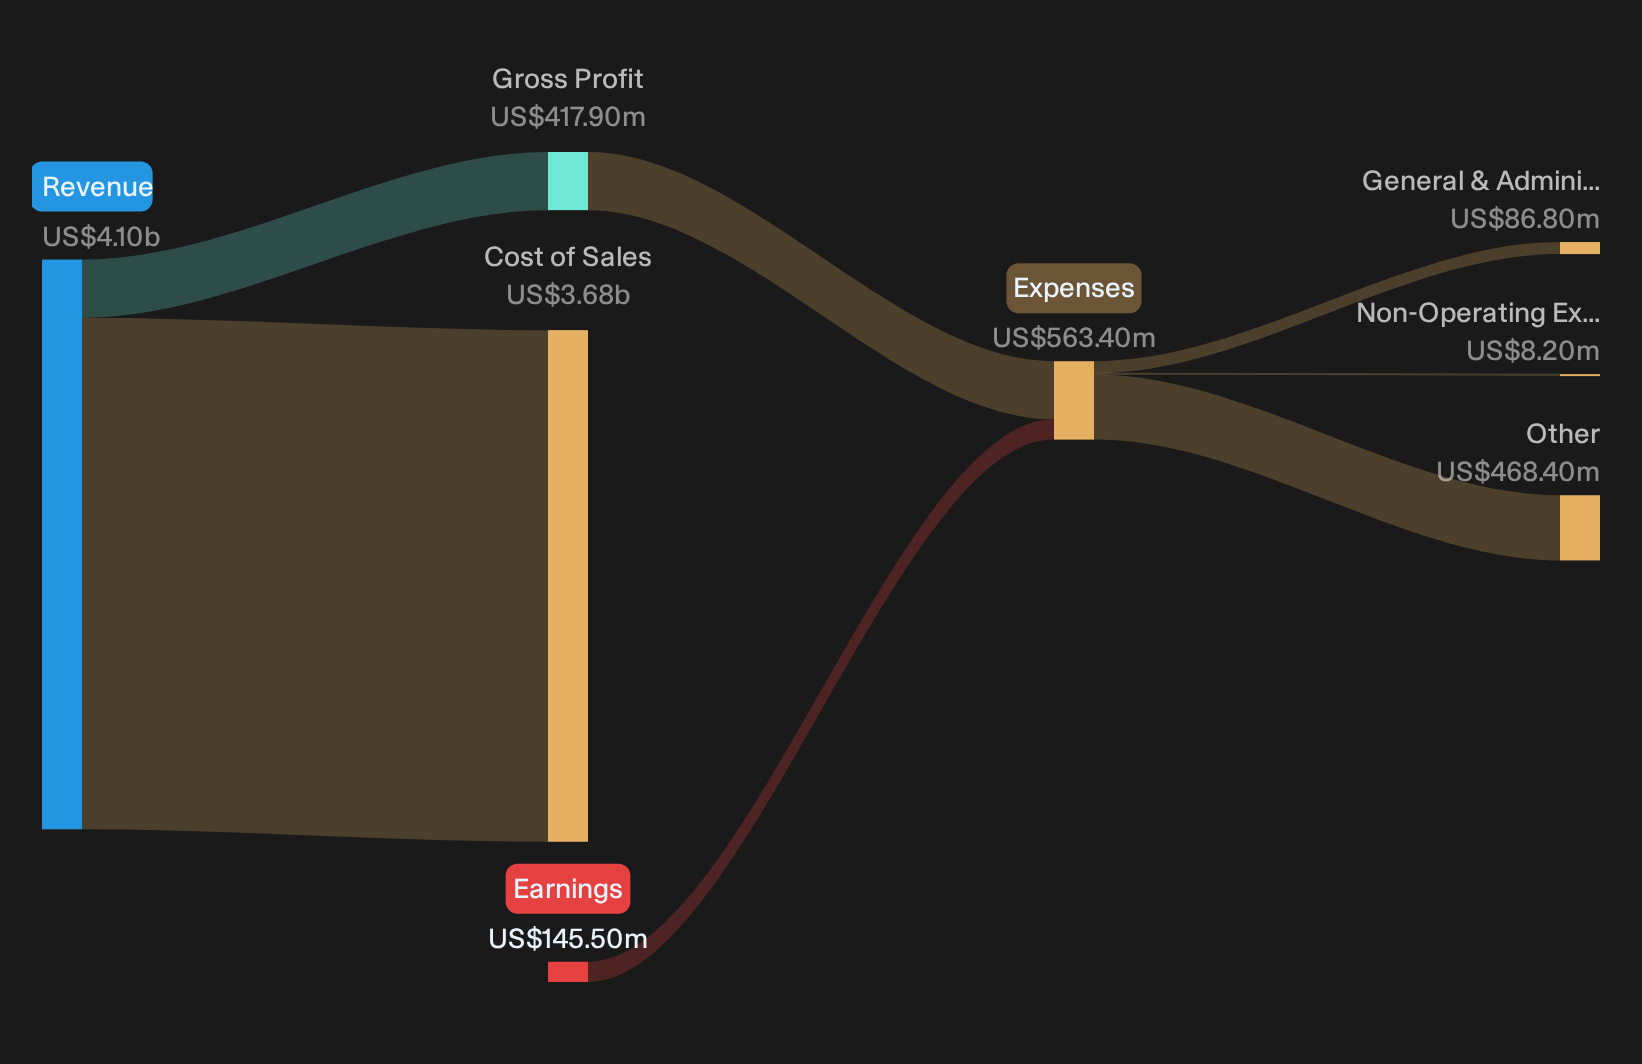
Kosmos Energy is a deepwater explorer and producer focused on oil and natural gas, generating about US$1.7b in revenue from exploration, development and production activities, and the stock carries a market value of roughly US$1.3b.
"Kosmos reported record Q1 2026 production, cut net debt by about 7% versus year-end 2025, raised its 2026 debt-reduction target to ~20%, and kept full-year capex discipline intact at about $350 million."
One question for investors is what happens if a less visible pressure on future cash costs shifts just as that operational momentum starts to bite.
If that cost curve really is shifting, read the full narrative for Kosmos Energy to see what might be accelerating beneath Kosmos Energy’s headline production and debt numbers.
Peabody Energy (BTU)
Peabody Energy is a pure-play coal miner tied to traditional hydrocarbon demand, supplying utilities and steelmakers at a time when hydrogen projects are slowing and policy support for dispatchable power is back in focus.
Peabody Energy produces metallurgical and thermal coal for power generators and steel producers, linking directly to the conventional energy theme. With a market value of about US$2.0b, investors are watching how its fossil fuel exposure responds to the policy reset around cleaner alternatives.
"Sustained tightness in seaborne coal markets, with premium hard coking coal averaging US$238 per ton and Newcastle 6,000 kcal thermal coal averaging US$137 per ton in Q2 2026, continues to support pricing for Peabody Energy’s export volumes and can feed through to stronger net margins from the seaborne segments if similar conditions persist."
The real swing factor now is how one developing policy and project trend shapes medium term demand for Peabody Energy’s coal customers.
That swing factor is exactly why reading the full narrative for Peabody Energy can help you see how Peabody Energy’s coal exposure could be accelerating or quietly stalling.
Talos Energy (TALO)
Talos Energy plugs directly into this conventional upstream theme through its Gulf focused oil, gas and natural gas liquids portfolio, while its growing carbon capture unit gives it a secondary angle on lower carbon projects without changing the core hydrocarbons story.
Talos Energy is a Houston based explorer and producer with upstream operations in the U.S. and Mexico, generating about US$2.1b in upstream revenue and a market value near US$2.5b.
"Talos Energy is still executing its targeted US$100 million per year initiative in operational efficiencies and cost reductions, and progress on the Optimal Performance Plan that had already reached more than two thirds of its 2026 target by mid year supports the original view that ongoing savings could support free cash flow, net margins and earnings."
What really matters next is how one unresolved cost and project timing pressure shapes where those future margins actually land.
Those cost and timing pressures are exactly why reading the full narrative for Talos Energy can show whether Talos Energy’s efficiency push is quietly accelerating or masking deeper risks.

Seeking Alternatives Before The Crowd Moves
Fresh ideas move first, and pricing can move even faster once momentum catches a theme. Scan these under the radar lists before the window narrows and act now.
- Target cash generative compounding with a curated 7 dividend fortresses that aims to keep income flowing even when share prices are swinging and sentiment feels scattered.
- Ride potential secular tailwinds as 53 AI infrastructure stocks tracks the companies supplying the backbone for AI demand while that story is still building under the radar for now.
- Position ahead of any renewed interest in electrification metals using the curated 16 top copper producer stocks before stronger momentum gets fully caught in market expectations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com