
Missed Ulta Beauty's Run? What Holders Had To Believe
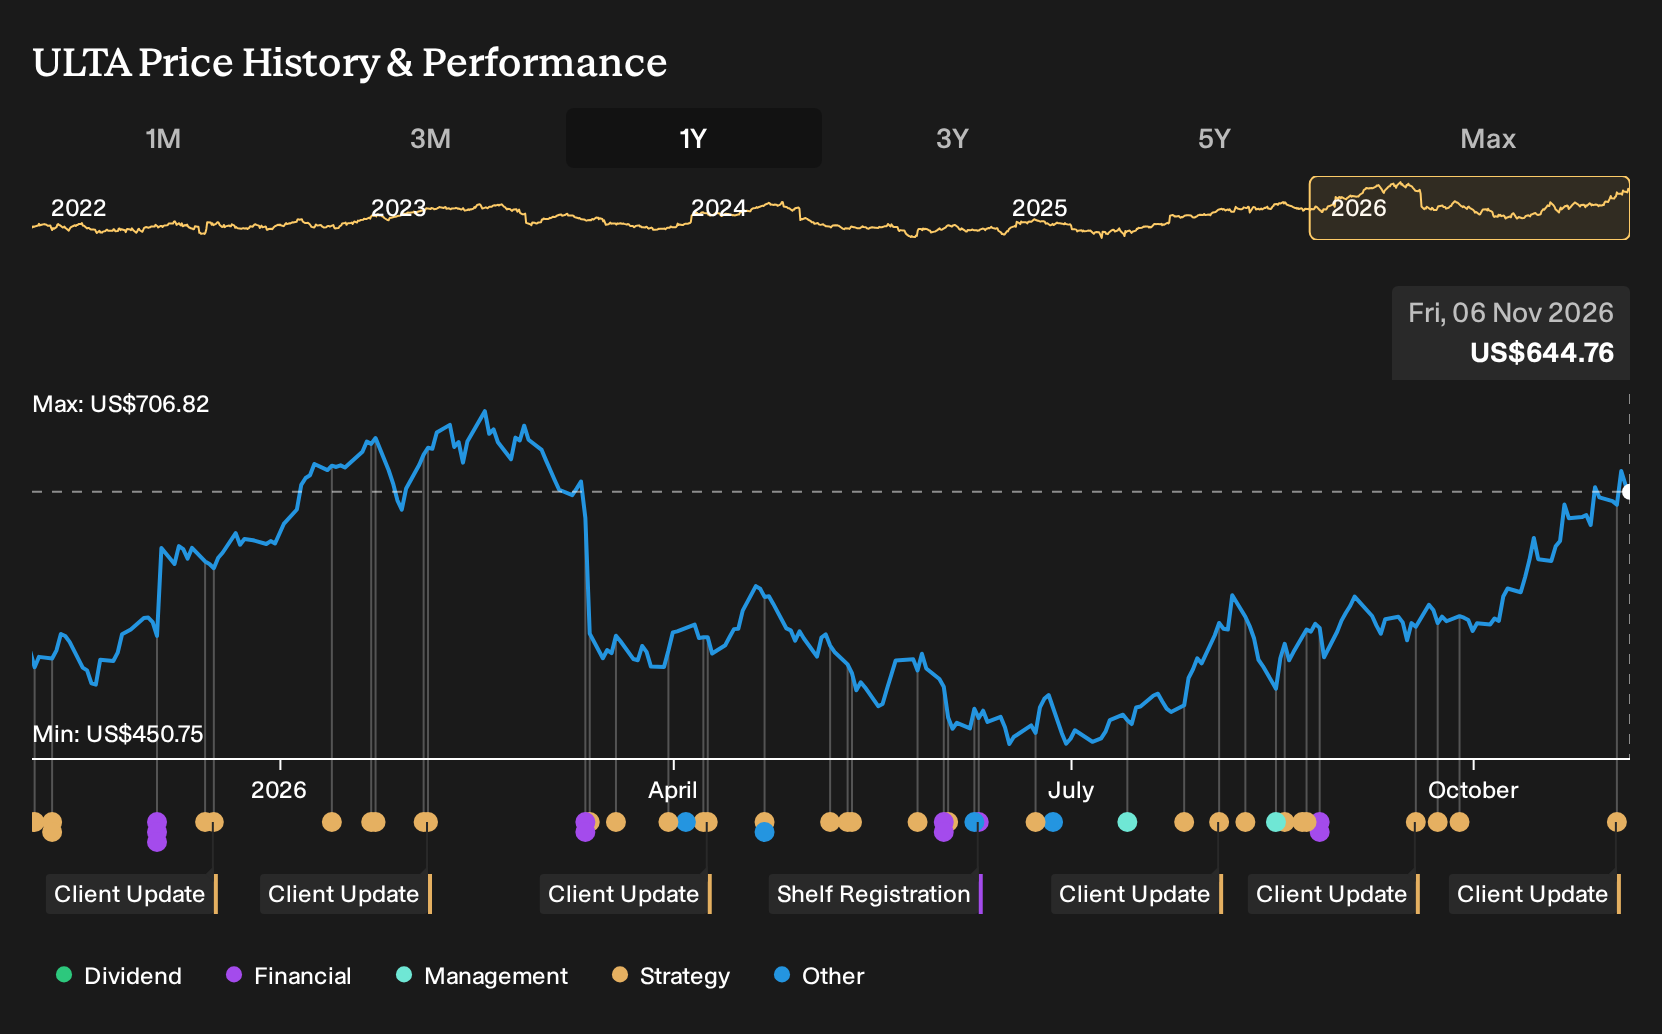
If you only read Ulta Beauty’s headlines this year, the mix of higher guidance, a Target breakup, and a Times Square flagship commitment might have felt messy rather than reassuring. Investors who held Ulta Beauty over the past year are up 24.5%, including dividends. If you had been deciding on 6 November 2025, with some investors arguing for wellness-led growth and others focused on slowing expansion and execution risk, which evidence would have deserved more weight?
If the move has made Ulta Beauty harder to judge, start where the gap is still open and scan 38 high quality undervalued stocks.
The Two Ulta Beauty Stories Investors Were Arguing About
The shares cost US$510 at the start of the period, which left Ulta Beauty holders choosing between two very different but plausible stories.
The bullish Narrative saw upside to a Fair Value of US$575, a rough guide to what the price might be if wellness expansion and digital investments delivered 5.9% annual revenue growth with profit margins at 9.2% and a future P/E of 21.8x.
The bearish Narrative pointed to a Fair Value of US$427, built on the view that a pure storefront model, international execution risk, and rising competition would slow expansion despite assumed 4.5% revenue growth, 10.6% margins, and a 16.0x future P/E.
What The Results Changed For The Ulta Beauty Debate
Ulta Beauty raised fiscal 2026 guidance after Q2 2026, then reported Q2 2027 revenue of US$3,035.7m and net income of US$282.0m, both above Q2 2026. That outcome leaned toward the wellness and digital expansion story. The slimmer net margin, which moved from 9.4% to 9.3%, kept the cautious view on profitability very much alive. Overall, the evidence cut both ways.
The key assumption investors needed to track was not just whether Ulta Beauty could grow sales, but whether earnings quality kept pace. For a similar retailer, you would want to check whether higher guidance eventually lines up with margin trends in the next set of reported results.
What Ulta Beauty’s Run Already Prices In
With Ulta Beauty now at US$645, this selected Narrative’s Fair Value sits below the current price, which signals a more cautious stance on what the recent one year 24.5% gain already assumes.
The Narrative centers on whether loyalty data, AI tools, and newer wellness adjacencies can outpace category fatigue and privacy concerns. For today’s price to hold up, a buyer needs to believe Ulta Beauty can keep converting its store network and data heavy engagement into growth without loyalty or margin damage from surveillance sensitive loss prevention.
"Ulta’s growing use of technology such as license-plate reader tools to combat retail crime has already triggered privacy concerns, which introduces a reputational overhang that could increase compliance and legal costs or dampen member engagement and ultimately weigh on net margins and earnings quality."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking One Step Beyond Ulta
Ulta Beauty focuses on helping customers feel more confident in their own skin. You could stop there or look one ring further out.
Personal care shoppers often want more than a fresh serum or new palette. They also look for smooth ways to pay, borrow, and receive what they buy.
Another business leans into that problem with a combined shopping and digital finance engine. It invests in payments, credit, and logistics that make transactions easier.
As that model develops, the real question is where the value ultimately settles. On the beauty counter, or inside the platform that quietly moves the money?
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 59% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com